


 |
市場調查報告書
商品編碼
2120552
亞太地區綠色資料中心:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)APAC Green Data Center - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,亞太地區綠色資料中心市場規模將從 2025 年的 172 億美元成長到 2026 年的 205.7 億美元,然後在 2031 年達到 503.9 億美元,2026 年至 2031 年的複合年成長率為 19.62%。
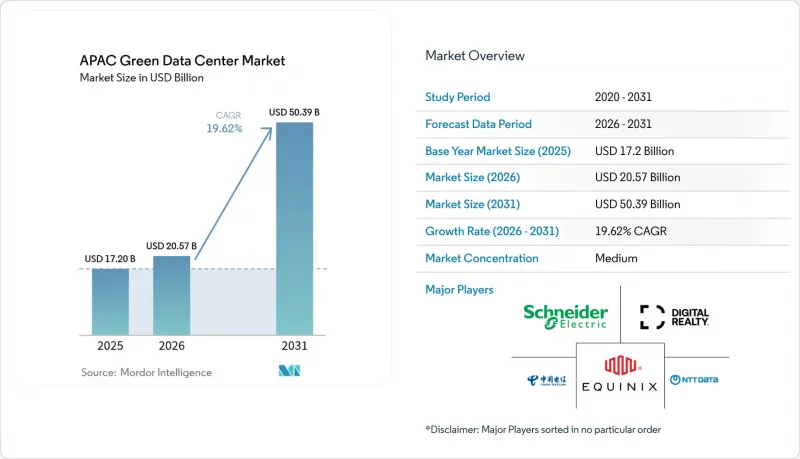
本報告按元件(服務(系統整合、監控服務等)、解決方案(電源、伺服器、管理軟體等))、資料中心類型(託管服務供應商、超大規模資料中心業者雲端服務供應商、企業邊緣運算)、產業領域(醫療保健、金融服務等)和國家/地區進行細分。市場預測以價值(美元)表示。
亞太地區綠色資料中心市場趨勢與洞察
在利用人工智慧的高密度工作負載中,液冷和混合冷卻的必要性。
GPU密集型伺服器的機架密度正從10kW迅速提升至100kW以上,推動散熱方式轉向直接冷卻、浸沒式冷卻和精密液冷系統。 SK Telecom等業者正與硬體製造商合作,將下一代溫度控管解決方案商業化,與風冷相比,這些方案可降低高達30%的能耗。 Equinix已在包括新加坡在內的100多個資料中心部署了液冷系統,以在維持其人工智慧服務效能的同時減少用水量。早期採用者可以獲得成本優勢,因為更高的機架密度可以減少所需的占地面積,並提高每平方英尺的收益。
東南亞新興大都會圈超大規模託管設施的快速擴張
泰國已撥款27億美元用於建設三個超大規模園區,而印尼則從Digital Realty獲得了1億美元的資金,用於其在雅加達的擴張。馬來西亞獲得了谷歌20億美元的投資,其中包括現場水處理設施。這些新園區將縮短新加坡和東京等面臨電力和土地限制的超大規模資料中心業者企業的部署時間,但同時,它們也給開關設備、變壓器和專業承包商等區域供應鏈帶來了壓力。
成熟樞紐城市的土地和電力供應限制
新加坡於2024年解除了為期四年的電力供應禁令,但新增供應容量僅80兆瓦,且開發人員必須遵守嚴格的能源效率標準和人工智慧賦能要求。東京也面臨類似的挑戰,電網升級未能跟上需求,迫使計畫遷往千葉和北海道。由於許可證限制,地價飆升,計畫開工也被推遲,導致資金流向吉隆坡、雅加達和曼谷。
細分市場分析
到2025年,解決方案細分市場將佔據亞太綠色資料中心市場61.62%的佔有率。這主要歸功於企業對整合電力、冷卻和自動化系統的青睞,這些系統能夠快速部署到人工智慧叢集。由於資料中心正在重新佈線以提高密度,電力設備仍然是最大的細分市場。同時,隨著液冷技術的日益普及,先進的冷卻系統也實現了兩位數的成長。儘管目前規模較小,「服務」細分市場正以21.3%的複合年成長率成長,超過了所有其他類別,這主要得益於對設計建造工程、可再生能源整合和認證諮詢的需求。預計到2031年,亞太綠色資料中心市場服務細分市場的規模將達到206.3億美元,隨著複雜維修專案的推進,該市場可望繼續擴大。能夠將軟體定義能源管理平台與液冷硬體捆綁銷售的供應商正在成為超大規模超大規模資料中心業者營運商的「一站式」合作夥伴。
企業也在碳核算審計、綠色債券結構設計和購電協議 (PPA) 談判等領域利用專業服務。例如,亞馬遜在東京一個建築專案中使用水泥替代品,將隱含碳排放量減少了 64%,這種低碳材料凸顯了組件創新與服務諮詢之間的緊密聯繫。能夠整合電氣、機械和 IT 系統的整合專家可以降低試運行風險,並縮短投資者的獲利週期。
預計到2025年,託管服務提供者將佔據35.62%的市場佔有率,對於那些尋求可擴展容量但又不想進行前期投資的超大規模資料中心業者而言,它們仍然至關重要。然而,受人工智慧模型訓練和自主雲端合約的驅動,超大規模資料中心才是主要的成長動力,預計將實現23.6%的複合年成長率。預計到2031年,亞太地區與超大規模資料中心業者資料中心相關的綠色資料中心市場規模將成長三倍以上。雅加達、柔佛和巴淡島的土地收購競爭日益激烈,像TikTok這樣的公司承諾在五年內投資88億美元在泰國託管伺服器。
為了應對這項挑戰,託管公司紛紛提供液冷閒置頻段、晶片直接冷卻通道以及每機架超過 40kW 的高密度電源。同時,超大規模資料中心業者正在擴大其在「過渡區域」的託管服務,因為這些區域的自建進度無法滿足需求。電信業者的邊緣部署也帶來了新的變化,在 5G 基地台附近部署微型站點以支援即時分析。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在利用人工智慧的高密度工作負載中,液冷和混合冷卻的必要性。
- 東南亞新興大都會圈超大規模託管設施的快速擴張
- 政府強制推行淨零排放和綠色稅收優惠政策。
- 透過公司間購電協議(PPA)實現電網脫碳和加速可再生能源採購
- 鮮為人知:小型模組化反應器(SMR)零碳基礎供電示範項目
- 鮮為人知的是:房地產投資信託基金類型的綠色金融正在降低華盛頓特區開發商的加權平均資本成本。
- 市場限制因素
- 成熟樞紐城市(如新加坡、東京)的土地和電力供應限制
- 三級及以上永續建築項目存在較高的資本投資溢價(15-20%)。
- 先進冷卻技術和資料中心互連管理(DCIM)領域技術純熟勞工短缺。
- 鮮為人知的是:水資源緊張法規限制了蒸發冷卻
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 評估宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 按組件
- 服務
- 系統整合
- 監控服務
- 專業服務
- 其他
- 解決方案
- 電源
- 冷卻
- 伺服器
- 網路裝置
- 管理軟體
- 其他解決方案
- 服務
- 依資料中心類型
- 託管服務提供者
- 超大規模資料中心業者雲端服務供應商
- 企業邊緣
- 層級特定
- 一級和二級
- 三級
- 第四級
- 按行業細分
- 衛生保健
- 金融服務
- 政府
- 通訊/IT
- 製造業
- 媒體與娛樂
- 其他
- 國家
- 中國
- 印度
- 日本
- 馬來西亞
- 澳洲
- 印尼
- 泰國
- 新加坡
- 韓國
- 其他亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Fujitsu Limited
- Cisco Systems Inc.
- HP Inc.
- Dell Technologies Inc.
- Hitachi Ltd.
- Schneider Electric SE
- IBM Corporation
- Eaton Corporation plc
- Vertiv Holdings Co
- Equinix Inc.
- Digital Realty Trust Inc.
- NTT DATA Group Corp.
- China Telecom Corp. Ltd.
- ST Telemedia Global Data Centres
- Keppel DC REIT
- AirTrunk Operating Pty Ltd.
- Huawei Technologies Co. Ltd.
- Amazon Web Services Inc.
- Microsoft Corp.
- Alibaba Cloud Computing Co. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Asia-Pacific green data center market size is expected to grow from USD 17.2 billion in 2025 to USD 20.57 billion in 2026 and is forecast to reach USD 50.39 billion by 2031 at 19.62% CAGR over 2026-2031.
This report is Segmented by Services (System Integration, Monitoring Services, and More), Solutions (Power, Servers, Management Software, and More), Users (Colocation Providers, Cloud Service Providers, Enterprises), End-User Industries (Healthcare, Financial Services, and More), and by Country. The Market Forecasts are Provided in Terms of Value (USD).
APAC Green Data Center Market Trends and Insights
AI-Driven High-Density Workloads Require Liquid and Hybrid Cooling
Rack densities have ballooned from 10 kW to beyond 100 kW for GPU-rich servers, prompting a shift toward direct, immersion, and precision liquid cooling systems. Operators such as SK Telecom are partnering with hardware manufacturers to commercialize next-generation thermal solutions that can trim energy use by up to 30% compared with air cooling. Equinix is rolling out liquid cooling in more than 100 facilities, including Singapore, to maintain performance for AI services while curbing water usage. Early adopters gain a cost advantage because higher rack density reduces floor space requirements and accelerates revenue per square foot.
Rapid Hyperscale and Colocation Build-Outs Across Emerging Southeast Asia Metros
Thailand has earmarked USD 2.7 billion for three hyperscale campuses, while Indonesia is receiving USD 100 million from Digital Realty for a Jakarta expansion. Malaysia has attracted a USD 2 billion pledge from Google that includes on-site water-treatment plants. New sites in these markets shorten deployment timelines for hyperscalers facing power and land caps in Singapore and Tokyo, though they strain regional supply chains for switchgear, transformers, and specialist contractors.
Land and Power Moratoriums in Mature Hubs
Singapore lifted its four-year moratorium in 2024 but released only 80 MW of new capacity, pushing developers to meet strict efficiency and AI-readiness rules. Tokyo faces similar challenges as grid upgrades lag demand, forcing projects to relocate to Chiba or Hokkaido. Limited permits inflate land prices and slow project starts, redirecting capital toward Kuala Lumpur, Jakarta, and Bangkok.
Other drivers and restraints analyzed in the detailed report include:
- Government Net-Zero Mandates and Green-Tax Incentives
- Grid Decarbonization and Corporate PPAs Accelerating Renewable Sourcing
- Skilled-Labour Shortage for Advanced Cooling and DCIM
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions captured 61.62% share of the Asia-Pacific green data center market in 2025 as enterprises favor integrated power, cooling, and automation stacks that can be deployed quickly for AI clusters. Power equipment remains the largest subsegment because facilities are re-wiring electrical backbones for higher density, while advanced cooling systems record double-digit growth as liquid technologies spread. Services are smaller today yet outpace all other categories with a 21.3% CAGR, fueled by demand for design-build engineering, renewable-energy integration, and certification consulting. The Asia-Pacific green data center market size for Services is projected to reach USD 20.63 billion by 2031, expanding alongside complex retrofits. Vendors able to bundle software-defined energy-management platforms with liquid cooling hardware position themselves as single-throat-to-choke partners for hyperscalers.
Enterprises also turn to professional services for carbon-accounting audits, green-bond structuring, and power-purchase agreement negotiations. Low-carbon materials, such as Amazon's cement replacements that cut embodied carbon by 64% in Tokyo builds, underscore how component innovation dovetails with service advisory. Integration specialists who can orchestrate electrical, mechanical, and IT systems reduce commissioning risk, shortening revenue realization cycles for investors.
Colocation operators held a 35.62% share in 2025 and remain vital for enterprises seeking scalable capacity without upfront capital. Yet hyperscalers, propelled by AI model training and sovereign-cloud contracts, are registering a 23.6% CAGR, making them the primary growth locomotive. The Asia-Pacific green data center market size tied to hyperscalers is projected to more than triple by 2031. Competition for land bank parcels in Jakarta, Johor, and Batam is intensifying as companies like TikTok pledge USD 8.8 billion over five years for Thailand hosting.
Colocation firms respond by offering liquid-ready white space, direct-to-chip cooling corridors, and high-density power feeds exceeding 40 kW per rack. Hyperscalers, in turn, expand colocation usage for on-ramp regions where self-build timelines exceed demand. Edge deployments by telecom operators add another layer, requiring micro-sites near 5G base stations to support real-time analytics.
Complete Report Scope:
- By Component
- Service
- System Integration
- Monitoring Services
- Professional Services
- Other Services
- Solution
- Power
- Cooling
- Servers
- Networking Equipment
- Management Software
- Other Solutions
- Service
- By Data Center Type
- Colocation Providers
- Hyperscalers/Cloud Service Providers
- Enterprise and Edge
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Industry Vertical
- Healthcare
- Financial Services
- Government
- Telecom and IT
- Manufacturing
- Media and Entertainment
- Other Verticals
- By Country
- China
- India
- Japan
- Malaysia
- Australia
- Indonesia
- Thailand
- Singapore
- South Korea
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Fujitsu Limited
- Cisco Systems Inc.
- HP Inc.
- Dell Technologies Inc.
- Hitachi Ltd.
- Schneider Electric SE
- IBM Corporation
- Eaton Corporation plc
- Vertiv Holdings Co
- Equinix Inc.
- Digital Realty Trust Inc.
- NTT DATA Group Corp.
- China Telecom Corp. Ltd.
- ST Telemedia Global Data Centres
- Keppel DC REIT
- AirTrunk Operating Pty Ltd.
- Huawei Technologies Co. Ltd.
- Amazon Web Services Inc.
- Microsoft Corp.
- Alibaba Cloud Computing Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-driven high-density workloads require liquid and hybrid cooling
- 4.2.2 Rapid hyperscale and colocation build-outs across emerging SE-Asia metros
- 4.2.3 Government net-zero mandates and green-tax incentives
- 4.2.4 Grid decarbonisation and corporate PPAs accelerating renewable sourcing
- 4.2.5 Under-reported: SMR (Small Modular Reactor) pilots for zero-carbon baseload
- 4.2.6 Under-reported: REIT-style green financing lowering WACC for DC developers
- 4.3 Market Restraints
- 4.3.1 Land and power moratoriums in mature hubs (e.g., Singapore, Tokyo)
- 4.3.2 High capex premium (15-20 %) for Tier III+ sustainable builds
- 4.3.3 Skilled-labour shortage for advanced cooling and DCIM
- 4.3.4 Under-reported: Water-stress regulations limiting evaporative cooling
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of the Impact of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Service
- 5.1.1.1 System Integration
- 5.1.1.2 Monitoring Services
- 5.1.1.3 Professional Services
- 5.1.1.4 Other Services
- 5.1.2 Solution
- 5.1.2.1 Power
- 5.1.2.2 Cooling
- 5.1.2.3 Servers
- 5.1.2.4 Networking Equipment
- 5.1.2.5 Management Software
- 5.1.2.6 Other Solutions
- 5.1.1 Service
- 5.2 By Data Center Type
- 5.2.1 Colocation Providers
- 5.2.2 Hyperscalers/Cloud Service Providers
- 5.2.3 Enterprise and Edge
- 5.3 By Tier Type
- 5.3.1 Tier 1 and 2
- 5.3.2 Tier 3
- 5.3.3 Tier 4
- 5.4 By Industry Vertical
- 5.4.1 Healthcare
- 5.4.2 Financial Services
- 5.4.3 Government
- 5.4.4 Telecom and IT
- 5.4.5 Manufacturing
- 5.4.6 Media and Entertainment
- 5.4.7 Other Verticals
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 Malaysia
- 5.5.5 Australia
- 5.5.6 Indonesia
- 5.5.7 Thailand
- 5.5.8 Singapore
- 5.5.9 South Korea
- 5.5.10 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Fujitsu Limited
- 6.4.2 Cisco Systems Inc.
- 6.4.3 HP Inc.
- 6.4.4 Dell Technologies Inc.
- 6.4.5 Hitachi Ltd.
- 6.4.6 Schneider Electric SE
- 6.4.7 IBM Corporation
- 6.4.8 Eaton Corporation plc
- 6.4.9 Vertiv Holdings Co
- 6.4.10 Equinix Inc.
- 6.4.11 Digital Realty Trust Inc.
- 6.4.12 NTT DATA Group Corp.
- 6.4.13 China Telecom Corp. Ltd.
- 6.4.14 ST Telemedia Global Data Centres
- 6.4.15 Keppel DC REIT
- 6.4.16 AirTrunk Operating Pty Ltd.
- 6.4.17 Huawei Technologies Co. Ltd.
- 6.4.18 Amazon Web Services Inc.
- 6.4.19 Microsoft Corp.
- 6.4.20 Alibaba Cloud Computing Co. Ltd.
7 MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026年全球綠色資料中心電力市場報告
 綠色電信發展趨勢(2026):人工智慧驅動的電力需求與液冷資料中心
 歐洲綠色資料中心:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 綠色資料中心市場:按組件、資料中心類型、冷卻方式和最終用戶分類-2026-2032年全球市場預測
 綠色資料中心市場:產業趨勢及2035年全球預測-按組件類型、資料中心規模、最終用戶、產業和地區分類
 綠色資料中心市場:按組件、類型、容量、部署方式、最終用途、國家和地區分類-全球產業分析、市場規模及佔有率、未來預測(2026-2033)
 綠色資料中心市場預測至2034年:按組件、企業規模、最終用戶和地區分類的全球分析綠色銀行解決方案市場預測至2034年-按解決方案類型、銀行職能、技術、部署模式和最終用戶分類的全球分析
 2026-2030年全球綠色資料中心(GDC)市場綠色資料中心:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)