


 |
市場調查報告書
商品編碼
2120541
精密農業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Precision Farming - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
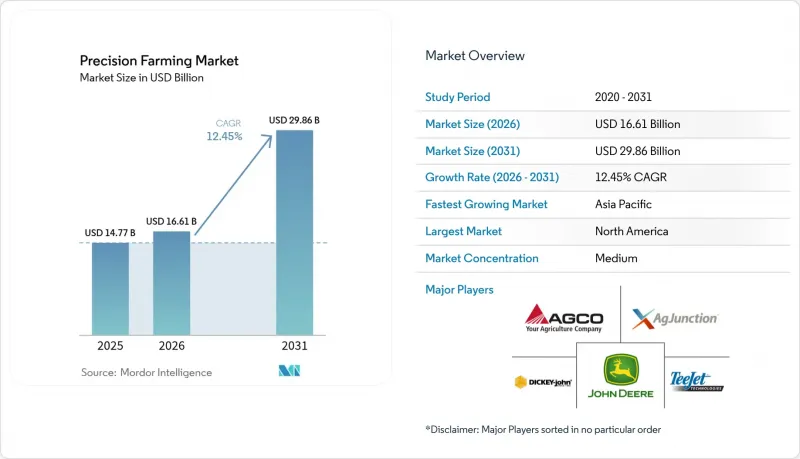
根據 Mordor Intelligence 估計,精密農業市場在 2026 年的價值將達到 166.1 億美元,高於 2025 年的 147.7 億美元,預計到 2031 年將達到 298.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 12.45%。
本報告按技術(導航系統、遙感探測、變數施肥技術、無人機/無人飛行器 (UAV) 及其他)、組件(硬體、軟體、服務)、應用(產量監測、變數噴灑、田間測繪、土壤/作物健康監測及其他)、農場規模(小規模、中型、大型農場)和地區進行細分。市場預測以美元 (USD) 為單位。
全球精密農業市場趨勢及洞察
大型農場中GNSS自動駕駛技術的應用迅速成長
在面積超過1000公頃的農場中,GNSS輔助自主導航的採用率已達到70%,超過了中型農場52%的採用率。這一趨勢正日益影響精密農業市場,這主要得益於約翰迪爾StarFire 7000接收器的普及,該接收器能夠捕捉更多衛星頻寬並加速融合。 SpaceX的Starlink即使在沒有行動電話網路覆蓋的區域也回程傳輸傳導航數據,使操作員能夠晝夜自主導航。 AGCO的OutRun維修套件相容於其他品牌的曳引機,方便為擁有多種不同類型機械的農場升級導航功能。隨著人手不足日益嚴重,引入機器人替代稀缺操作員的價值也日益凸顯,因為機器人可以保持作物行筆直,減少重複勞動,並節省柴油。在有限的播種季節,降低燃料成本和最大限度地提高機器運作進一步提升了投資回報率。
頻譜熱成像無人機感測器的成本快速降低
目前,全球已有超過30萬架農業無人機管理超過5億公頃的農田,而大疆創新(DJI)的Mavic 3多光譜無人機如今已以以往只有大型農場才能負擔得起的價格上市。在蒙大拿州一家小麥農場進行的測試表明,將定點噴灑無人機與WEED-IT視覺系統相結合,可減少90-95%的除草劑用量。較小的感測器在保持光譜解析度的同時,減輕了有效載荷重量,並使飛行時間延長了一倍,從而能夠測量葉綠素和冠層濕度。巴西和美國放寬了管制,擴大了超視距飛行的作業範圍,加速了其在廣袤農田的應用。人工智慧驅動的異常檢測技術能夠比肉眼提前一周識別營養脅迫,使農民能夠在產量下降之前採取相應的措施。
不同製造商機器之間的資料互通性差距
約73%的農戶使用多家原廠(OEM)的曳引機、播種機和噴藥機,造成了資料孤島,阻礙了端到端的分析。儘管OGC的SensorThings API承諾為地理空間和農業機械資料提供通用封裝,但專有文件格式和不同的CAN總線協定阻礙了資料的無縫流動。 AGCO和Trimble的合資企業PTx承諾提供與品牌無關的轉向和資料同步功能,但對老舊機械進行改裝成本高昂,且需要經銷商的專業技術。歐洲開放標準和MQTT傳輸層的進步是一個積極的徵兆,但小型供應商擔心產品同質化,因此採用速度緩慢。如果沒有標準化,農民將繼續依賴U盤和雲端平台,無法充分獲得完全自主化所帶來的生產力提升。
細分市場分析
2025年,導航系統在精密農業市場中維持著37.45%的領先市場佔有率。這得歸功於強大的GNSS接收器,即使在崎嶇不平的地形上,也能以亞英寸級的精度引導機器作業。預計到2031年,可變施肥技術的精密農業市場將以13.55%的複合年成長率成長。這主要是由於化肥和農藥價格上漲,對精準施肥的需求日益成長。在無人機遙感探測,價格更親民的頻譜感測器正被廣泛應用。根據大疆創新(DJI)的一份報告顯示,基於地圖數據控制複合噴霧器已使農藥用量減少了67.78%。隨著創業投資資金轉向邊緣人工智慧平台,機器人的應用也不斷擴展。 Four Growers和Bonsai Robotics已聯合融資2,400萬美元,用於在50萬英畝農地上實現收割自動化。衛星物聯網透過傳輸行動電話訊號無法覆蓋的農田的感測器輸入數據,為該系統提供補充,從而確保自動駕駛模組的模型始終保持最新狀態。
邊緣運算和雲端分析協同工作。邊緣硬體即時處理影像串流,而雲端引擎則分析季節性模式。約翰迪爾的第二代自動駕駛技術堆疊整合了這兩層,目標是在本世紀末實現玉米和大豆的完全自動駕駛。農民越來越傾向於使用多種品牌的設備來改造他們的農機設備,而不是全部更換為單一品牌。 AGCO公司憑藉其OutRun套件抓住了這一趨勢,該套件無需農民高成本更換曳引機。鑑於這些趨勢,能夠結合開放API和獨立於硬體的組件的技術供應商最有希望贏得不斷成長的耕地面積。
2025年,包括感測器、控制器、無人機和自動駕駛平台在內的硬體將佔精密農業市場51.20%的佔有率。然而,軟體銷售額正以13.40%的複合年成長率成長,因為邊緣人工智慧即使在網路連線中斷的情況下也能提供可在數秒內執行的方案。感測器已經變得像郵票一樣小,這使得即使是小規模農戶也能部署高密度土壤濕度測量網格,從而建立變數灌溉地圖。像約翰迪爾G5-Plus這樣的顯示器具備乙太網路功能,可以將更豐富的資料集從農機具傳輸到駕駛室。汽車電腦將GNSS、機器視覺和遙測功能整合到單一電路板上,顯著降低了自動駕駛迴路的延遲。
隨著營運商越來越依賴第三方合作夥伴進行軟體修補程式和網路威脅即時監控,精密農業託管服務的市場規模預計將會擴大。 CNH 和 Raven 的數據分析套件透過人工智慧驅動的選擇性噴灑,可將除草劑用量減少 77%。衛星回程傳輸確保田間作業期間配方資料的同步,這對於 4G 通訊無法覆蓋的 77% 農地至關重要。隨著硬體利潤率的收緊,供應商正在尋求透過捆綁更新、演算法和排碳權報告儀表板的訂閱模式來獲得永續的收入來源。
區域分析
2025年,北美地區將維持41.15%的區域市場佔有率,這得益於其成熟的全球導航衛星系統(GNSS)網路、完善的經銷商體係以及允許碳排放專案採用數位化文件的法規環境。與新興地區相比,北美市場成長已趨於平緩,部分原因是2025年農業工人調查顯示,在商品價格波動的大背景下,北美地區採取了較為謹慎的資本規劃。預計北美地區較低的市場需求將由老舊顯示器的強勁更新換代週期以及向全自動系統的擴展來維持。
亞太地區精密農業市場成長率最高,達13.95%。這主要得益於印度智慧農業市場的發展,預計2028年市場規模將達到8.8621億美元,以及中國對數位農業的政策支持。政府資助的衛星星系、低成本無人機以及農村地區的寬頻投資,都在推動小規模農戶在田間地頭採用這些技術。 2024年,超過12億美元的創業投資將用於自動化果園噴藥機和農業金融科技信用評分系統,將投入資金與感測器檢驗的田間數據結合。在澳大利亞,由於引入了自動化大面積農機以緩解長期存在的勞動力短缺問題,耕地面積正在逐步擴大。
在歐洲,隨著環境法規要求在2030年將化學品使用量減少50%,精準噴灑被視為一種合規手段,相關工作正在穩步推進。德國的田間試驗證實,農藥使用量可減少10%至20%,且不會影響產量,增強了農民的信心。拉丁美洲的推廣速度各不相同。在巴西和阿根廷,由於乾旱導致的收入損失,2024年曳引機的購買量下降了14%,但無人機噴灑在放鬆管制後迅速發展。在中東和非洲,無人機噴灑仍處於起步階段。對撒哈拉以南非洲的農民來說,衛星物聯網是一條生命線,儘管RTK網路覆蓋率上限為40%,但成本效益和技能缺乏正在減緩其普及速度。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 大型農場中GNSS自動駕駛技術的應用迅速成長
- 頻譜熱成像無人機感測器的成本快速降低
- 政府碳權計劃,根據碳排放量的波動性獎勵投入減少量
- 整合衛星物聯網衛星群進行現場遙測,實現亞英吋級精度。
- 採用人工智慧風險評分的農場可享保險費折扣。
- 創業投資資金從農業管理SaaS轉向邊緣人工智慧機器人
- 市場限制因素
- 不同製造商機器之間的資料互通性差距
- 針對農場營運技術網路的遍遠地區網路安全威脅
- 撒哈拉以南非洲地區的RTK網路覆蓋範圍停滯不前。
- 農業工人抵制演算法決策,喪失自主權
- 工業生態系分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過技術
- 導航系統
- GNSS/GPS
- GIS
- 可變利率技術
- 變數施肥技術
- 可變播種率技術
- 變數農藥施用技術
- 遙感探測
- 無人機和無人駕駛飛行器(UAV)
- 機器人和自主設備
- 邊緣和雲端分析平台
- 其他
- 導航系統
- 按組件
- 硬體
- 感測器和執行器
- 控制器顯示幕
- 車輛計算與互聯
- 軟體
- 農業管理軟體即服務
- 數據分析與人工智慧
- 服務
- 整合諮詢
- 託管服務
- 硬體
- 透過使用
- 產量監測
- 變數噴灑
- 實地測繪
- 監測土壤和作物健康狀況
- 灌溉管理
- 作物生長狀況調查
- 收割自動化和物流
- 其他
- 按農場規模
- 小規模農場(少於100公頃)
- 中型農場(100-1000公頃)
- 大型農場(超過1000公頃)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 肯亞
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Deere and Company
- Trimble Inc.
- AGCO Corporation
- CNH Industrial NV
- Raven Industries
- Topcon Positioning Systems
- Lindsay Corporation
- TeeJet Technologies
- DICKEY-john
- BASF Digital Farming(xarvio)
- Yara International ASA
- Climate Corp(Bayer)
- Hexagon Agriculture
- CropX Technologies
- DJI Agriculture
- Farmers Edge
- Granular
- Ag Leader Technology
- Kubota Smart Agri
- Sentera
第7章 市場機會與未來展望
According to Mordor Intelligence, precision farming market size in 2026 is estimated at USD 16.61 billion, growing from 2025 value of USD 14.77 billion with 2031 projections showing USD 29.86 billion, growing at 12.45% CAGR over 2026-2031.
This report is Segmented by Technology (Guidance Systems, Remote Sensing, Variable-Rate Technology, Drones and UAVs, and More), Component (Hardware, Software, and Services), Application (Yield Monitoring, Variable-Rate Application, Field Mapping, Soil and Crop Health Monitoring, and More), Farm Size (Small, Medium, and Large Farms), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Precision Farming Market Trends and Insights
GNSS-Enabled Auto-Steering on Large Farms
Adoption of GNSS auto-steering has reached 70% on farms over 1,000 ha versus 52% on midsize holdings, a trend increasingly shaping the precision farming market, aided by John Deere's StarFire 7000 receiver that locks onto more satellite bands for faster convergence. SpaceX Starlink backhauls the guidance data where cellular networks fail, letting operators run autonomous passes throughout the day and night. AGCO's OutRun retrofit kit democratizes steering upgrades for mixed fleets, supporting tractors from rival brands. Labor shortages heighten the value proposition by substituting scarce operators with robotics that maintain perfectly straight rows, suppress overlap, and conserve diesel. Return on investment is amplified through reduced fuel costs and higher field-hour utilization that push machinery farther during tight planting windows.
Rapid Cost Declines in Multispectral/Thermal Drone Sensors
More than 300,000 agricultural drones now treat over 500 million ha worldwide, with DJI's Mavic 3 Multispectral priced below the threshold once reserved for large farms. Farm trials on Montana wheat show 90-95% herbicide savings when spot-spray drones are paired with WEED-IT vision systems. Sensor miniaturization has lowered payload weight, doubling flight endurance while preserving spectral resolution for chlorophyll and canopy moisture readings. Regulatory easing in Brazil and the United States has widened the operational envelope for beyond-visual-line-of-sight flights, accelerating adoption on broad-acre crops. AI-enabled anomaly detection now flags nutrient stress a week sooner than the naked eye, letting growers intervene before yield loss sets in.
Data-Interoperability Gaps Among Mixed-Brand Machinery
Roughly 73% of growers operate tractors, planters, and sprayers from multiple OEMs, creating data silos that handicap end-to-end analytics. The OGC SensorThings API promises a universal wrapper for geospatial and machinery data, yet proprietary file formats and differing CAN bus protocols block seamless flows. AGCO's PTx Trimble venture pledges brand-agnostic steering and data sync, but retrofits on legacy rigs are costly and require dealership expertise. Europe's push for open standards and MQTT transport layers is a positive signal, though adoption lags smaller vendors who fear commoditization. Without convergence, farmers continue to juggle USB sticks and cloud portals, capping the productivity gains that full autonomy could deliver.
Other drivers and restraints analyzed in the detailed report include:
- Carbon-Credit Schemes Rewarding Variable-Rate Input Cuts
- Satellite IoT Constellations for Sub-Inch Telemetry
- Rural Cybersecurity Threats Targeting Farm OT Networks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Guidance Systems held the leading 37.45% precision farming market share in 2025, sustained by robust GNSS receivers that steer machinery to sub-inch paths under variable terrain. The precision farming market size for Variable-Rate Technology is forecast to grow at a 13.55% CAGR through 2031, driven by rising fertilizer and chemical prices that incentivize targeted application. Drone-based remote sensing leverages cheaper multispectral payloads, with DJI reporting a 67.78% cut in chemical volumes when maps feed prescription sprayers. Robots are gaining traction as venture funding pivots to edge-AI platforms; Four Growers and Bonsai Robotics collectively raised USD 24 million to automate harvesting on 500,000 acres. Satellite IoT rounds out the stack, relaying sensor inputs from fields outside cellular reach so models stay current for autonomy modules.
Edge and cloud analytics work in tandem: edge hardware processes vision streams in real time, while cloud engines crunch seasonal patterns. John Deere's second-generation autonomy stack merges both layers to target full corn and soybean autonomy by decade's end. Farmers increasingly prefer mixed-fleet retrofits over single-brand replacements, a shift AGCO capitalized on with its OutRun kit that omits a high-cost tractor swap. Given these dynamics, technology suppliers who pair open APIs with hardware-agnostic components are best positioned to capture incremental acreage.
Hardware captured 51.20% of the precision farming market in 2025, covering sensors, controllers, drones, and autonomous platforms. Yet, software revenue is climbing at a 13.40% CAGR as edge-AI delivers actionable prescriptions within seconds, even when the network drops. Sensors have shrunk to postage-stamp footprints, letting small farms afford dense soil-moisture grids that feed variable-rate irrigation maps. Displays like John Deere's G5-Plus add Ethernet to pass richer datasets from implements back to the cab. On-board computers integrate GNSS, machine vision, and telemetry onto a single board, slashing latency for autonomy loops.
The precision farming market size for managed services is set to widen as operators lean on third-party partners to patch software and monitor cyber threats in real time. Data analytics suites from CNH and Raven trim herbicide by 77% with AI-directed selective spraying. Satellite backhaul ensures prescriptions sync during fieldwork, a crucial fail-safe for 77% of cropland without 4G. As hardware margins compress, vendors seek recurring revenue through subscriptions that bundle updates, algorithms, and carbon-credit reporting dashboards.
Complete Report Scope:
- By Technology
- Guidance Systems
- GNSS / GPS
- GIS
- Variable-Rate Technology
- Variable-Rate Fertilizer
- Variable-Rate Seeding
- Variable-Rate Pesticide
- Remote Sensing
- Drones and UAVs
- Robotics and Autonomous Equipment
- Edge and Cloud Analytics Platforms
- Other Technologies
- Guidance Systems
- By Component
- Hardware
- Sensors and Actuators
- Controllers and Displays
- On-board Computing and Connectivity
- Software
- Farm-Management SaaS
- Data Analytics and AI
- Services
- Integration and Consulting
- Managed Services
- Hardware
- By Application
- Yield Monitoring
- Variable-Rate Application
- Field Mapping
- Soil and Crop Health Monitoring
- Irrigation Management
- Crop Scouting
- Harvest Automation and Logistics
- Other Applications
- By Farm Size
- Small Farms (less than 100 ha)
- Medium Farms (100 - 1,000 ha)
- Large Farms (greater than 1,000 ha)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 41.15% regional share in 2025, aided by mature GNSS networks, an established dealer ecosystem, and a regulatory environment that recognizes digital records for carbon programs. The market has plateaued in growth rate relative to emerging regions, partly because 2025 farmer sentiment surveys show cautious capital plans amid volatile commodity prices. Nevertheless, active replacement cycles for legacy displays and expansion into full-machine autonomy should preserve the continent's demand floor.
The Asia-Pacific region recorded the fastest growth rate of 13.95% in the precision farming market, propelled by India's smart-ag market, projected to reach USD 886.21 million by 2028, and China's policy mandates around digital agriculture. Government-funded satellite constellations, low-cost drones, and rural broadband investments underpin adoption across smallholder plots. Venture capital flows of more than USD 1.2 billion in 2024 concentrated on automated orchard sprayers and agri-fintech credit scoring that ties input loans to sensor-verified field data. Australia adds incremental acreage with autonomous broad-acre fleets that alleviate chronic labor shortages.
Europe advances steadily under environmental legislation requiring a 50% cut in chemicals by 2030, positioning precision spraying as a compliance lever. Field trials in Germany confirm 10-20% pesticide reductions without yield sacrifice, bolstering farmer confidence. Latin America's adoption pace diverges: Brazil and Argentina slowed tractor purchases by 14% in 2024 due to drought-linked income declines, yet accelerated drone spraying after regulatory relaxation. The Middle East and Africa remain early in the curve; satellite IoT is a lifeline for Sub-Saharan growers where RTK networks stall at 40% coverage, but affordability and skills gaps temper speed.
- Deere and Company
- Trimble Inc.
- AGCO Corporation
- CNH Industrial N.V.
- Raven Industries
- Topcon Positioning Systems
- Lindsay Corporation
- TeeJet Technologies
- DICKEY-john
- BASF Digital Farming (xarvio)
- Yara International ASA
- Climate Corp (Bayer)
- Hexagon Agriculture
- CropX Technologies
- DJI Agriculture
- Farmers Edge
- Granular
- Ag Leader Technology
- Kubota Smart Agri
- Sentera
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in GNSS-enabled auto-steering adoption on large farms
- 4.2.2 Rapid cost declines in multispectral/thermal drone sensors
- 4.2.3 Government carbon-credit schemes rewarding variable-rate input cuts
- 4.2.4 Integration of satellite IoT constellations for sub-inch field telemetry
- 4.2.5 Insurance discounts for farms deploying AI-based risk scoring
- 4.2.6 Venture funding shift from farm-management SaaS to edge-AI robotics
- 4.3 Market Restraints
- 4.3.1 Data-interoperability gaps among mixed-brand machinery
- 4.3.2 Rural cybersecurity threats targeting farm OT networks
- 4.3.3 Plateauing RTK-network coverage in Sub-Saharan Africa
- 4.3.4 Farmer resistance to algorithmic decision loss of autonomy
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Guidance Systems
- 5.1.1.1 GNSS / GPS
- 5.1.1.2 GIS
- 5.1.2 Variable-Rate Technology
- 5.1.2.1 Variable-Rate Fertilizer
- 5.1.2.2 Variable-Rate Seeding
- 5.1.2.3 Variable-Rate Pesticide
- 5.1.3 Remote Sensing
- 5.1.4 Drones and UAVs
- 5.1.5 Robotics and Autonomous Equipment
- 5.1.6 Edge and Cloud Analytics Platforms
- 5.1.7 Other Technologies
- 5.1.1 Guidance Systems
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.1.1 Sensors and Actuators
- 5.2.1.2 Controllers and Displays
- 5.2.1.3 On-board Computing and Connectivity
- 5.2.2 Software
- 5.2.2.1 Farm-Management SaaS
- 5.2.2.2 Data Analytics and AI
- 5.2.3 Services
- 5.2.3.1 Integration and Consulting
- 5.2.3.2 Managed Services
- 5.2.1 Hardware
- 5.3 By Application
- 5.3.1 Yield Monitoring
- 5.3.2 Variable-Rate Application
- 5.3.3 Field Mapping
- 5.3.4 Soil and Crop Health Monitoring
- 5.3.5 Irrigation Management
- 5.3.6 Crop Scouting
- 5.3.7 Harvest Automation and Logistics
- 5.3.8 Other Applications
- 5.4 By Farm Size
- 5.4.1 Small Farms (less than 100 ha)
- 5.4.2 Medium Farms (100 - 1,000 ha)
- 5.4.3 Large Farms (greater than 1,000 ha)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Netherlands
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Deere and Company
- 6.4.2 Trimble Inc.
- 6.4.3 AGCO Corporation
- 6.4.4 CNH Industrial N.V.
- 6.4.5 Raven Industries
- 6.4.6 Topcon Positioning Systems
- 6.4.7 Lindsay Corporation
- 6.4.8 TeeJet Technologies
- 6.4.9 DICKEY-john
- 6.4.10 BASF Digital Farming (xarvio)
- 6.4.11 Yara International ASA
- 6.4.12 Climate Corp (Bayer)
- 6.4.13 Hexagon Agriculture
- 6.4.14 CropX Technologies
- 6.4.15 DJI Agriculture
- 6.4.16 Farmers Edge
- 6.4.17 Granular
- 6.4.18 Ag Leader Technology
- 6.4.19 Kubota Smart Agri
- 6.4.20 Sentera
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 歐洲精密農業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 精密農業市場:2026-2032年全球市場預測(按產品形式、產品類型、技術、農場規模、應用和最終用戶分類)
 全球精密農業市場規模、佔有率、趨勢和成長分析報告(2026-2034)精密農業設備市場:按設備類型、技術、產品、應用和最終用戶分類-2026-2032年全球市場預測
 即時農業監測感測器市場預測至 2034 年:按感測器類型、連接方式、農場類型、動力來源、應用、最終用戶和地區進行全球分析。
 衛星和地理空間技術在農業生產力中的作用:分析與預測(2025-2035 年)
 精密農業市場規模、佔有率和成長分析:按產品、技術、應用、最終用途和地區分類-2026-2033年產業預測人工智慧精密農業市場預測至2034年:按組件、技術、應用、最終用戶和區域分類的全球分析
 精密農業市場:依產品、應用和區域分類
 2026年全球人工智慧精密農業市場報告