


 |
市場調查報告書
商品編碼
2120470
無菌包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Aseptic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,無菌包裝市場規模將從 2025 年的 782.9 億美元成長到 2026 年的 863.6 億美元,到 2031 年將達到 1,410.6 億美元,2026 年至 2031 年的複合年成長率為 10.31%。
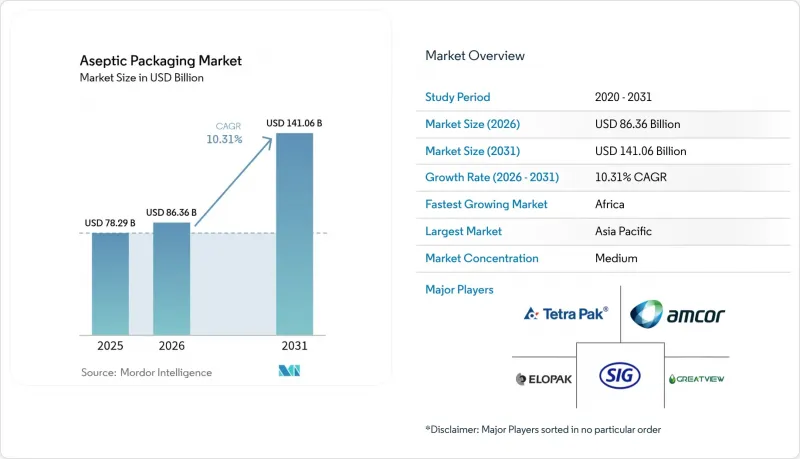
本報告按產品類型(紙盒、瓶子、罐子、袋子/包裝袋及其他)、材料成分(紙/紙板、塑膠、玻璃、金屬、複合層壓材料)、應用領域(飲料、食品、藥品及其他)、灌裝技術(泡沫灌裝封口 (FFS)、吹塑灌裝封裝 (BFS)、無菌灌裝技術(泡棉填充)及其他)和地區灌裝包裝區域(注射灌裝)及其他地區(注射灌裝)及其他地區。市場預測以美元 (USD) 為單位。
全球無菌包裝市場趨勢與洞察
即飲功能飲料的快速成長
即飲奶昔、益生菌飲料和強化植物奶正擴大採用常溫保存的紙盒和軟包裝,無需冷藏即可實現全國範圍的配送。在北美,蛋白質飲料製造商等品牌透過從冷鏈轉向無菌包裝,降低了約四分之一的物流成本。這種轉變也體現在資本投資上,預計到2025年,功能性飲料製造商將佔新增紙盒灌裝機安裝量的40%。小規模的新參與企業則依賴契約製造製造商以1萬至2.5萬件為單位生產無菌軟包裝,從而加快口味測試並降低庫存風險。消費者願意為與免疫力、腸道健康和身體抵抗力相關的功效產品支付更高的價格,這推高了無菌解決方案所需材料的成本。
擴大常溫乳製品在亞洲新興市場的分銷
超高溫滅菌(UHT)牛奶和優格如今已惠及缺乏可靠冷藏設施的農村地區消費者。印度合作社計劃在2024年至2025年間將紙盒包裝產能擴大約五分之一,以瞄準二、三線城市市場。與進口奶粉相比,常溫保存產品能夠防止雨季變質,穩定市場需求,並維持價格優勢,同時價格略高於鮮奶。印尼和越南政府對無菌灌裝設施的稅收優惠政策提高了投資吸引力,促使跨國加工企業在常溫保存產品系列實現了兩位數的成長。
多層聚合物價格波動
聚乙烯和聚丙烯價格的劇烈波動擠壓了加工商的利潤空間,迫使他們每季與品牌所有者調整價格。非洲和拉丁美洲的小規模加工商由於缺乏對沖手段,被迫承擔全部成本衝擊,導致在與進口成品包裝袋的競爭中處於劣勢。一些有遠見的供應商正在投資再生塑膠來源以確保原料供應,但由於再生聚乙烯目前的價格遠高於原生聚乙烯,這種短期緩解措施效果有限。
細分市場分析
預計到2031年,袋裝和軟包裝的複合年成長率將達到11.31%,在所有包裝形式中成長最高。這主要是由於直接面對消費者的飲料和品牌需要輕巧且適合數位印刷的包裝。紙盒在2025年佔銷售額的43.56%,但其成長速度正在放緩,因為零售商更重視紙盒相比軟包裝可節省20-30%的倉儲空間。瓶裝仍然是高階咖啡和益生菌飲料的主要包裝選擇,因為這些產品較高的包裝成本是合理的。而罐裝則滿足了能量飲料和雞尾酒的需求,充分利用了金屬的阻隔性和可回收性。
成本和品牌因素正在推動軟包裝的成長。與同等容量的紙盒相比,柔軟性可將運輸重量減輕近一半,從而降低運輸排放。零售商已開始使用永續發展評分卡來評估這一優勢。數位印刷技術的進步使得即使是5萬件或更少的批量也能實現全彩印刷,從而消除了以往小批量紙盒生產中難以逾越的製版成本。雖然在咖啡館和健身房等注重可重複密封性和品質的管道中,罐裝和瓶裝產品仍然佔據主導地位,但帶吸嘴的可重複密封軟包裝正在縮小與罐裝和瓶裝產品在功能上的差距,這表明無菌包裝市場的佔有率正在持續向軟包裝轉移。
到2025年,紙和紙板將佔銷售額的47.13%,反映出紙盒在乳製品和果汁領域的主導地位,而複合層壓材料的年複合成長率預計將達到11.39%。這是因為加工商正在將聚乙烯和乙烯-乙烯醇層進行層壓,以達到類似鋁箔的阻隔性能,同時滿足回收法規的要求。塑膠廣泛用於包裝袋和瓶子,玻璃在超高階冷萃咖啡領域仍佔有一席之地,而金屬則主要用於能量飲料。
複合材料結構的創新正在減少對鋁箔的依賴。安姆科的聚乙烯和二氧化矽複合材料的氧氣透過率低於0.5立方厘米,同時重量減輕了20%。歐盟2030年的回收目標正促使加工商轉向單一材料解決方案,尤其是聚乙烯。這些變化表明,複合材料結構將繼續在整個無菌包裝市場取代鋁箔紙盒,尤其是在積極實施擴大生產者責任制的地區。
區域分析
到2025年,亞太地區將佔全球銷售額的35.67%,這主要得益於印度乳製品需求的成長以及中國即飲茶市場的成長。在印度,超高溫滅菌(UHT)牛奶實現了兩位數的成長,因為即使在缺乏可靠冷藏設施的第二線城市,常溫保存包裝也得到了廣泛應用。在日本和韓國,高階單份優格的需求正在上升,而東南亞的新創公司則正在採用袋裝包裝來打入當地的分銷管道。
預計2026年至2031年間,非洲將維持11.34%的強勁複合年成長率。在奈及利亞、肯亞和南非,柴油和電力成本的上漲使得冷鏈營運面臨經濟困境。因此,這些國家的乳製品合作社和果汁加工商開始轉向生產常溫保存型產品。儘管本地紙板和包裝袋的生產仍處於起步階段,且進口成本不斷增加,但跨國公司正積極尋求與本地加工商建立合作關係,以加強其本地供應鏈。
儘管歐洲和北美的成長速度較慢,但它們正在推動永續性法規的製定。歐盟的《包裝和包裝廢棄物法規》正在加速單一材料複合材料的普及。北美市場的成長主要集中在功能性飲料和無菌生技藥品的填充領域,而拉丁美洲則在外匯波動和對常溫乳製品強勁需求之間尋求平衡。在中東,沙烏地阿拉伯和阿拉伯聯合大公國預計將帶來商機,因為這些地區的高溫氣候是無菌包裝市場的天然優勢。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 產業價值鏈分析
- 市場促進因素
- 即飲功能飲料的快速成長
- 擴大常溫乳製品在亞洲新興市場的分銷
- 嚴格的食品安全法規促進了無菌包裝的採用。
- 通貨膨脹導致物流從冷鏈轉向常溫。
- 強制過渡到永續和輕量化包裝
- D2C品牌中採用數位印刷技術的小批量SKU的興起
- 市場限制因素
- 多層聚合物價格波動
- 無菌灌裝生產線的初始設備投資成本高
- 鋁箔層壓板缺乏回收基礎設施
- PFAS阻隔塗層監管方面的不確定性
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
- 價格分析
第5章 市場規模與成長預測
- 依產品
- 紙盒
- 瓶子
- 能
- 袋子和小袋
- 管瓶安瓿
- 按材料組成
- 紙張和紙板
- 塑膠(PP、PE、PET)
- 玻璃
- 金屬(鋁、鐵)
- 複合層壓材料
- 透過使用
- 飲料
- 即飲飲料
- 乳製品飲料
- 食物
- 加工食品
- 水果和蔬菜
- 乳製品
- 製藥
- 個人護理和化妝品
- 飲料
- 灌裝技術
- 泡棉填充密封(FFS)
- 吹灌封(BFS)
- 無菌灌裝(注射灌裝)
- 旋轉式無菌灌裝
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲地區
- 中東
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Tetra Pak International SA
- SIG Combibloc Group
- Amcor PLC
- Elopak ASA
- IPI SRL(Coesia Group)
- DS Smith PLC
- Smurfit Kappa Group
- Mondi PLC
- Uflex Limited
- Schott AG
- Gerresheimer AG
- Toyo Seikan Group
- CDF Corporation
- BIBP Sp. z oo
- Nampak Ltd
- Greatview Aseptic Packaging
- OPLATEK Group
- Sealed Air Corporation
- ProAmpac Holdings Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the aseptic packaging market size is expected to grow from USD 78.29 billion in 2025 to USD 86.36 billion in 2026 and is forecast to reach USD 141.06 billion by 2031 at a 10.31% CAGR over 2026-2031.
This report is Segmented by Product (Cartons, Bottles, Cans, Bags and Pouches, and More), Material Composition (Paper and Paperboard, Plastics, Glass, Metal, Composite Laminates), Application (Beverage, Food, Pharmaceuticals, and More), Filling Technology (Form-Fill-Seal (FFS), Blow-Fill-Seal (BFS), Injection Aseptic Filling, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Aseptic Packaging Market Trends and Insights
Rapid Growth of RTD Functional Beverages
Ready-to-drink shakes, probiotic drinks, and fortified plant-based milks are switching to ambient cartons and pouches, enabling national distribution without refrigeration. Brand examples such as protein beverages in North America cut logistics bills by roughly one-quarter when they moved from cold-chain to aseptic packaging. Capital spending reflects the shift, with functional beverage producers accounting for 40% of new carton-filler installations in 2025. Smaller entrants lean on co-packers that run aseptic pouches in lots of 10,000-25,000 units, accelerating flavor tests and limiting inventory exposure. Consumer willingness to pay premiums for claims linked to immunity, gut health, and recovery underpins the higher material cost of aseptic solutions.
Expansion of Ambient Dairy Distribution in Emerging Asia
Ultra-high-temperature milk and yogurt now reach rural consumers who lack reliable refrigeration. Indian cooperatives increased carton capacity by roughly one-fifth during 2024-2025 to penetrate tier-2 and tier-3 cities. Ambient formats reduce monsoon-season spoilage, stabilize demand, and earn modest price premiums over fresh milk while remaining affordable relative to imported powders. Government tax incentives for aseptic equipment in Indonesia and Vietnam sharpened the investment case, and multinational processors recorded double-digit growth from ambient dairy portfolios.
Volatility in Multilayer Polymer Prices
Swinging polyethylene and polypropylene prices shaved converter margins and forced quarterly price realignments with brand owners. Small converters in Africa and Latin America, lacking hedging options, absorbed the full cost shock, undermining competitiveness against imported pre-made pouches. Forward-looking suppliers are investing in recycled-resin streams to secure feedstock, yet recycled polyethylene currently trades at a noticeable premium over virgin grades, limiting near-term relief.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Food-Safety Regulations Pushing Sterile Packaging Adoption
- Inflation-Linked Shift from Cold-Chain to Shelf-Stable Logistics
- High Initial CAPEX for Aseptic Filling Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bags and pouches are projected to deliver an 11.31% CAGR through 2031, the swiftest among formats, as direct-to-consumer beverage and sauce brands need lightweight packs that suit digital graphics. Cartons retained 43.56% of revenue in 2025, yet their growth rate moderates as retailers reward pouches with 20-30% warehouse cube savings. Bottles continue to serve premium coffees and probiotic drinks that justify higher pack costs, while cans cater to energy cocktails, leveraging metal's barrier and recyclability.
Cost and branding factors underpin the pouch trajectory. Each flexible pack reduces shipping weight by close to half versus a similar-volume carton, translating to lower freight emissions, an advantage spotlighted by retailers with sustainability scorecards. Digital press advances now permit full-color artwork for runs of fewer than 50,000 pieces, avoiding plate fees that historically handicapped small-batch cartons. Cans and bottles still dominate cafe or gym channels where resealability and perceived quality matter, yet resealable spouted pouches are narrowing that functional gap, indicating continued share migration toward flexibles in the aseptic packaging market.
Paper and paperboard accounted for 47.13% of revenue in 2025, reflecting carton dominance in dairy and juice, yet composite laminates are on track for an 11.39% CAGR as converters stack polyethylene and ethylene-vinyl-alcohol layers to achieve foil-barrier performance while meeting recyclability rules. Plastics have broad utility across pouches and bottles, while glass remains niche in ultra-premium cold brews, and metal focuses on energy drinks.
Innovation in laminate structures is reducing reliance on aluminum foil. Amcor's polyethylene plus silicon oxide laminate achieves sub-0.5 cc oxygen transmission with 20% less weight. The European Union's 2030 recyclability targets are steering converters toward mono-material solutions, particularly polyethylene. These shifts suggest composite structures will continue to displace foil-lined cartons across the aseptic packaging market, especially in regions with active extended producer responsibility schemes.
Complete Report Scope:
- By Product
- Cartons
- Bottles
- Cans
- Bags and Pouches
- Vials and Ampoules
- By Material Composition
- Paper and Paperboard
- Plastics (PP, PE, PET)
- Glass
- Metal (Aluminum, Steel)
- Composite Laminates
- By Application
- Beverage
- Ready-to-Drink (RTD) Beverages
- Dairy-Based Beverages
- Food
- Processed Food
- Fruits and Vegetables
- Dairy Food
- Pharmaceuticals
- Personal Care and Cosmetics
- Beverage
- By Filling Technology
- Form-Fill-Seal (FFS)
- Blow-Fill-Seal (BFS)
- Injection Aseptic Filling
- Rotary Aseptic Filling
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia Pacific accounted for 35.67% of global revenue in 2025, led by expanding dairy demand in India and the growth of ready-to-drink tea in China. Ultra-high-temperature milk in India grew at double-digit rates as ambient packs reached tier-2 cities without reliable refrigeration. Japan and South Korea show premium uptakes in single-serve yogurts, while Southeast Asian startups adopt pouches to penetrate rural channels.
From 2026 to 2031, Africa is projected to witness a robust CAGR of 11.34%. In Nigeria, Kenya, and South Africa, soaring diesel and grid-power expenses are rendering cold chain operations economically unfeasible. As a result, dairy cooperatives and juice processors in these nations are shifting their focus towards shelf-stable product formats. While local production of cartons and pouches is still in its infancy, leading to heightened landed-cost pressures, multinational corporations are proactively forging partnerships with regional converters, aiming to bolster local supply chains.
Europe and North America grow more slowly yet drive sustainability mandates. The EU's Packaging and Packaging Waste Regulation is accelerating the adoption of mono-material laminates. North America's growth clusters around functional drinks and sterile biologic fills, while Latin America balances currency volatility against strong demand for ambient dairy. The Middle East offers opportunities in Saudi Arabia and the United Arab Emirates, where high ambient temperatures naturally favor the aseptic packaging market.
- Tetra Pak International SA
- SIG Combibloc Group
- Amcor PLC
- Elopak ASA
- IPI SRL (Coesia Group)
- DS Smith PLC
- Smurfit Kappa Group
- Mondi PLC
- Uflex Limited
- Schott AG
- Gerresheimer AG
- Toyo Seikan Group
- CDF Corporation
- BIBP Sp. z o.o.
- Nampak Ltd
- Greatview Aseptic Packaging
- OPLATEK Group
- Sealed Air Corporation
- ProAmpac Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value Chain Analysis
- 4.3 Market Drivers
- 4.3.1 Rapid Growth of RTD Functional Beverages
- 4.3.2 Expansion of Ambient Dairy Distribution in Emerging Asia
- 4.3.3 Stringent Food-Safety Regulations Pushing Sterile Packaging Adoption
- 4.3.4 Inflation-Linked Shift from Cold-Chain to Shelf-Stable Logistics
- 4.3.5 Shift Toward Sustainable, Lightweight Packaging Mandates
- 4.3.6 Rise of Digital-Print-Enabled Short SKUs for D2C Brands
- 4.4 Market Restraints
- 4.4.1 Volatility in Multilayer Polymer Prices
- 4.4.2 High Initial CAPEX for Aseptic Filling Lines
- 4.4.3 Limited Recycling Infrastructure for Aluminum-Foil Laminates
- 4.4.4 Regulatory Uncertainty Around PFAS Barrier Coatings
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Pricing Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Cartons
- 5.1.2 Bottles
- 5.1.3 Cans
- 5.1.4 Bags and Pouches
- 5.1.5 Vials and Ampoules
- 5.2 By Material Composition
- 5.2.1 Paper and Paperboard
- 5.2.2 Plastics (PP, PE, PET)
- 5.2.3 Glass
- 5.2.4 Metal (Aluminum, Steel)
- 5.2.5 Composite Laminates
- 5.3 By Application
- 5.3.1 Beverage
- 5.3.1.1 Ready-to-Drink (RTD) Beverages
- 5.3.1.2 Dairy-Based Beverages
- 5.3.2 Food
- 5.3.2.1 Processed Food
- 5.3.2.2 Fruits and Vegetables
- 5.3.2.3 Dairy Food
- 5.3.3 Pharmaceuticals
- 5.3.4 Personal Care and Cosmetics
- 5.3.1 Beverage
- 5.4 By Filling Technology
- 5.4.1 Form-Fill-Seal (FFS)
- 5.4.2 Blow-Fill-Seal (BFS)
- 5.4.3 Injection Aseptic Filling
- 5.4.4 Rotary Aseptic Filling
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Tetra Pak International SA
- 6.4.2 SIG Combibloc Group
- 6.4.3 Amcor PLC
- 6.4.4 Elopak ASA
- 6.4.5 IPI SRL (Coesia Group)
- 6.4.6 DS Smith PLC
- 6.4.7 Smurfit Kappa Group
- 6.4.8 Mondi PLC
- 6.4.9 Uflex Limited
- 6.4.10 Schott AG
- 6.4.11 Gerresheimer AG
- 6.4.12 Toyo Seikan Group
- 6.4.13 CDF Corporation
- 6.4.14 BIBP Sp. z o.o.
- 6.4.15 Nampak Ltd
- 6.4.16 Greatview Aseptic Packaging
- 6.4.17 OPLATEK Group
- 6.4.18 Sealed Air Corporation
- 6.4.19 ProAmpac Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026-2030年全球無菌包裝市場
 北美無菌包裝:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 無菌包裝市場:2026-2032年全球市場預測(依產品類型、材料、滅菌方法、填充技術、應用、最終用戶及通路分類)
 2026 年至 2035 年無菌加工包裝材料的市場機會、成長促進因素、產業趨勢分析與預測。
 2034年乳製品無菌包裝市場預測-按包裝形式、材料、技術、產品類型、最終用戶和地區分類的全球分析
 無菌包裝市場報告:按類型、材料、應用和地區分類(2026-2034 年)
 全球無菌包裝市場分析:市場規模、佔有率、應用及預測(2018-2034)
 無菌包裝市場:依材料、類型、應用、地區分類全球無菌包裝市場:市場規模、趨勢與預測(2034 年)
 無菌包裝食品市場規模、佔有率和成長分析:按材料類型、包裝類型、應用、最終用途和地區分類-2026-2033年產業預測