


 |
市場調查報告書
商品編碼
2119397
體育行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Sports Marketing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
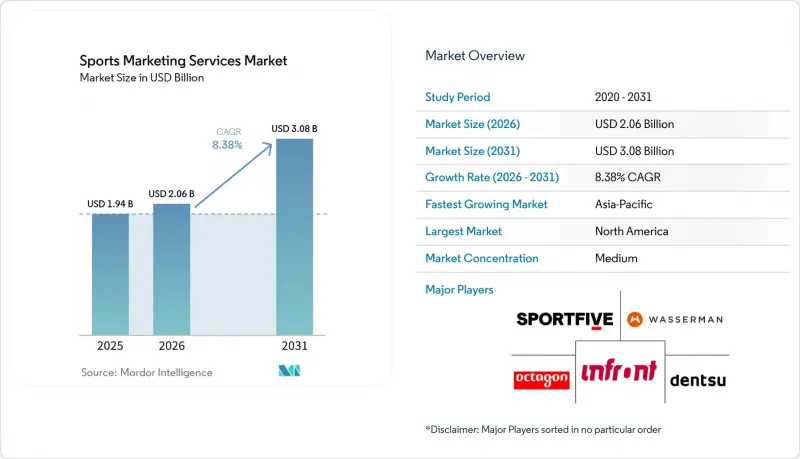
據 Mordor Intelligence 稱,2025 年體育行銷服務市場價值 19.4 億美元,預計到 2031 年將達到 30.8 億美元,而 2026 年為 20.6 億美元,2026 年至 2031 年預測期內的複合年預計成長率為 8.38%。
本報告按服務類型(策略諮詢和商業情報服務、商業版權銷售和夥伴關係管理服務、品牌體驗、受眾開發和互動服務等)、運動類型(足球、電子競技、板球、棒球/壘球、網球、高爾夫等)和地區進行細分。市場預測以價值(美元)表示。
全球體育行銷服務市場的趨勢與洞察
對可衡量的贊助投資報酬率的需求日益成長
贊助支出與可靠的績效衡量之間的差距仍然是體育行銷服務市場面臨的核心挑戰。一項針對全球品牌所有者的2025年調查顯示,衡量投資回報率是贊助管理最大的挑戰,超過了活動整合和預算管理。目前的衡量方法往往分散在各個團隊之間,無法整體情況商業性回報。能夠將衡量系統與創新和活動運營相結合的代理機構,可以在獲取以往依賴人脈關係的交易方面獲得競爭優勢。 2026年2月,SponsorUnited發布了其「4.0」平台,該平台包含超過40.3萬個品牌和220萬筆交易的數據,凸顯了人們對基準分析將成為標準服務的日益成長的期望。同行評審的研究表明,與傳統方法相比,採用強化學習框架可以將贊助投資回報率提高25%至35%,品牌曝光度提高20%至30%。
串流媒體和社群優先運動消費的擴張
隨著觀眾從傳統電視轉播轉向串流媒體和社交管道,全球體育行銷服務市場正商業性的規模擴張。如今,球迷可以透過多種形式與內容互動,包括直播比賽、精彩片段、創作者、球隊頻道和運動員帳號。這一趨勢催生了不同的互動群體,每個群體都需要不同的創新素材、分發計畫和效果評估方法。這也使得內容合約建構和創作者夥伴關係管理成為一項核心服務,而不再只是可選項目。擁有體育賽事轉播權的平台越來越重視其平台專屬的發行、球迷互動和宣傳活動協調能力。代理商則透過將體育相關的推廣活動與創作者計畫和數位零售活動相結合來應對這一變化,從而產生了更廣泛的服務需求和更複雜的歸因分析。
跨平台衡量和歸因的碎片化
串流媒體平台、社群管道和內容創作者網路正在將體育觀眾群體分割成多個互動群體,而許多衡量系統無法整合這些數據。這限制了廣告主比較不同宣傳活動曝光量和效果的能力。 2026年1月,ESPN採用了comscore的跨平台衡量系統,以整合來自傳統電視、串流媒體、數位媒體和社群媒體的觀眾數據。雖然此舉代表著進步,但它並未在版權所有擁有者、平台和國家之間建立通用的標準。體育行銷服務公司被迫投資開發自己的衡量工具,這給沒有專門分析部門的中型機構帶來了更大的負擔。此外,在歐洲,隱私法規限制了用戶層級的追蹤,使得跨平台歸因分析更加困難。
細分市場分析
2025年,「品牌體驗」佔服務類支出的31.60%,反映出對現場活動、體驗式快閃店和贊助粉絲活動的持續投入。這在體育行銷服務市場中佔據了服務類別中的最大佔有率。隨著世界盃的舉辦,主辦城市的節慶活動、互動場館計畫和內容創作者整合活動的預算撥款也在增加。這些項目旨在創造體育場館廣告以外的附加價值。隨著客戶適應「姓名、形象和肖像權(NIL)」的商業化、串流版權策略以及不斷發展的大學體育項目,「策略諮詢和商業情報服務」的重要性仍然很高。 Learfield報告稱,2025-2026會計年度與NIL相關的贊助收入將超過3億美元,高於2024-2025會計年度的1.4億美元,涵蓋超過1300個品牌和5000名學生運動員。隨著職業運動和大學體育賽事合約活動的擴展,商業版權銷售和夥伴關係管理服務也從中受益。隨著球隊和聯賽不斷提升利用第一方數據的能力,受眾拓展和互動服務的重要性日益凸顯。
「內容、媒體和創作者服務」產業預計將在2026年至2031年間以8.90%的複合年成長率成長。該服務業中體育行銷服務的市場規模成長主要得益於創作者網路作為體育分發基礎設施的正式應用。運動員創作者正日益被視為媒體合作夥伴,而不僅僅是偶爾的網紅。這種轉變正在拓展代理商的工作範圍,使其從創新製作擴展到合作夥伴選擇、版權管理、分發和效果報告。美國職業足球大聯盟(MLS)於2026年3月宣布與DataGrail達成多年合作協議,旨在其中央營運部門和30傢俱樂部中實施一個全聯盟範圍的資料隱私和管治平台。這項合作表明,受眾拓展已涵蓋同意管理和資料管治。同時具備內容運作和法律/技術能力的代理商更有能力滿足這些要求。隱私合規正成為個人化和受眾拓展服務合約中不可或缺的一部分。
區域分析
到2025年,北美將佔據全球體育行銷服務市場42.80%的佔有率。該地區憑藉著高昂的媒體版權價值、成熟的贊助模式、穩定的現場觀眾人數以及品牌預算對體育行銷服務市場的支持,正推動著市場成長。姓名、形象和肖像權(NIL)經濟正為受眾拓展、內容創作和夥伴關係服務注入新的商業性活力。同時,2026年世界盃也帶動了主辦城市推廣活動、球迷節、創作者宣傳活動以及零售合作的需求。 Opendorse預測,2026-2027學年美國NIL市場規模將達到45億美元。北美仍然是提供整合版權、推廣活動、數據、效果評估和績效報告等服務的供應商的重要區域中心。
歐洲是體育行銷服務市場的第二大區域中心。預計到2025年,歐洲運動贊助市場規模將達到247.9億歐元(285億美元)。德國預計仍將是歐洲最大的運動贊助市場,規模達62.6億歐元(71.9億美元)。同時,西班牙預計將達到21.8億歐元(25億美元),成長14%。英國預計將達到61.5億歐元(70.7億美元),法國為18.5億歐元(21.3億美元),義大利為20.1億歐元(23.1億美元)。儘管成熟的媒體版權和廣告市場支撐著對專業服務的穩定需求,但隱私管治、以人才主導的夥伴關係以及受眾數據監管正在影響宣傳活動的設計。
預計亞太地區在2026年至2031年間將以8.72%的複合年成長率成長,成為所有地區中成長最快的地區。這將擴大服務印度、中國和韓國的體育行銷服務市場規模。印度的板球生態系統和數位發行管道的擴張,催生了對系統性贊助、內容和版權服務的需求;而中國的串流媒體環境則需要在地化的數位夥伴關係模式。電通在國際棒球和壘球賽事的媒體和行銷版權商業化方面繼續發揮關鍵作用,其與世界棒壘球聯合會(WBSC)的合作協議便是最好的證明。非洲仍處於發展初期,但南非成熟的贊助活動、奈及利亞足球媒體的蓬勃發展以及埃及舉辦賽事的積極性,都催生了對專業支持的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對可衡量的贊助投資報酬率的需求日益成長
- 串流媒體和社群優先運動消費的擴張
- 女性運動用品的商業性擴張
- 品牌轉向體驗式粉絲互動
- 擴大NIL和大學運動員的商業基礎設施
- 實施人工智慧原生贊助計畫和最佳化工作流程
- 市場限制因素
- 跨平台衡量和歸因的碎片化
- 許可費和激活成本不斷上漲
- 粉絲導向個人化中的隱私與資料管治摩擦
- 串流媒體市場分散化與訂閱疲勞
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 策略諮詢和商業資訊服務
- 商業版權銷售和夥伴關係管理服務
- 品牌體驗
- 受眾拓展與互動服務
- 內容、媒體和創作者的服務
- 體育運動
- 足球
- 籃球
- 蟋蟀
- 棒球/壘球
- 網球
- 高爾夫球
- 電競
- 奧運和綜合運動會
- 其他運動
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Octagon, Inc.
- Wasserman Media Group, LLC
- Dentsu Group Inc.
- Infront Sports & Media AG
- SPORTFIVE Global Holding GmbH
- Creative Artists Agency, LLC
- William Morris Endeavor Entertainment, LLC
- IMG Worldwide, LLC
- Learfield Communications, LLC
- Two Circles Ltd
- Publicis Groupe SA
- GMR Marketing LLC
- TEAM Marketing AG
- CSM Sport and Entertainment LLP
- Excel Sports Management, LLC
- Momentum Worldwide
- Abler Sports & Entertainment
- Right Formula Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the sports marketing services market size was USD 1.94 billion in 2025 and is estimated to grow from USD 2.06 billion in 2026 to reach USD 3.08 billion by 2031, at a CAGR of 8.38% during the forecast period 2026-2031.
This report is Segmented by Service Type (Strategic Advisory and Commercial Intelligence Services, Commercial Rights Sales and Partnership Management Services, Brand Experience, Audience Development and Engagement Services, and More), by Sport (Football/Soccer, Esports, Cricket, Baseball and Softball, Tennis, Golf, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sports Marketing Services Market Trends and Insights
Rising Demand for Measurable Sponsorship ROI
The gap between sponsorship spending and credible performance measurement remains a central issue for the sports marketing services market. A 2025 survey of global brand owners identified ROI measurement as the leading sponsorship management challenge, ahead of activation integration and budget governance. Measurement often remains fragmented across teams, limiting a complete view of commercial return. Agencies that integrate measurement systems with creative and activation work can compete for mandates that previously depended more on network relationships. SponsorUnited introduced its 4.0 platform in February 2026, featuring data on more than 403,000 brands and 2.2 million deals, underscoring that benchmarking is becoming a standard service expectation. A peer-reviewed study found that a reinforcement learning framework improved sponsorship ROI by 25-35% and brand exposure by 20-30% against conventional approaches.
Expansion of Streaming and Social-First Sports Consumption
The shift of audiences from linear television to streaming and social channels is expanding the commercial surface area of the global sports marketing services market. Fans now engage with live games, clips, creators, team channels, and athlete accounts across several formats. This pattern creates separate engagement pools that need different creative assets, distribution plans, and measurement methods. It also makes content deal structuring and creator partnership management central services rather than optional additions. Platforms that secure sports rights are increasing the value of platform-native distribution, fan engagement, and campaign coordination skills. Agencies are responding by connecting sports activations with creator programs and digital retail activity, producing a broader service need and a more difficult attribution environment.
Fragmented Cross-Platform Measurement and Attribution
Streaming platforms, social channels, and creator networks divide sports audiences into engagement pools that many measurement systems cannot reconcile. This limits buyers' ability to compare exposure and outcomes across a complete campaign. ESPN adopted Comscore's cross-platform measurement system in January 2026 to bring together linear television, streaming, digital, and social audience data. The development signals progress, but it does not create a common standard across rights holders, platforms, and countries. Sports marketing services firms must invest in their own measurement tools, which creates a heavier burden for mid-tier agencies without dedicated analytics divisions. In Europe, privacy rules also limit user-level tracking and make cross-platform attribution more difficult.
Other drivers and restraints analyzed in the detailed report include:
- Commercial Acceleration of Women's Sports Inventory
- Brand Shift Toward Experiential Fan Engagement
- Escalating Rights Fees and Activation Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brand Experience held 31.60% of service-type spending in 2025, reflecting continued investment in venue activations, experiential pop-ups, and sponsored fan events. It accounted for the largest share of the sports marketing services market among the service categories. The World Cup cycle is directing more budgets toward host-city festivals, interactive venue programs, and creator-integrated activity. These programs are designed to create value beyond a stadium placement. Strategic Advisory and Commercial Intelligence Services remains relevant as clients address name, image, and likeness commercialization, streaming rights strategy, and changes in college athletic programs. Learfield reported more than USD 300 million in NIL-linked sponsorship revenue for 2025-26, up from more than USD 140 million in 2024-25, across more than 1,300 brands and 5,000 student-athletes. Commercial Rights Sales and Partnership Management Services also benefit from expanding deal activity across professional and college properties. Audience Development and Engagement Services are gaining importance as teams and leagues develop first-party data capabilities.
Content, Media and Creator Services is projected to grow at a 8.90% CAGR from 2026 to 2031. The sports marketing services market size for this service line is supported by the formal adoption of creator networks as sports distribution infrastructure. Athlete creators are increasingly managed as media partners rather than as occasional influencers. This shift broadens agency work from creative production into partner selection, rights management, distribution, and performance reporting. Major League Soccer announced a multiyear collaboration with DataGrail in March 2026 to deploy a league-wide data privacy and governance platform across its central operations and 30 clubs. The arrangement shows that audience development now includes consent management and data governance. Agencies that combine content work with legal and technology capabilities are better placed to meet these requirements. Privacy compliance is becoming part of contracts for personalization and audience development services.
Complete Report Scope:
- By Service Type
- Strategic Advisory and Commercial Intelligence Services
- Commercial Rights Sales and Partnership Management Services
- Brand Experience
- Audience Development and Engagement Services
- Content, Media and Creator Services
- By Sport
- Football/Soccer
- Basketball
- Cricket
- Baseball and Softball
- Tennis
- Golf
- Esports
- Olympic and Multi-Sport Events
- Other Sports
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 42.80% of the global sports marketing services market in 2025. The region combines high media rights values, mature sponsorship practices, regular live attendance, and brand budgets that support the sports marketing services market. The name, image, and likeness economy is adding a commercial layer for audience development, content, and partnership services, while the World Cup 2026 is increasing demand for host-city activations, fan festivals, creator campaigns, and retail connections. Opendorse projected the U.S. NIL market would reach USD 4.5 billion in the 2026-27 academic year. North America remains the primary regional base for providers offering integrated rights, activation, data, measurement, and performance reporting.
Europe is the second-largest regional base in the sports marketing services market. European sports sponsorship is expected to reach EUR 24.79 billion (USD 28.5 billion) in 2025. Germany is expected to remain Europe's largest national sports sponsorship market at EUR 6.26 billion (USD 7.19 billion), while Spain is projected to rise by 14% to EUR 2.18 billion (USD 2.5 billion). The United Kingdom is expected to reach EUR 6.15 billion (USD 7.07 billion), France EUR 1.85 billion (USD 2.13 billion), and Italy EUR 2.01 billion (USD 2.31 billion). Mature media rights and advertising markets support stable demand for specialist services, while privacy governance, talent-led partnerships, and audience data rules shape campaign design.
Asia-Pacific is projected to grow at an 8.72% CAGR from 2026 to 2031, the fastest regional rate. This creates an expanding sports marketing services market size for agencies serving India, China, and South Korea. India's cricket ecosystem and growing digital distribution are building demand for structured sponsorship, content, and rights services, while China's streaming environment requires localized digital partnership models. Dentsu's agreement with the World Baseball Softball Confederation continued its role in commercializing media and marketing rights across international baseball and softball events. Africa remains an earlier-stage region, although established South African sponsorship activity, growing Nigerian football media, and Egypt's event-hosting ambitions are creating need for specialist support.
- Octagon, Inc.
- Wasserman Media Group, LLC
- Dentsu Group Inc.
- Infront Sports & Media AG
- SPORTFIVE Global Holding GmbH
- Creative Artists Agency, LLC
- William Morris Endeavor Entertainment, LLC
- IMG Worldwide, LLC
- Learfield Communications, LLC
- Two Circles Ltd
- Publicis Groupe S.A.
- GMR Marketing LLC
- TEAM Marketing AG
- CSM Sport and Entertainment LLP
- Excel Sports Management, LLC
- Momentum Worldwide
- Abler Sports & Entertainment
- Right Formula Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand For Measurable Sponsorship ROI
- 4.2.2 Expansion of Streaming and Social-First Sports Consumption
- 4.2.3 Commercial Acceleration of Women's Sports Inventory
- 4.2.4 Brand Shift Toward Experiential Fan Engagement
- 4.2.5 Scaling of NIL And College Athlete Commercialization Infrastructure
- 4.2.6 Adoption of AI-Native Sponsorship Planning And Optimization Workflows
- 4.3 Market Restraints
- 4.3.1 Fragmented Cross-Platform Measurement and Attribution
- 4.3.2 Escalating Rights Fees and Activation Costs
- 4.3.3 Privacy and Data Governance Friction In Fan Personalization
- 4.3.4 Streaming Fragmentation and Subscription Fatigue
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Strategic Advisory and Commercial Intelligence Services
- 5.1.2 Commercial Rights Sales and Partnership Management Services
- 5.1.3 Brand Experience
- 5.1.4 Audience Development and Engagement Services
- 5.1.5 Content, Media and Creator Services
- 5.2 By Sport
- 5.2.1 Football/Soccer
- 5.2.2 Basketball
- 5.2.3 Cricket
- 5.2.4 Baseball and Softball
- 5.2.5 Tennis
- 5.2.6 Golf
- 5.2.7 Esports
- 5.2.8 Olympic and Multi-Sport Events
- 5.2.9 Other Sports
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Chile
- 5.3.2.4 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 Japan
- 5.3.4.3 India
- 5.3.4.4 South Korea
- 5.3.4.5 Australia
- 5.3.4.6 Rest of Asia-Pacific
- 5.3.5 Middle East
- 5.3.5.1 United Arab Emirates
- 5.3.5.2 Saudi Arabia
- 5.3.5.3 Qatar
- 5.3.5.4 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Egypt
- 5.3.6.3 Nigeria
- 5.3.6.4 Rest of Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Octagon, Inc.
- 6.4.2 Wasserman Media Group, LLC
- 6.4.3 Dentsu Group Inc.
- 6.4.4 Infront Sports & Media AG
- 6.4.5 SPORTFIVE Global Holding GmbH
- 6.4.6 Creative Artists Agency, LLC
- 6.4.7 William Morris Endeavor Entertainment, LLC
- 6.4.8 IMG Worldwide, LLC
- 6.4.9 Learfield Communications, LLC
- 6.4.10 Two Circles Ltd
- 6.4.11 Publicis Groupe S.A.
- 6.4.12 GMR Marketing LLC
- 6.4.13 TEAM Marketing AG
- 6.4.14 CSM Sport and Entertainment LLP
- 6.4.15 Excel Sports Management, LLC
- 6.4.16 Momentum Worldwide
- 6.4.17 Abler Sports & Entertainment
- 6.4.18 Right Formula Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


