


 |
市場調查報告書
商品編碼
2119287
雲端原生網路功能遷移服務:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031 年)Cloud-Native Network Function Migration Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,雲端原生網路功能遷移服務的市場規模預計將在 2025 年達到 25.4 億美元,在 2026 年達到 32.4 億美元,在 2031 年達到 62.9 億美元,從 2026 年到 2031 年的複合成長率年為 14.19%。
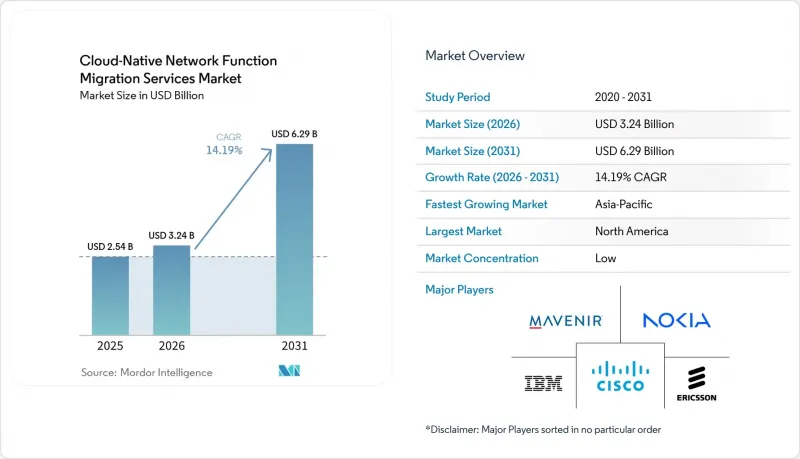
本報告按元件(解決方案和服務)、部署模式(雲端服務供應商和本地部署)、網路功能域(5G核心網路和演進分組核心網、IP多媒體子系統等)、最終用戶(電信服務供應商、雲端服務供應商、大型企業等)和地區進行細分。市場預測以價值(美元)表示。
全球雲端原生網路功能遷移服務市場趨勢與洞察
5G獨立組網核心網和網路切片的部署
雲端原生功能對於 5G 獨立組網核心至關重要,這直接催生了對遷移工作的需求。挪威電信 (Telia Norge) 宣布將於 2026 年推出全國性的商用 5G 獨立組網服務,其延遲低於 10 毫秒,而非獨立組網 5G 的延遲為 15-18 毫秒。 Proximus 將於 2026 年 4 月在比利時推出「5G+」服務,這將為另一個需要雲端原生核心功能的商用部署增添新的選擇。網路切片依賴獨立群組網路架構,因為它需要在使用者和服務之間動態分配網路資源。隨著營運商將這些功能遷移到商用領域,而不是繼續維護非獨立組網網路,雲端原生網路功能遷移服務市場將從中受益。 ETSI 標準為在此遷移過程中檢驗基於服務的網路架構提供了一個通用的技術框架。
利用混合雲和多重雲端解決方案實現電信營運商的現代化
電信業者正日益充分利用公共雲端資源和自有資料中心基礎設施。 2026年3月,O2 Telefonica 在其自有資料中心內,基於運行在 AWS Outposts 上的諾基亞軟體部署了 5G 雲端核心網,並透過這種混合模式為一百萬客戶提供服務。這種模式將公共雲端維運工具與對雲端敏感網路工作負載的本地控制相結合,從而在雲端原生網路功能遷移服務市場中佔有一席之地。隨著電信業者需要在不同的地點和雲端環境中運作各項功能,平台可攜性也變得日益重要。雲端原生網路功能遷移服務市場受益於此複雜性,因為遷移合作夥伴必須設計、測試和維運雲端平台之間的連接。中國電信將雲端原生網路元素的演進和邊緣人工智慧的融合定位為其 2026 年至 2030 年「雲端網融合」階段的兩大支柱。
整合傳統OSS和BSS的複雜度。
傳統營運支援系統(OSS) 和收費支撐系統 (BSS) 仍然是雲端原生遷移的重大障礙。由於過去的收購和獨立的網路部署,現有電信業者通常經營多個 OSS 和 BSS 平台。這些系統可能包含專有介面和未公開的依賴項,難以與容器化網路功能整合。雲端原生網路功能遷移服務市場需要經驗豐富的整合團隊,因為網路配置、收費和服務保障必須在整個切換期間持續進行。如果傳統層缺乏實用的可編程介面,則可能仍然需要人工操作,從而削弱運營商期望從雲原生自動化中獲得的速度和成本優勢。
細分市場分析
至2025年,服務業將佔據雲端原生網路功能遷移服務市場69.12%的佔有率。這反映出電信業者對整合式諮詢、檢驗和託管式遷移支援的持續需求。遷移項目通常需要詳細的功能清單、遷移計劃、依賴關係映射、平行操作和生產檢驗。這些需求推動了服務合約的普及,尤其是在網路涉及多個供應商和傳統營運平台的情況下。專業服務供應商還幫助電信業者協調網路營運團隊、應用程式所有者、安全團隊和雲端基礎設施合作夥伴之間的工作。
預計到2031年,解決方案市場將以16.11%的複合年成長率成長,超過雲端原生網路功能遷移服務市場的整體成長率。此細分市場包括遷移自動化工具、生命週期管理軟體以及支援容器化網路功能的平台。產品化工具能夠提高跨不同叢集、發布週期和供應商的可重現性,並減少後續遷移階段和定期軟體更新所需的自訂配置工作量。德國電信的「基於營運商的雲端自動化解決方案」採用Kubernetes營運商模式和GitOps原則進行生命週期管理。這種方法充分說明了電信業者為何尋求能夠以更標準化的方式管理有狀態功能和叢集間依賴關係的工具。
預計到2025年,雲端服務供應商將佔總營收的53.62%,並將以15.98%的複合年成長率成長至2031年。部署到公共雲端使電信業者能夠利用彈性基礎設施,而無需承擔建置新資料中心所需的全部成本和時間。此外,也提供支援基於Kubernetes的部署和維運的託管平台服務。這使得雲端託管環境成為需要快速擴展容量的新型獨立核心專案的理想選擇。因此,雲端原生網路功能遷移服務市場需要能夠將網路特定功能與公共雲端營運模式、安全控制和操作流程整合的服務。
2026年2月,TuneTalk透過在AWS基礎架構上部署Mavenir的雲端原生核心網路、OSS和BSS解決方案,成為東協地區首家完全雲端原生的行動網路營運商。諾基亞和Citymesh也於2026年2月開始利用AWS上的5G核心網路SaaS營運商用行動服務。這些部署表明,只要具備必要的效能、安全性和運作安全措施,公有公共雲端就能支援商用行動工作負載。對於那些對延遲敏感、有資料主權要求且現有資料中心容量充足的營運商而言,本地部署環境仍然至關重要。因此,對於許多成熟的營運商來說,混合編配仍然是一項核心需求,而不僅僅是一種過渡方案。
區域分析
2025年,北美將佔據雲端原生網路功能遷移服務市場34.90%的佔有率。該地區匯集了許多大型電信營運商,他們正從最初的獨立核心網路部署遷移到語音、邊緣、企業服務和服務保障營運。 FirstNet專用的5G獨立核心網路展現了雲端原生架構在公共安全網路中的重要角色。此外,該地區還受益於充滿活力的雲端服務供應商、供應商和系統整合商生態系統。 O-RAN聯盟進行的互通性測試為營運商檢驗多供應商接取網路部署奠定了基礎。
在歐洲,德國、英國、法國和其他西歐市場的成熟轉型計畫正在穩步推進,而中東歐的電信業者仍處於引進週期的早期階段。 O2 Telefónica部署混合雲端核心網,展示了區域資料主權要求與公共雲端營運實務如何能夠共存。 2025年9月,歐盟委員會發布了《電信雲端參考架構》,為營運商雲端設計提供了區域性指南,旨在平衡互通性和資料主權。 Proximus於2026年4月推出5G+服務,以及Telia Norge在全國部署商用5G獨立組網,都顯示這一趨勢正在持續發展。
預計到2031年,亞太地區將以16.13%的複合年成長率成長,成為雲端原生網路功能遷移服務市場所有地區中成長最快的地區。 2026年3月,NTT Docomo和NEC在AWS上推出了日本首個商用5G核心網,利用基於代理的AI和GitOps自動化,將設計和建造時間縮短了80%。中國的YD/T 6386-2025標準定義了雲端原生電信網路元件的設計和管理原則。 2026年6月,SK Telecom發布了L4級自治網路藍圖,其中包括下一代OSS的轉型和AI代理的標準化。由於印度Open RAN的擴展以及東南亞新進入者的加入,區域需求不斷成長。同時,中東、南美和非洲仍處於起步階段,一些雲端原生計畫和有針對性的國際夥伴關係正在推進中。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素對市場的影響
- 市場促進因素
- 5G獨立組網核心網和網路切片的部署
- 利用混合雲和多重雲端解決方案實現電信營運商的現代化
- 透過從VNF遷移到CNF來最佳化營運成本
- 面向低延遲服務的邊緣雲端部署
- 人工智慧驅動的編配與服務保障
- 開放的、基於 Kubernetes 的平台可以減少遷移過程中的供應商鎖定。
- 市場限制因素
- 整合傳統OSS和BSS的複雜性
- 營運商層面的互通性和效能差異
- VNF 和 CNF 共存期間過渡停滯的風險
- 跨領域雲端原生運維人員短缺
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 解決方案
- 服務
- 按部署模式
- 雲端服務供應商
- 現場
- 按網域分類的網路功能
- 5G核心網與演進分組核心網
- IP多媒體子系統
- 無線接取網路及開放式無線接取網
- 邊緣運算和多接入邊緣運算
- 其他網路功能域
- 最終用戶
- 電信服務供應商
- 雲端服務供應商
- 大公司
- 小型企業
- 政府和國防機構
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture plc
- Cisco Systems, Inc.
- Dell Technologies Inc.
- Ericsson
- Fujitsu Limited
- Google LLC
- Hewlett Packard Enterprise Company
- Huawei Investment & Holding Co., Ltd.
- International Business Machines Corporation
- Infosys Limited
- Juniper Networks, Inc.
- Mavenir Systems, Inc.
- Microsoft Corporation
- Nokia Corporation
- Oracle Corporation
- Red Hat, Inc.
- Samsung Electronics Co., Ltd.
- Tech Mahindra Limited
- VMware LLC
- ZTE Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the cloud-native network function migration services market size is projected to be USD 2.54 billion in 2025, USD 3.24 billion in 2026, and reach USD 6.29 billion by 2031, growing at a CAGR of 14.19% from 2026 to 2031.
This report is Segmented by Component (Solutions, and Services), Deployment Model (Cloud Service Providers, and On-Premises), Network Function Domain (5G Core and Evolved Packet Core, IP Multimedia Subsystem, and More), End User (Telecom Service Providers, Cloud Service Providers, Large Enterprises, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Cloud-Native Network Function Migration Services Market Trends and Insights
5G Standalone Core and Network Slicing Rollouts
5G standalone cores require cloud-native functions and therefore create direct demand for migration work. Telia Norge launched nationwide commercial 5G standalone service in 2026 and reported latency below 10 milliseconds, compared with 15-18 milliseconds on non-standalone 5G. Proximus launched 5G+ in Belgium in April 2026, adding another commercial rollout that requires cloud-native core capabilities. Network slicing depends on standalone architecture because it needs dynamic allocation of network resources across users and services. The cloud-native network function migration services market benefits when operators bring these capabilities into commercial use rather than maintaining non-standalone networks. ETSI standards provide a shared technical framework for validating service-based network architecture during these migrations.
Hybrid and Multi-Cloud Telco Modernization
Operators increasingly use both public cloud resources and infrastructure inside their own data centers. O2 Telefonica deployed a 5G cloud core on Nokia software running on AWS Outposts in its data centers in March 2026, while serving 1 million customers through this hybrid model. This model combines public-cloud operating tools with local control over sensitive network workloads in the cloud-native network function migration services market. It also makes platform portability more important because operators need functions to operate across different locations and cloud environments. The cloud-native network function migration services market gains from this complexity because migration partners must design, test, and operate the links between cloud platforms. China Telecom identified cloud-native network element evolution and edge AI integration as pillars of its 2026-2030 cloud-network fusion phase.
Legacy OSS and BSS Integration Complexity
Legacy operating support systems and billing support systems remain a practical barrier to cloud-native migration. Established operators often run several OSS and BSS platforms because of earlier acquisitions and separate network deployments. These systems can contain proprietary interfaces and undocumented dependencies that are difficult to connect to containerized network functions. The cloud-native network function migration services market needs experienced integration teams when network provisioning, billing, and service assurance must remain active throughout a cutover. Manual steps can remain necessary when the legacy layer lacks usable programmatic interfaces. This weakens the speed and cost benefits that operators expect from cloud-native automation.
Other drivers and restraints analyzed in the detailed report include:
- OPEX Optimization Through VNF-to-CNF Transformation
- Edge Cloud Deployment for Low-Latency Services
- Telco-Grade Interoperability and Performance Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services held 69.12% of the cloud-native network function migration services market share in 2025, reflecting operators' continuing need for integration, consulting, validation, and managed migration support. Migration programs commonly require detailed function inventories, transition planning, dependency mapping, parallel operation, and production validation. Those requirements favor service engagements when a network includes multiple vendors and older operating platforms. Professional services providers also help operators coordinate network operations teams, application owners, security teams, and cloud infrastructure partners.
Solutions are projected to expand at a 16.11% CAGR through 2031, faster than the overall cloud-native network function migration services market. The segment includes migration automation tools, lifecycle management software, and platforms that support containerized network functions. Productized tools can make deployments more repeatable across separate clusters, release cycles, and technology vendors. They can also reduce the amount of bespoke configuration needed during later migration waves and routine software updates. Deutsche Telekom's Operator-based Cloud Automation Solution uses Kubernetes operator patterns and GitOps principles for lifecycle management. Its approach shows why operators are seeking tools that can manage stateful functions and cross-cluster dependencies in a more standardized way.
Cloud service providers held 53.62% of revenue in 2025 and are projected to expand at a 15.98% CAGR through 2031. Public-cloud deployment gives operators access to elastic infrastructure without the full cost and timing of building new data center capacity. It can also provide managed platform services that support Kubernetes-based deployment and operations. This makes cloud-hosted environments attractive for new standalone core programs that need rapid capacity changes. The cloud-native network function migration services market therefore requires services that connect network-specific functions to public-cloud operating models, security controls, and operating procedures.
Tune Talk became ASEAN's first fully cloud-native mobile network operator in February 2026 through a Mavenir deployment of cloud-native core, OSS, and BSS solutions on AWS infrastructure. Nokia and Citymesh also brought a commercial mobile service using 5G Core SaaS into operation on AWS in February 2026. These deployments indicate that public cloud can support commercial mobile workloads when the required performance, security, and operational safeguards are in place. On-premise environments still matter for latency-sensitive functions, data sovereignty needs, and operators with substantial existing data center capacity. As a result, hybrid orchestration remains a central requirement rather than a temporary transition stage for many established operators.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Model
- Cloud Service Providers
- On-Premises
- By Network Function Domain
- 5G Core and Evolved Packet Core
- IP Multimedia Subsystem
- Radio Access Network and Open RAN
- Edge and Multi-Access Edge Computing
- Other Network Function Domains
- By End User
- Telecom Service Providers
- Cloud Service Providers
- Large Enterprises
- Small and Medium-Sized Enterprises
- Government and Defense Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 34.90% of the cloud-native network function migration services market share in 2025. The region has large operators that are moving from initial standalone core deployment into voice, edge, enterprise service, and service-assurance work. A dedicated 5G standalone core for FirstNet shows the role of cloud-native architecture in public safety networks. The region also benefits from an active ecosystem of cloud providers, network vendors, and systems integrators. Interoperability testing by the O-RAN Alliance gives operators a basis for validating multi-vendor access-network deployments.
Europe has mature migration programs in Germany, the United Kingdom, France, and other Western European markets, while Central and Eastern European operators remain earlier in deployment cycles. O2 Telefonica's hybrid cloud core deployment illustrates how regional data sovereignty requirements can coexist with public-cloud operating methods. The European Commission published the Telco Cloud Reference Architecture in September 2025, providing a regional reference for interoperable and sovereign telco cloud design. Proximus's April 2026 5G+ launch and Telia Norge's nationwide commercial 5G standalone rollout indicate continued momentum.
Asia-Pacific is projected to expand at a 16.13% CAGR through 2031, the highest regional growth rate in the cloud-native network function migration services market. NTT DOCOMO and NEC launched Japan's first commercial 5G core on AWS in March 2026, using agentic AI and GitOps automation that reduced design and construction time by 80%. China's YD/T 6386-2025 standard established design and management principles for cloud-native telecom network elements. SK Telecom released an autonomous network Level 4 blueprint in June 2026 that includes next-generation OSS transformation and AI agent standardization. India's Open RAN expansion and Southeast Asia's greenfield operators broaden regional demand, while the Middle East, South America, and Africa remain earlier-stage areas with selected cloud-native projects and targeted international partnerships.
- Accenture plc
- Cisco Systems, Inc.
- Dell Technologies Inc.
- Ericsson
- Fujitsu Limited
- Google LLC
- Hewlett Packard Enterprise Company
- Huawei Investment & Holding Co., Ltd.
- International Business Machines Corporation
- Infosys Limited
- Juniper Networks, Inc.
- Mavenir Systems, Inc.
- Microsoft Corporation
- Nokia Corporation
- Oracle Corporation
- Red Hat, Inc.
- Samsung Electronics Co., Ltd.
- Tech Mahindra Limited
- VMware LLC
- ZTE Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 5G Standalone Core and Network Slicing Rollouts
- 4.3.2 Hybrid and Multi-Cloud Telco Modernization
- 4.3.3 OPEX Optimization Through VNF-to-CNF Transformation
- 4.3.4 Edge Cloud Deployment for Low-Latency Services
- 4.3.5 AI-Assisted Orchestration and Service Assurance
- 4.3.6 Open, Kubernetes-Based Platforms Reduce Migration Lock-In
- 4.4 Market Restraints
- 4.4.1 Legacy OSS and BSS Integration Complexity
- 4.4.2 Telco-Grade Interoperability and Performance Gaps
- 4.4.3 Migration Freeze Risk During VNF and CNF Coexistence
- 4.4.4 Scarcity of Cross-Domain Cloud-Native Operations Talent
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Competitive Rivalry
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of New Entrants
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Model
- 5.2.1 Cloud Service Providers
- 5.2.2 On-Premises
- 5.3 By Network Function Domain
- 5.3.1 5G Core and Evolved Packet Core
- 5.3.2 IP Multimedia Subsystem
- 5.3.3 Radio Access Network and Open RAN
- 5.3.4 Edge and Multi-Access Edge Computing
- 5.3.5 Other Network Function Domains
- 5.4 By End User
- 5.4.1 Telecom Service Providers
- 5.4.2 Cloud Service Providers
- 5.4.3 Large Enterprises
- 5.4.4 Small and Medium-Sized Enterprises
- 5.4.5 Government and Defense Organizations
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Russia
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Cisco Systems, Inc.
- 6.4.3 Dell Technologies Inc.
- 6.4.4 Ericsson
- 6.4.5 Fujitsu Limited
- 6.4.6 Google LLC
- 6.4.7 Hewlett Packard Enterprise Company
- 6.4.8 Huawei Investment & Holding Co., Ltd.
- 6.4.9 International Business Machines Corporation
- 6.4.10 Infosys Limited
- 6.4.11 Juniper Networks, Inc.
- 6.4.12 Mavenir Systems, Inc.
- 6.4.13 Microsoft Corporation
- 6.4.14 Nokia Corporation
- 6.4.15 Oracle Corporation
- 6.4.16 Red Hat, Inc.
- 6.4.17 Samsung Electronics Co., Ltd.
- 6.4.18 Tech Mahindra Limited
- 6.4.19 VMware LLC
- 6.4.20 ZTE Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 全球雲端遷移軟體市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 雲端遷移服務:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)
 持續智慧市場-2026-2032年全球市場預測
 雲端遷移服務市場機會、成長要素、產業趨勢分析及 2026-2035 年預測。雲端遷移服務市場:依服務類型、服務供應商、遷移策略、資料類型、企業規模、部署模式和產業分類-2026-2032年全球市場預測ERP升級與遷移服務:市場佔有率分析、產業趨勢與統計數據以及成長預測(2026-2031年)
 雲端遷移服務市場規模、佔有率、趨勢和預測:按服務類型、企業規模、部署模式、應用程式、產業和地區分類,2026-2034 年
 雲端遷移服務市場:按元件、部署類型、企業規模、最終用戶產業和地區分類全球雲端辦公室遷移工具市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球雲端遷移服務市場報告