


 |
市場調查報告書
商品編碼
2118935
美國光纖電纜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)United States Fiber Optic Cable - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
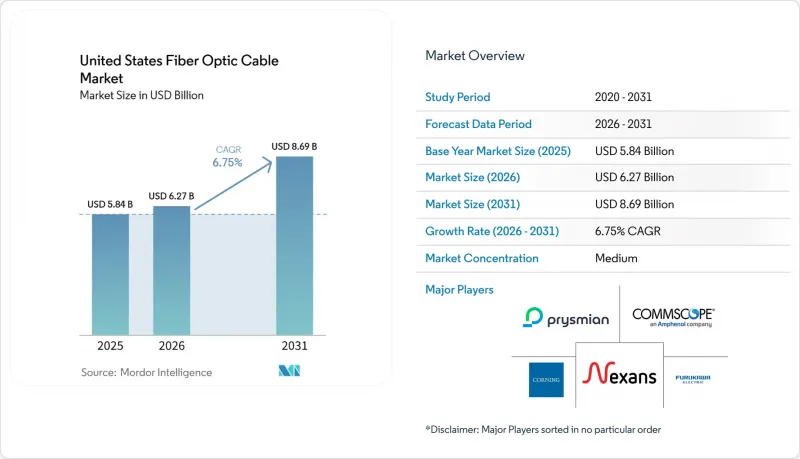
美國光纖電纜市場預計將從 2025 年的 58.4 億美元和 2026 年的 62.4 億美元成長到 2031 年的 86.9 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 6.75%。
本報告按電纜類型(鬆套管、緊包電纜等)、模式(單模、多模)、安裝方式(地下、架空、海底)和終端用戶產業(電信、電力、國防軍事、工業製造、資料中心和雲端服務供應商等)進行細分。市場預測以美元計價。
美國光纖電纜市場趨勢與洞察
人工智慧資料中心互連和 800G/1.6T 的部署正在推動對結構化電纜的需求。
美國光纖電纜市場正受惠於資料中心從孤立式架構轉變為分散式人工智慧GPU叢集的轉變。這些叢集需要超低損耗、高光纖密度的佈線路徑,以連接數十至數百英里範圍內的設施。這些需求增加了運行地理分散式系統作為統一運算環境所需的實體基礎設施。在設施內部,800G介面的普及推動了MPO-24帶狀互連在新設施中的廣泛應用。計劃於2026年過渡到1.6T光連接模組將需要更多的光纖和更嚴格的製造公差。這將使能夠持續進行產品開發並穩定交付高密度產品的製造商獲得優勢。
FTTH(光纖到府)和 5G X-Haul 的加速部署正在支援需求的成長。
到2025年底,光纖寬頻基礎設施將覆蓋超過60%的美國家庭,光是當年就新增了1,180萬個連線。儘管人工智慧相關需求不斷成長,但光纖到府(FTTH)建設仍然是美國光纖電纜市場的主要需求驅動力。隨著中頻寬5G密度的不斷提高,基地台需要連接多個扇區和區域聚合,每英里線路的光纖數量也在增加。電信業者正在共用的室外安裝系統中部署去程傳輸、中傳和寬頻光纖,這推動了對高芯徑光纜的需求。緊包覆光纜在最後一公里和基地台安裝站點非常有用,因為技術人員無需中間分支硬體即可進行端接。能夠以同一產品線滿足寬頻和行動應用需求的供應商,可以在整個部署週期中持續完善其產品組合。
土木工程、授權和土地徵用成本的不斷上漲,給該專案的經濟可行性帶來了壓力。
在許多項目中,土木工程和授權如今比電纜價格對專案經濟效益的影響更大。 2025年,地下電纜鋪設的平均成本達到每英尺18美元,而架空電纜鋪設的平均成本達到每英尺8美元。調查顯示,88%的受訪者預計2026年成本將會增加,原因是人事費用、材料、授權和準備工作成本的上升。許可證採集費用可能佔專案預算的10%,在監管嚴格的地區甚至可能高達30%。鐵路道口、交通部門核准、環境評估、歷史街區以及市政建設凍結等因素都可能使工期延長數週甚至數月。雖然微型溝槽可以降低成本,但由於回收方面的法規不一致,其在許多地區的使用受到限制。
細分市場分析
到2025年,鬆套管光纜將占美國光纖電纜市場32.65%的佔有率。其耐濕耐熱性能使其適用於戶外安裝、架空佈線以及FTTH(光纖到府)、5G回程傳輸和電網專案中使用的長距離線路。帶狀光纜因其高密度熔接能力而常用於高密度戶外安裝,從而縮短了每次熔接的連接時間。而鎧裝光纜則用於直接埋設的公共產業和工業線路,這些線路會受到擠壓力的影響。在2026年光纖通訊展(OFC 2026)上,康寧公司發表了其「Contour Flow」微型光纜,該光纜包含1728根光纖,直徑僅為傳統帶狀光纜的一半左右,並採用低摩擦護套,以便於噴射敷設。這些設計表明,即使在成熟的戶外光纜領域,敷設方法和光纖密度也變得越來越重要。
預計到2031年,緊包光纖電纜的複合年成長率將達到7.80%,成為美國光纖電纜行業所有電纜類型中成長最快的。其直接端接功能使其適用於800G資料中心連結和企業級最後一公里部署,而預端接主幹線在出貨前已將緊包光纖和MPO連接器封裝在通用護套內。與現場拋光連接相比,這些組件可將現場端接時間縮短一半以上,且其在室內佈線中的應用也符合ANSI/TIA-568標準。向1.6T互連技術的過渡預計將增加這些組件中的光纖數量。具備連接器和組件生產能力的製造商可以從電纜和連接相關業務中獲得豐厚利潤,而僅供應電纜的供應商則可能面臨利潤率壓力。
2025年,單模光纖在美國光纖電纜市場佔有61.92%的市佔率。單模光纖對於城域網路、長途網路和光纖到府(FTTH)網路仍然至關重要,因為目前尚無其他可替代的方案能夠以可比規模處理如此遠距離的傳輸。其久經考驗的叢集也支撐了公共寬頻專案和商業線路的需求。受人工智慧GPU集群普及推動,800G機房網路對OM4和OM5光纜的需求增加,預計2026年至2031年多模光纖的複合年成長率將達到7.30%。 IEEE 802.3ck標準進一步鞏固了多模光纖在超大規模採購規範中用於短距離連接的應用。
多模光纜的需求正從低成本的企業區域網路擴展到更廣泛的領域。在人工智慧設施中,採用 OM4 的 800GBASE-SR8 可以支援機架內和機架間長達 100 公尺的鏈路,同時收發器成本低於同等單模配置。 OM5 支援短距離分波多工(WDM),有助於降低伺服器機架內的帶狀光纜密度。單模和多模光纜的選擇主要取決於收發器的價格,因此製造商需要將此因素納入需求規劃。普睿司曼 (Prysmian) 和康寧 (Corning) 將 OM4 和 OM5 定位為人工智慧資料中心產品,這推動了美國光纖光纜市場高價值產品組合的形成,使能夠提供光纖和連接組件的供應商獲得競爭優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- AI資料中心互聯及800G/1.6T部署
- FTTH(光纖到府)和 5G X-Haul 的部署正在加速。
- 聯邦和州寬頻資金,包括 BEAD 和 RDOF。
- 光纖技術應用於公共產業、電網和關鍵基礎設施網路。
- 國內製造業及「建設美國,購買美國貨」採購政策
- 使用高芯數光纜和預端接光纜可以彌補安裝工作上人手不足。
- 市場限制因素
- 土木工程、授權和土地徵用成本不斷上漲。
- 在人口稀少的地區替換固定式無線電衛星和低地球軌道衛星。
- 合格的連接、測試和戶外設備技術人員短缺
- 預成型件、纖維和特殊部件的供應波動
- 價值鏈分析
- 監理情勢
- 技術展望
- 光纖在主要產業的現狀
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按電纜類型
- 鬆管
- 緊緩衝
- 絲帶
- 鎧裝電纜
- 按模式
- 單模
- 多模式
- 依部署類型
- 地下
- 空氣
- 潛水艇型
- 按最終用戶行業分類
- 電訊
- 電力公司
- 國防/軍事
- 工業和製造業
- 資料中心和雲端服務供應商
- 醫療保健
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Prysmian Group
- Corning Inc.
- Nexans SA
- CommScope Holding Company Inc.
- Furukawa Electric Co., Ltd.
- Sumitomo Electric Industries Ltd.
- Sterlite Technologies Limited
- Fujikura Ltd.
- Leoni AG
- Belden Inc.
- LS Cable and System
- HUBER+SUHNER AG
- Hexatronic Group AB
- AFL(Fujikura)
- Optical Cable Corp.
- Coherent Corp.(Finisar Corporation)
- ZTT Group
- Molex LLC
- Clearfield, Inc.
- viaPhoton, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the United States fiber optic cable market size is projected to expand from USD 5.84 billion in 2025 and USD 6.24 billion in 2026 to USD 8.69 billion by 2031, registering a CAGR of 6.75% between 2026 and 2031.
This report is Segmented by Cable Type (Loose-Tube, Tight-Buffered, and More), Mode (Single-Mode, and Multi-Mode), Deployment Type (Underground, Aerial, and Submarine), End-User Industry (Telecommunications, Power Utilities, Defense and Military, Industrial and Manufacturing, Data Centers and Cloud Service Providers, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Fiber Optic Cable Market Trends and Insights
AI Data Center Interconnect and 800G/1.6T Deployment Fuels Structural Cable Demand
The United States fiber optic cable market is benefiting from the shift from isolated data centers to distributed AI GPU clusters. These clusters need ultra-low-loss, high-fiber-count cable routes that can connect facilities across tens or hundreds of miles. These requirements increase the physical infrastructure needed to operate geographically distributed systems as a unified computing environment. Inside facilities, 800G interfaces support wider use of MPO-24 ribbon connections in new construction. The shift toward 1.6T optical interconnects in 2026 requires more fibers and tighter production tolerances. This favors manufacturers that can sustain product development and deliver consistent high-density products.
Accelerating Fiber-to-the-Home and 5G X-Haul Rollouts Underpin Volume Demand
Fiber broadband infrastructure reached more than 60% of US households by the end of 2025, adding 11.8 million homes during the year. Fiber-to-the-home construction remains the main volume driver for the United States fiber optic cable market, even as AI-related demand rises. Mid-band 5G densification uses more fiber strands per route mile because cell sites need connections for several sectors and regional aggregation. Carriers are deploying fronthaul, midhaul, and broadband fiber in shared outside-plant systems, which is driving demand for higher-fiber-count cable. Tight-buffered cable is useful in last-mile and cell-site settings because technicians can terminate it without the need for intermediate breakout hardware. Suppliers that can serve both broadband and mobile applications from the same product range can improve their product mix during the deployment cycle.
Civil Works, Permitting, and Right-of-Way Cost Inflation Compresses Project Economics
Civil works and permits are now more important to project economics than cable pricing in many projects. Median underground deployment costs reached USD 18.00 per foot in 2025, while aerial costs reached USD 8.00 per foot. The same survey found that 88% of respondents expected higher costs in 2026 because of labor, materials, permitting, and make-ready work. Permits can account for 10% of a project budget and reach 30% in difficult jurisdictions. Rail crossings, transportation department approvals, environmental reviews, historic districts, and municipal moratoria can extend schedules by weeks or months. Microtrenching can reduce costs, but inconsistent restoration rules limit its use across many jurisdictions.
Other drivers and restraints analyzed in the detailed report include:
- Federal and State Broadband Funding, Including BEAD and RDOF, Provides Demand Support
- Fiberization of Utility, Grid, and Critical Infrastructure Networks Opens a New Demand Vertical
- Shortage of Qualified Splicing, Testing, and Outside-Plant Technicians Lengthens Build Schedules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Loose-tube cables accounted for 32.65% of the United States fiber optic cable market in 2025. Their moisture resistance and thermal performance make them suitable for outside-plant, aerial, and long-haul routes used by fiber-to-the-home, 5G backhaul, and utility grid projects. Ribbon cable is used in high-density outside-plant builds because mass fusion splicing reduces time per splice, while armored cable is used for direct-burial utility and industrial routes exposed to crushing forces. Corning launched its Contour Flow micro cable at OFC 2026 with 1,728 fibers in nearly half the diameter of legacy ribbon cable and a low-friction jacket for air-jet installation. These designs show that installation method and fiber density are becoming important within established outdoor cable categories.
Tight-buffered cable is projected to grow at a 7.80% CAGR through 2031, the fastest rate among cable types in the United States fiber optic cable industry. Its direct-termination capability suits 800G data center links and enterprise last-mile installations, while pre-terminated trunks place tight-buffered fibers and MPO connectors within a common jacket before delivery. These assemblies can reduce field-termination time by more than half compared with field-polished connections, and ANSI/TIA-568 standards support their use for indoor runs. The move toward 1.6T interconnects is expected to increase fiber counts in these assemblies. Manufacturers with connector and assembly capability can capture cable and connectivity revenue, while cable-only suppliers may face margin pressure.
Single-mode fiber accounted for 61.92% of the United States fiber-optic cable market in 2025. It remains necessary for metro, long-haul, and fiber-to-the-home networks because no practical substitute serves these distances at the same scale. Its installed base supports demand across public broadband programs and commercial routes. Multimode fiber is projected to grow at a 7.30% CAGR from 2026 to 2031 as AI GPU clusters increase demand for OM4 and OM5 cable in 800G intra-facility networks. IEEE 802.3ck has reinforced the use of multimode in hyperscale procurement specifications for short-reach connections.
Multimode demand is extending beyond lower-cost enterprise local area networks. In AI facilities, 800GBASE-SR8 over OM4 can support intra- and inter-rack links up to 100 meters, with lower transceiver costs than comparable single-mode configurations. OM5 supports wavelength-division multiplexing over short distances and can help manage ribbon density inside server racks. The choice between single-mode and multimode depends heavily on transceiver pricing, which producers must include in demand planning. Prysmian and Corning are positioning OM4 and OM5 as AI data center products, supporting a higher-value mix in the United States fiber optic cable market and favoring suppliers that can provide cable and connectivity components.
Complete Report Scope:
- By Cable Type
- Loose-Tube
- Tight-Buffered
- Ribbon
- Armored
- By Mode
- Single-Mode
- Multi-Mode
- By Deployment Type
- Underground
- Aerial
- Submarine
- By End-User Industry
- Telecommunications
- Power Utilities
- Defense and Military
- Industrial and Manufacturing
- Data Centers and Cloud Service Providers
- Healthcare and Medical
- Other End-User Industries
List of Companies Covered in this Report:
- Prysmian Group
- Corning Inc.
- Nexans SA
- CommScope Holding Company Inc.
- Furukawa Electric Co., Ltd.
- Sumitomo Electric Industries Ltd.
- Sterlite Technologies Limited
- Fujikura Ltd.
- Leoni AG
- Belden Inc.
- LS Cable and System
- HUBER+SUHNER AG
- Hexatronic Group AB
- AFL (Fujikura)
- Optical Cable Corp.
- Coherent Corp. (Finisar Corporation)
- ZTT Group
- Molex LLC
- Clearfield, Inc.
- viaPhoton, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI Data-Center Interconnect and 800G/1.6T Deployment
- 4.2.2 Accelerating Fiber-to-the-Home and 5G X-Haul Rollouts
- 4.2.3 Federal and State Broadband Funding, Including BEAD and RDOF
- 4.2.4 Fiberization of Utility, Grid, and Critical-Infrastructure Networks
- 4.2.5 Domestic Manufacturing and Build America, Buy America Procurement
- 4.2.6 High-Fiber-Count and Pre-Terminated Cable Adoption to Offset Installation Labor Constraints
- 4.3 Market Restraints
- 4.3.1 Civil-Works, Permitting, and Right-of-Way Cost Inflation
- 4.3.2 Fixed-Wireless and Low-Earth-Orbit Satellite Substitution in Sparse Areas
- 4.3.3 Shortage of Qualified Splicing, Testing, and Outside-Plant Technicians
- 4.3.4 Preform, Fiber, and Specialized Component Supply Volatility
- 4.4 Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 State of Fiber Optics in Key Industries
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cable Type
- 5.1.1 Loose-Tube
- 5.1.2 Tight-Buffered
- 5.1.3 Ribbon
- 5.1.4 Armored
- 5.2 By Mode
- 5.2.1 Single-Mode
- 5.2.2 Multi-Mode
- 5.3 By Deployment Type
- 5.3.1 Underground
- 5.3.2 Aerial
- 5.3.3 Submarine
- 5.4 By End-User Industry
- 5.4.1 Telecommunications
- 5.4.2 Power Utilities
- 5.4.3 Defense and Military
- 5.4.4 Industrial and Manufacturing
- 5.4.5 Data Centers and Cloud Service Providers
- 5.4.6 Healthcare and Medical
- 5.4.7 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Prysmian Group
- 6.4.2 Corning Inc.
- 6.4.3 Nexans SA
- 6.4.4 CommScope Holding Company Inc.
- 6.4.5 Furukawa Electric Co., Ltd.
- 6.4.6 Sumitomo Electric Industries Ltd.
- 6.4.7 Sterlite Technologies Limited
- 6.4.8 Fujikura Ltd.
- 6.4.9 Leoni AG
- 6.4.10 Belden Inc.
- 6.4.11 LS Cable and System
- 6.4.12 HUBER+SUHNER AG
- 6.4.13 Hexatronic Group AB
- 6.4.14 AFL (Fujikura)
- 6.4.15 Optical Cable Corp.
- 6.4.16 Coherent Corp. (Finisar Corporation)
- 6.4.17 ZTT Group
- 6.4.18 Molex LLC
- 6.4.19 Clearfield, Inc.
- 6.4.20 viaPhoton, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Rural Middle-Mile and Tribal Broadband Deployment Gaps
- 7.1.2 Domestic High-Density Cable and Connector Capacity
- 7.1.3 Fiber for AI Factory and Edge-Data-Center Expansion
- 7.1.4 Utility-Fiber Leasing and Shared-Infrastructure Models
- 7.1.5 Labor-Saving Pre-Terminated and Modular Deployment Systems

 特種光纖電纜市場-全球及區域分析:按應用、產品與國家分類-分析與預測,2026-2036年
 美國及歐洲光纖電纜:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 模式調節電纜市場規模、佔有率和成長分析:按電纜類型、連接器類型、應用、最終用戶和地區分類-2026年至2033年產業預測光纖電纜:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 光纖電纜市場-2026-2032年全球市場預測智慧公路和自動駕駛基礎設施中的光纖電纜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)鐵路和地鐵基礎設施用光纖電纜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026-2030年全球軍用級光纖電纜市場
 光纖電纜市場商機、成長要素、產業趨勢分析及2026-2035年預測
 光纖電纜市場預測至2034年—按光纖類型、電纜類型、安裝類型、應用、最終用戶和地區分類的全球分析