


 |
市場調查報告書
商品編碼
2116919
印尼聚丙烯市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Indonesia Polypropylene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
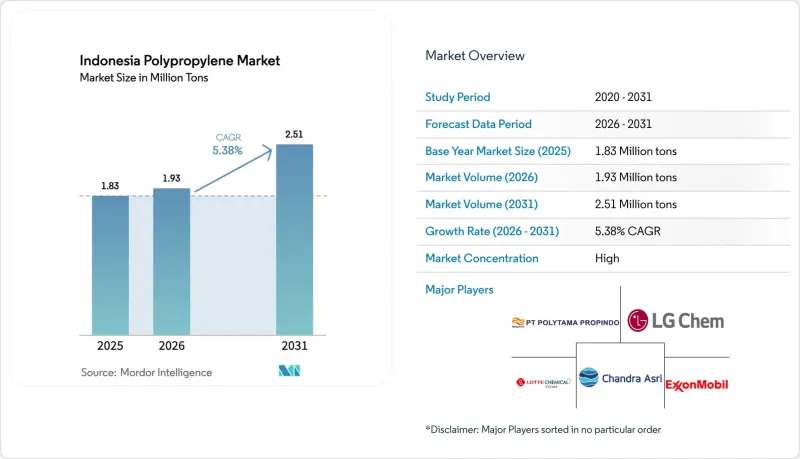
據 Mordor Intelligence 稱,印尼聚丙烯市場預計到 2026 年將達到 193 萬噸,高於 2025 年的 183 萬噸,預計到 2031 年將達到 251 萬噸。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.38%。
本報告按類型(均聚物和共聚物)、終端用戶行業(包裝、汽車、消費品、電氣和電子等)以及應用(射出成型、紡織品、薄膜和片材等)進行分類。市場預測以噸為單位。
印尼聚丙烯市場趨勢與分析
對軟包裝的需求正在激增。
為了遵守2019年第75號法規(法規要求在2029年實現包裝材料100%回收),零食和日常消費品(FMCG)製造商正在將多層包裝袋重新設計為可回收的單層材料薄膜。到2024年,已有21家食品飲料公司提交了正式的藍圖,而像大日本印刷印尼公司這樣的加工商已經推出了單層聚丙烯產品,每年將取代4萬噸難以回收的泡麵包裝。中產階級對便捷單份包裝的需求正在推動銷售量,而聚丙烯因其在密封性、剛性和透明度方面的出色平衡而優於多層複合材料。隨著品牌商將生產轉向國產均聚物和無規共聚物薄膜,印尼聚丙烯市場正從中受益。芝勒貢新增產能的提高縮短了加工商的前置作業時間,並降低了原物料價格風險。
促進國內汽車OEM供應鏈的減重
在2025年上半年,汽車製造商在成品車在在地採購率達到40%的政策指引下,共生產了551,082輛汽車。與鋼材相比,添加30%至40%玻璃纖維的聚丙烯複合材料在後行李箱蓋和前端模組中可減輕高達40%的重量,同時滿足碰撞安全標準。這種替代方式有利於印尼聚丙烯市場,因為隨著原料本地化,進口組件減少。電動車(EV)的獎勵提高了減重的價值,而Chandra Asri和Politama Propindo產能的提升則為複合材料提供了均聚物原料。原始設備製造商(OEM)的檢驗週期表明,預計至少在未來四個車型年內,市場需求將保持穩定。
在飲料和包裝袋領域,PET和rPET面臨激烈的競爭。
預計到2024年,印尼的PET消費量將達到100萬噸。隨著各大飲料品牌承諾使用100%再生寶特瓶,PET在透明應用領域的領先地位進一步鞏固。印尼PET回收率的提高以及250萬噸的回收基礎設施建設,使其在2029年實現50%再生材料含量目標方面處於有利地位。然而,在印尼聚丙烯市場,這一趨勢導致PET在高階飲料和阻隔性包裝袋領域的滲透率下降。加工商被迫將產品差異化,不再以透明度取勝,而是以剛性和耐熱性作為競爭優勢。
細分市場分析
預計到2025年,均聚物將佔印尼聚丙烯市場佔有率的69.45%,並在2031年之前以5.59%的複合年成長率成長。這反映了射出成型成型汽車零件和硬質包裝組件對均聚物低成本、高剛性的需求不斷成長。預計到2031年,印尼均聚物市場規模將達到176萬噸,主要驅動力是樂天化學面向通用級聚丙烯的新生產線的運作。印尼國內加工商在遵守國產化率(TKDN)規定的同時,實現了供應穩定和訂單週期縮短。
共聚物廣泛應用於瓶蓋、封蓋和抗衝擊薄膜等領域,這些產品需要兼具柔軟性和透明度。儘管對共聚物進口徵收的反傾銷稅阻礙了銷售量成長,但由於生產者延伸責任制(EPR)法規下單一材料薄膜的推廣應用,市場對其的興趣正在復甦。中期來看,市場成功與否將取決於本地製造商能否升級其反應器,並確保無規共聚物和抗衝擊共聚物的產能。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 印尼零嘴零食和日常消費品(FMCG)產業的快速成長,帶動了對軟包裝需求的激增。
- 促進國內汽車OEM廠商供應鏈的減重
- 隨著電子商務履約網路的快速擴張,對耐用托特包和薄膜解決方案的需求日益成長。
- 國內反傾銷稅有利於國產聚丙烯產品而非進口產品。
- 巴厘巴板新煉油廠和聚丙烯(PP)聯合裝置的石化產品一體化
- 市場限制因素
- 在飲料和軟包裝產品領域,PET 和 rPET 構成競爭。
- 與主要使用乙烷作為原料的進口產品不同,石腦油原料的價格波動很大。
- 加強雅加達和峇裡島兩省的塑膠廢棄物管理條例
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 均聚物
- 共聚物
- 按最終用戶行業分類
- 包裝
- 車
- 消費品
- 電氣和電子設備
- 其他
- 透過使用
- 射出成型
- 纖維
- 薄膜和片材
- 其他
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率(%)/排名分析
- 公司簡介
- Argha Karya Prima Industry Tbk
- BASF
- Exxon Mobil Corporation
- INEOS
- LG Chem
- LOTTE Chemical CORPORATION
- LyondellBasell Industries Holdings BV
- Mitsubishi Chemical Corporation
- NAGA SEMUT
- PT Chandra Asri Petrochemical
- PT Langgeng Jaya Group
- PT Polytama Propindo
- PT Trias Sentosa Tbk
- SABIC
- Sumitomo Corporation
- TORAY INDUSTRIES, INC.
第7章 市場機會與未來展望
According to Mordor Intelligence, indonesia polypropylene market size in 2026 is estimated at 1.93 million tons, growing from 2025 value of 1.83 million tons with 2031 projections showing 2.51 million tons, growing at 5.38% CAGR over 2026-2031.
This report is Segmented by Type (Homopolymer and Copolymer), End-User Industry (Packaging, Automotive, Consumer Products, Electrical and Electronics, and Others), and Application (Injection Molding, Fiber, Film and Sheet, and Other). The Market Forecasts are Provided in Terms of Volume (Tons).
Indonesia Polypropylene Market Trends and Insights
Surge in Flexible-Packaging Demand
Snack and FMCG producers are redesigning multilayer sachets into recyclable mono-material films to comply with Regulation 75/2019 that mandates 100% recyclable packaging by 2029. Twenty-one food and beverage companies filed official roadmaps in 2024, and converters such as Dai Nippon Printing Indonesia launched mono-material polypropylene formats that replace 40 kilotons of difficult-to-recycle instant-noodle wrap each year. Middle-class demand for convenient single-serve packs accelerates volume, and polypropylene's balance of sealability, stiffness, and clarity makes it the preferred candidate over multilayer laminates. The Indonesia polypropylene market benefits as brand owners shift volumes to domestically produced homopolymer and random-copolymer film grades. New capacity in Cilegon shortens lead times for converters and tempers raw-material price risk.
Lightweighting Push in Domestic Automotive OEM Supply Chains
Vehicle assemblers produced 551,082 units in H1 2025 under a policy that requires 40% local content on finished vehicles. Polypropylene compounds reinforced with 30%-40% glass fiber deliver up to 40% weight savings over steel for liftgates and front-end modules while meeting crash standards. The Indonesia polypropylene market gains from this substitution because the material is sourced locally, reducing imported assemblies. Electric-vehicle incentives raise the value of mass reduction, and capacity expansions at Chandra Asri and Polytama Propindo supply homopolymer feedstock for compounding. OEM validation cycles indicate steady demand visibility for at least four model years.
Competition from PET and rPET in Beverage and Pouch Formats
Indonesia consumed 1 million tons of PET in 2024, and leading beverage brands committed to using 100% recycled PET bottles, reinforcing PET's dominance in transparent applications. Higher collection rates and a 2.5 million-ton recycling infrastructure favor PET when producers must hit 50% recycled-content targets by 2029. For the Indonesia polypropylene market, this trend reduces penetration in premium beverage and high-barrier pouch categories. Converters are forced to differentiate based on rigidity and heat performance rather than clarity.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Build-Out of E-Commerce Fulfillment Networks
- Local Anti-Dumping Duties Favoring Domestic PP Versus Imports
- Volatile Naphtha Feedstock Costs Versus Ethane-Advantaged Imports
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Homopolymer captured 69.45% of the Indonesia polypropylene market share in 2025 and is forecast to grow at a 5.59% CAGR through 2031, reflecting its low cost and high stiffness in injection-molded automotive and rigid-packaging parts. The Indonesia polypropylene market size for homopolymer is predicted to reach 1.76 million tons by 2031, aided by Lotte Chemical's new line that mainly targets general-purpose grades. Domestic converters gain security of supply and faster order cycles, aligning with TKDN local-content rules.
Copolymer serves caps, closures, and impact-modified films that require flexibility or clarity. Anti-dumping duties on copolymer imports have curtailed volume growth; however, the adoption of mono-material film under EPR rules is reviving interest. In the medium term, success depends on local producers upgrading reactors to random- and impact-copolymer capability.
Complete Report Scope:
- By Type
- Homopolymer
- Copolymer
- By End-user Industry
- Packaging
- Automotive
- Consumer Products
- Electrical and Electronics
- Others
- By Application
- Injection Molding
- Fiber
- Film and Sheet
- Other
List of Companies Covered in this Report:
- Argha Karya Prima Industry Tbk
- BASF
- Exxon Mobil Corporation
- INEOS
- LG Chem
- LOTTE Chemical CORPORATION
- LyondellBasell Industries Holdings BV
- Mitsubishi Chemical Corporation
- NAGA SEMUT
- PT Chandra Asri Petrochemical
- PT Langgeng Jaya Group
- PT Polytama Propindo
- PT Trias Sentosa Tbk
- SABIC
- Sumitomo Corporation
- TORAY INDUSTRIES, INC.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in flexible-packaging demand from Indonesia's booming snack and FMCG sectors
- 4.2.2 Lightweighting push in domestic automotive OEM supply chains
- 4.2.3 Rapid build-out of e-commerce fulfilment networks needing durable tote and film solutions
- 4.2.4 Local anti-dumping duties favouring domestic PP versus imports
- 4.2.5 Petrochemical integration at new Balikpapan refinery-to-PP complex
- 4.3 Market Restraints
- 4.3.1 Competition from PET and rPET in beverage and pouch formats
- 4.3.2 Volatile naphtha feedstock costs versus ethane-advantaged imports
- 4.3.3 Intensifying plastics-waste regulation in Jakarta and Bali provinces
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Homopolymer
- 5.1.2 Copolymer
- 5.2 By End-user Industry
- 5.2.1 Packaging
- 5.2.2 Automotive
- 5.2.3 Consumer Products
- 5.2.4 Electrical and Electronics
- 5.2.5 Others
- 5.3 By Application
- 5.3.1 Injection Molding
- 5.3.2 Fiber
- 5.3.3 Film and Sheet
- 5.3.4 Other
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Argha Karya Prima Industry Tbk
- 6.4.2 BASF
- 6.4.3 Exxon Mobil Corporation
- 6.4.4 INEOS
- 6.4.5 LG Chem
- 6.4.6 LOTTE Chemical CORPORATION
- 6.4.7 LyondellBasell Industries Holdings BV
- 6.4.8 Mitsubishi Chemical Corporation
- 6.4.9 NAGA SEMUT
- 6.4.10 PT Chandra Asri Petrochemical
- 6.4.11 PT Langgeng Jaya Group
- 6.4.12 PT Polytama Propindo
- 6.4.13 PT Trias Sentosa Tbk
- 6.4.14 SABIC
- 6.4.15 Sumitomo Corporation
- 6.4.16 TORAY INDUSTRIES, INC.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 2026-2030年全球聚丙烯市場
 改質聚丙烯蠟市場規模、佔有率和成長分析:按改性類型、形態、應用、最終用途產業、功能和地區分類-2026-2033年產業預測
 聚丙烯:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 改質聚丙烯市場:全球預測,2026-2032年聚丙烯市場:依類型、形狀、加工技術、終端用途產業及通路分類-2026-2032年全球市場預測
 聚丙烯玻璃纖維增強複合材料市場-全球產業規模、佔有率、趨勢、機會、預測:銷售管道、最終用途、地區和競爭格局分類,2021-2031年
 全球聚丙烯樹脂市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 改質聚丙烯市場規模、佔有率和成長分析:按類型、加工方法、最終用途和地區分類-2026-2033年產業預測
 聚丙烯紗線市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測
 2026年全球聚丙烯熱固性聚合物市場報告