


 |
市場調查報告書
商品編碼
2116110
印度UPVC門窗:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)India UPVC Doors And Windows - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年印度 UPVC 門窗市值為 14.9 億美元,預計到 2031 年將從 2026 年的 16 億美元成長至 22.7 億美元,預測期(2026-2031 年)的複合年成長率為 7.28%。
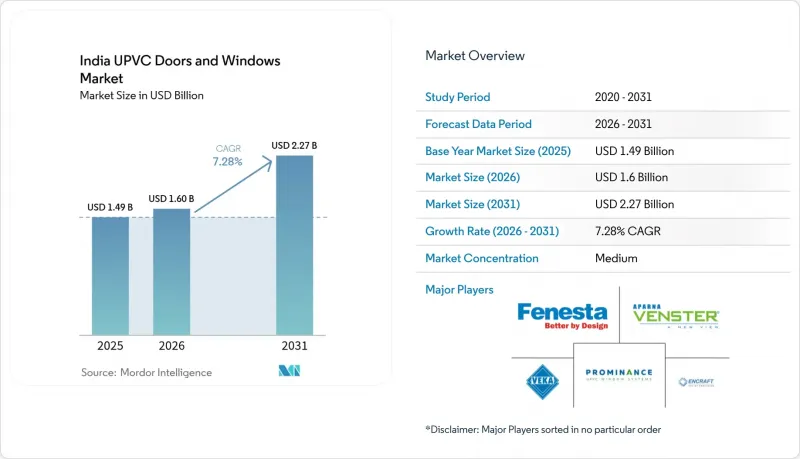
本報告按產品類型(UPVC窗戶、UPVC門)、最終用戶(住宅、商業、其他)、設計類型(滑動窗、平開窗、內傾內開窗、其他)、安裝類型(新建、更換/維修)、分銷管道(製造商直銷、經銷商/分銷商)和地區進行細分。市場預測以美元(USD)為單位。
印度UPVC門窗市場趨勢與洞察
政府推廣節能環保、經濟適用住宅計畫。
包括「總理陽光住房計畫」(PM Surya Ghar Yojana)和「總理住房計畫-城市2.0」(Pradhan Mantri Awas Yojana-Urban 2.0)在內的多項聯邦政府舉措,將住宅補貼與節能建築要求掛鉤,並推薦使用UPVC門窗。 2017年修訂的《節能建築標準》引入了自願分級制度,獎勵節能25%至50%的建築,並將UPVC型材定位為符合標準的解決方案。即將推出的《節能永續建築標準指南》(2024-2025年經濟調查中提及)將進一步把熱性能指標納入建築許可核准流程。這些措施支持印度2070年實現淨零排放的承諾,並鼓勵開發商採用高隔熱性能的門窗。因此,由於公共部門住宅建設計畫已擴展到大都會圈,印度的UPVC門窗市場正經歷持續成長。
在二、三線城市,消費者越來越偏好維護成本低的開門產品。
2021年至2023年,二、三線城市的住宅交易量以14%的複合年成長率成長,超過了大都會圈、泰米爾納德邦和古吉拉突邦的沿海地區,UPVC正迅速普及,因為這些地區鹽分較高的空氣會加速木材和常見鋁製門窗的劣化。像Fenesta這樣擁有超過250家經銷商的零售展示室,有助於提高消費者對產品的認知度,並為新買家提供技術諮詢。這些因素共同推動了印度UPVC門窗市場的發展,使其拓展到曾經幾乎完全依賴低性能材料的領域。
高消費稅稅率(18%),而鋁和木材替代品的稅率為12%。
PVC聚合物(商品及服務稅HSN 3904)需繳納18%的商品及服務稅(GST),而鋁和木質框架則適用12%的稅率,導致UPVC產品在價格上處於6個百分點的劣勢。這一差異進一步擴大了價格敏感型細分市場的初始成本差距,尤其是在二、三線城市,這些地區的消費者對產品生命週期成本節約的認知仍然有限。為此,製造商正在製定價值工程和融資方案,重點關注產品生命週期內的節能效果。即使效能優勢顯著,高額稅負也阻礙了UPVC產品的快速普及。市場參與企業預計,未來商品及服務稅的調整將推動印度UPVC門窗市場更快成長。
細分市場分析
到2025年,UPVC窗戶將佔印度UPVC門窗市場佔有率的55.68%,這反映了它們作為節能開啟產品的重要切入點的地位。此細分市場受益於高更換頻率以及與政策相關的隔熱性能目標(可獲得綠色建築積分)的直接關聯。高級產品系列採用多腔型材和層壓飾面,以滿足大都會圈和第二線城市日益成長的美學需求。製造商也在本地化生產抗紫外線樹脂化合物,以確保即使在印度強烈的陽光照射下,產品也能保持結構完整性。 [4] 這些因素共同確保了窗戶仍然是印度UPVC門窗市場最大的收入來源。
塑鋼門是成長最快的產品類別,預計從2026年到2031年將以8.12%的複合年成長率成長,穩步提升其在印度塑鋼門窗市場的佔有率。人們對多點鎖和鋼筋加固框架的日益重視,推動了高階和中端住宅對塑鋼門的採用,因為安全性是這些住宅的關鍵購買因素。門更換週期的延長降低了消費者對價格的敏感度,從而促進了設計師填充板和電子門禁系統的提升銷售。採用鋁箔外觀和冷色調技術的新產品的推出,進一步吸引了那些既追求金屬美感又不願犧牲隔熱性能的建築師。因此,預計到2030年,塑鋼門與傳統門窗的銷售差距將縮小。
2025年,住宅領域佔印度UPVC門窗市場的66.55%。這主要得益於聯邦政府的住宅建設支持計劃以及首次住宅可支配收入的增加。政府補貼計畫強制使用創新環保材料,鼓勵低收入購屋者選擇UPVC,從而提振了大都會圈和新興城市的需求。開發商強調UPVC門窗維護成本低、節能,以此證明其在中等收入項目中的較高價格是合理的,因為生命週期成本會影響購屋決策。快速的都市化和不斷成長的年輕人口進一步縮短了房屋翻新週期,即使在市場飽和的地區,重複購買的需求仍然存在。因此,住宅支撐了印度UPVC門窗市場的潛在銷售。
預計到2031年,商業用途將以8.57%的複合年成長率成長,成為印度UPVC門窗市場成長最快的收入驅動型細分市場。印度能源效率局的星級評定系統鼓勵建築師採用U值較低的UPVC型材,以獲得合規積分和更高的租金溢價。開發商也青睞UPVC的隔音性能,這在高密度商業區日益受到重視。隨著跨國公司將其分支機構擴展到二線城市,大都會圈的既定規範正在全國推廣。這種發展勢頭表明,到2030年,商業建築將是收入成長的最大貢獻者。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府推廣節能、環保和經濟適用住宅計劃
- 二、三線城市消費者越來越傾向偏好維護成本低的門窗。
- 新冠疫情後房地產維修加速進行,並推高了維修需求。
- 有組織的零售展示室和電子商務配置器迅速擴張
- 透過提高國內PVC產能來緩解原物料成本波動(信實集團、阿達尼集團)
- 將智慧家庭感測器和物聯網鎖具整合到UPVC型材中
- 市場限制因素
- 與鋁和木材替代品 12% 的稅率相比,商品及服務稅 (GST) 的稅率高達 18%。
- 由於長期缺乏熟練的安裝技術人員,導致品質意識出現問題。
- 高階硬體多腔設定檔中的導入依賴關係
- 高階市場中,來自隔熱鋁系統的競爭日益加劇
- 產業價值鏈分析
- 波特五力模型
- 洞察最新市場趨勢與創新
- 近期產業趨勢分析(新產品發布、策略性舉措、投資、合作、合資、業務擴張、併購等)
第5章 市場規模與成長預測
- 依產品類型
- UPVC窗戶
- UPVC門
- 依設計類型
- 滑動
- 平開窗
- 傾斜和旋轉
- 其他(法式、遮陽棚等)
- 按安裝類型
- 新建工程
- 更換/維修
- 最終用戶
- 住宅
- 商業
- 工業和基礎設施
- 透過分銷管道
- 廠商直銷
- 經銷商/分銷商
- 按地區
- 北方
- 西
- 南部
- 東
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Fenesta Building Systems(DCM Shriram)
- Encraft India Pvt Ltd
- VEKA India
- Rehau India Pvt Ltd
- Deceuninck Profiles
- Prominance Window Systems
- Aparna Venster
- Window Magic India
- Koemmerling India
- LG Hausys India
- NCL VEKA Ltd
- Lesso India
- Lingel Windows & Doors Technologies
- Shani Corporation(CORA Windows)
- Aluplast India
- AIS Windows
- Welltech Systems
- KAKA Profiles Pvt Ltd
- Elite Window Factory
- Eurostar Fenestration
- Perfect Window Solutions
第7章 市場機會與未來展望
According to Mordor Intelligence, the India UPVC windows and doors market size was valued at USD 1.49 billion in 2025 and estimated to grow from USD 1.6 billion in 2026 to reach USD 2.27 billion by 2031, at a CAGR of 7.28% during the forecast period (2026-2031).
This report is Segmented by Product Type (UPVC Windows, UPVC Doors), End-Use Sector (Residential, Commercial, and More), Design Type (Sliding, Casement, Tilt-And-Turn, Others), Installation Type (New Construction, Replacement & Renovation), Distribution Channel (Direct From the Manufacturers, Dealers and Distributors) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
India UPVC Doors And Windows Market Trends and Insights
Government Push for Energy-Efficient, Green & Affordable Housing Schemes
Multiple federal initiatives, including PM Surya Ghar Yojana and Pradhan Mantri Awas Yojana-Urban 2.0, link housing subsidies with energy-efficient construction requirements that favor UPVC fenestration. The Energy Conservation Building Code 2017 update created voluntary tiers that reward 25%-50% energy savings, positioning UPVC profiles as a compliant solution. Upcoming Energy Conservation & Sustainable Building Code guidelines referenced in the Economic Survey 2024-25 further embed thermal-performance metrics in building approvals. These policy layers support India's 2070 net-zero pledge, driving developers to specify high-insulation windows and doors. Consequently, the India UPVC windows and doors market receives a sustained boost from public-sector housing pipelines that extend well beyond metros.
Rising Consumer Preference for Low-Maintenance Fenestration in Tier-II & III Cities
Housing transactions in Tier-II and Tier-III cities expanded at 14% CAGR between 2021 and 2023, outpacing metro growth and creating new demand hubs for durable fenestration. Dual-income households in these cities prioritize products that minimize upkeep, and UPVC's resistance to termites, corrosion and weathering aligns with that expectation. Coastal zones in Karnataka, Tamil Nadu, and Gujarat adopt UPVC quickly because salt-laden air accelerates the degradation of wood and basic aluminum alternatives. Organized retail showrooms, such as Fenesta's 250-plus dealer network, improve product visibility and technical guidance for new buyers. These factors collectively expand the India UPVC windows and doors market into geographies that once relied almost entirely on lower-performance materials.
High GST Bracket (18%) Versus 12% on Aluminium & Wood Alternatives
PVC polymers classified under HSN 3904 attract 18% GST, while aluminum and wood frames fall into the 12% band, imposing a 6-percentage-point price handicap on UPVC products. The differential amplifies upfront cost gaps in price-sensitive segments, especially in Tier-II and Tier-III cities where awareness of lifecycle savings remains limited. Manufacturers respond with value-engineering and financing schemes that highlight energy-bill reductions over the product lifespan. Nonetheless, higher tax outlays constrain rapid adoption even when performance credentials are superior. Market participants anticipate that future GST rationalization could unlock faster growth for the India UPVC windows and doors market.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Real-Estate Renovations Post-COVID Unlocking Retrofit Demand
- Rapid Expansion of Organised Retail Showrooms & E-Commerce Configurators
- Persistent Skilled-Installer Deficit Causing Quality-Perception Issues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
UPVC windows captured 55.68% of the India UPVC windows and doors market share in 2025, reflecting their role as the primary entry point for energy-efficient fenestration. The segment benefits from higher replacement frequency and direct alignment with policy-linked thermal-performance goals that award green-building credits. Premium product lines now feature multi-chamber profiles and laminated finishes that meet evolving aesthetic expectations in metros and Tier-II cities alike. Manufacturers also localize resin compounds for UV resistance, ensuring structural integrity under intense Indian sunlight[4]. Together, these factors keep windows the largest revenue contributor within the India uPVC windows and doors market.
UPVC doors represent the fastest-growing product segment, advancing at an 8.12% CAGR for 2026-2031 and steadily raising their contribution to the India UPVC windows and doors market size. Increased awareness of multi-point locking and steel-reinforced frames boosts adoption in premium and mid-market housing, where security is a key purchase criterion. Longer door replacement cycles reduce price sensitivity, enabling upselling of designer infill panels and electronic access controls. Product launches featuring aluminium-look foils and cool-color technology further expand appeal to architects who prefer metallic aesthetics without thermal penalties. As a result, doors are expected to narrow the historical volume gap with windows by 2030.
The residential segment held 66.55% of the India UPVC windows and doors market in 2025, supported by federally subsidized housing pipelines and rising disposable incomes among first-time homeowners. Government grants that mandate innovative green materials steer low-income buyers toward UPVC, bolstering demand in both metros and emerging cities. Developers highlight reduced maintenance and energy savings to justify UPVC premiums in mid-income projects where lifecycle costs influence purchasing decisions. Rapid urbanization and a younger demographic further shorten renovation cycles, sustaining repeat demand even in saturated localities. Consequently, residential construction anchors baseline volume for the India UPVC windows and doors market.
Commercial applications are projected to rise at an 8.57% CAGR through 2031, making them the quickest revenue driver in the India uPVC windows and doors market size. Bureau of Energy Efficiency star-rating protocols influence architects to specify UPVC profiles with low U-values to earn compliance points and tenant leasing premiums. Developers also favor UPVC for acoustic insulation, a growing concern in high-density business districts. As multinational firms expand satellite offices in Tier-II hubs, specification norms established in metros replicate nationwide. This momentum positions commercial builds as the fastest contributor to incremental revenue through 2030.
Complete Report Scope:
- By Product Type
- UPVC Windows
- UPVC Doors
- By Design Type
- Sliding
- Casement
- Tilt-and-Turn
- Others (French, Awning, etc.)
- By Installation Type
- New Construction
- Replacement & Renovation
- By End-user
- Residential
- Commercial
- Industrial & Infrastructure
- By Distribution Channel
- Direct from the Manufacturers
- Dealers and Distributors
- By Region
- North
- West
- South
- East
List of Companies Covered in this Report:
- Fenesta Building Systems (DCM Shriram)
- Encraft India Pvt Ltd
- VEKA India
- Rehau India Pvt Ltd
- Deceuninck Profiles
- Prominance Window Systems
- Aparna Venster
- Window Magic India
- Koemmerling India
- LG Hausys India
- NCL VEKA Ltd
- Lesso India
- Lingel Windows & Doors Technologies
- Shani Corporation (CORA Windows)
- Aluplast India
- AIS Windows
- Welltech Systems
- KAKA Profiles Pvt Ltd
- Elite Window Factory
- Eurostar Fenestration
- Perfect Window Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Push For Energy-Efficient, Green & Affordable Housing Schemes
- 4.2.2 Rising Consumer Preference For Low-Maintenance Fenestration In Tier-Ii & Iii Cities
- 4.2.3 Accelerated Real-Estate Renovations Post-Covid Unlocking Retrofit Demand
- 4.2.4 Rapid Expansion Of Organised Retail Showrooms & E-Commerce Configurators
- 4.2.5 Domestic Pvc Capacity Additions (Reliance, Adani) Reducing Raw-Material Cost Volatility
- 4.2.6 Integration Of Smart-Home Sensors & Iot-Ready Locks Into Upvc Profiles
- 4.3 Market Restraints
- 4.3.1 High Gst Bracket (18%) Versus 12% On Aluminium & Wood Alternatives
- 4.3.2 Persistent Skilled-Installer Deficit Causing Quality-Perception Issues
- 4.3.3 Import Dependence For Premium Hardware & Multi-Chamber Profiles
- 4.3.4 Rising Competition From Thermally-Broken Aluminium Systems In Premium Segment
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights into the Latest Trends and Innovations in the Market
- 4.7 Insights on Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Industry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 UPVC Windows
- 5.1.2 UPVC Doors
- 5.2 By Design Type
- 5.2.1 Sliding
- 5.2.2 Casement
- 5.2.3 Tilt-and-Turn
- 5.2.4 Others (French, Awning, etc.)
- 5.3 By Installation Type
- 5.3.1 New Construction
- 5.3.2 Replacement & Renovation
- 5.4 By End-user
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.3 Industrial & Infrastructure
- 5.5 By Distribution Channel
- 5.5.1 Direct from the Manufacturers
- 5.5.2 Dealers and Distributors
- 5.6 By Region
- 5.6.1 North
- 5.6.2 West
- 5.6.3 South
- 5.6.4 East
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Fenesta Building Systems (DCM Shriram)
- 6.4.2 Encraft India Pvt Ltd
- 6.4.3 VEKA India
- 6.4.4 Rehau India Pvt Ltd
- 6.4.5 Deceuninck Profiles
- 6.4.6 Prominance Window Systems
- 6.4.7 Aparna Venster
- 6.4.8 Window Magic India
- 6.4.9 Koemmerling India
- 6.4.10 LG Hausys India
- 6.4.11 NCL VEKA Ltd
- 6.4.12 Lesso India
- 6.4.13 Lingel Windows & Doors Technologies
- 6.4.14 Shani Corporation (CORA Windows)
- 6.4.15 Aluplast India
- 6.4.16 AIS Windows
- 6.4.17 Welltech Systems
- 6.4.18 KAKA Profiles Pvt Ltd
- 6.4.19 Elite Window Factory
- 6.4.20 Eurostar Fenestration
- 6.4.21 Perfect Window Solutions
7 Market Opportunities & Future Outlook
- 7.1 Affordable Housing Projects Driving uPVC Adoption
- 7.2 Replacement of Wood and Aluminum Windows
- 7.3 Government Push for Energy-Efficient Buildings

 2026-2030年全球UPVC門窗市場
 北美UPVC門窗:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031年)UPVC門窗:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 UPVC門窗市場-全球產業規模、佔有率、趨勢、機會和預測:按產品類型、最終用戶、分銷管道、地區和競爭格局分類,2021-2031年
 塑鋼門窗市場規模、佔有率及趨勢分析報告:依產品、應用、地區及細分市場預測(2026-2033 年)
 PVC-U門窗市場:依玻璃類型、產品類型、表面處理、型材腔體、銷售管道、窗戶系統類型、門系統類型、最終用戶、應用領域分類,全球預測(2026-2032)
 全球PVC窗框型材市場規模、佔有率、趨勢及成長分析報告(2026-2034年)
 2026年全球商用聚氯乙烯(PVC)窗型材市場報告住宅用UPVC門窗市場-全球產業規模、佔有率、趨勢、機會及預測(依產品類型、配銷通路、地區及競爭格局分類,2021-2031年預測)
 硬質PVC門窗:全球市佔率及排名、總收入及需求預測(2025-2031年)