


 |
市場調查報告書
商品編碼
2114743
消泡塗料添加劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Defoaming Coating Additive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
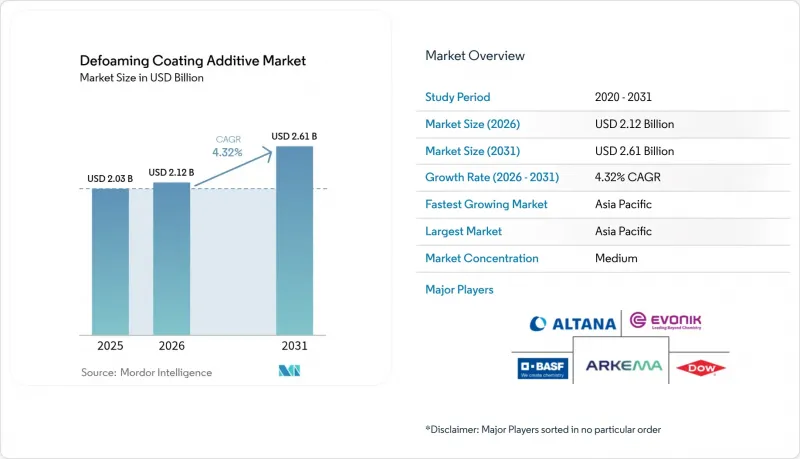
據 Mordor Intelligence 稱,2026 年消泡塗料添加劑的市場規模估計為 21.2 億美元,高於 2025 年的 20.3 億美元,預計到 2031 年將達到 26.1 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.32%。
本報告按產品類型(水性系統和溶劑型系統)、終端用戶產業(建築施工、汽車和交通運輸、木材和家具以及其他終端用戶產業)和地區(亞太地區、北美地區、歐洲地區、南美地區以及中東和非洲地區)進行細分。市場預測以美元計價。
全球消泡塗料添加劑市場趨勢及洞察
建築塗料需求不斷成長
快速的都市化和基礎設施現代化推動了全球建築飾面中發泡需求的成長。儘管噴塗式高膜厚系統目前已廣泛應用於商業外觀和土木工程結構,但即使是微小的氣泡也會影響附著力和長期耐久性。低VOC塗料的普及加劇了這些技術挑戰,因為與傳統的溶劑型塗料相比,高含水量配方會捕獲更多空氣。 2024年,BASF擴大了其南京工廠的添加劑生產,以供應水性消泡劑來應對這些挑戰。新興經濟體,特別是中國、印度和印度尼西亞,持續推動大規模住宅、交通走廊和工業園區建設,從而對能夠保持混凝土、金屬和複合材料基材光澤均勻性的高效消泡劑產生了持續的需求。
汽車塗料需求不斷成長
電動車 (EV) 平台、輕量化基材和多層塗層結構為泡棉控制帶來了新的挑戰。現代底漆和麵漆生產線高速運作,空氣分散不足會導致諸如凹坑、針孔和氣泡等缺陷。 Allnex 的溶劑型消泡劑 ADDITOL VXL 4951 N 展示了目前市場上的消泡塗料添加劑,該添加劑能夠將表面張力控制在狹窄的範圍內,從而避免霧狀缺陷,同時避免矽衍生的印刷轉移風險。在電池外殼、馬達組件和電極漿料等領域,一些新興的細分市場正在湧現,這些市場對電壓敏感區域需要無矽配方。這促使原始設備製造商 (OEM) 與能夠確保產品潔淨度的添加劑供應商簽訂長期供應協議。
矽油價格波動
薄型化的供應鏈、更高的純度標準以及高能耗的合成過程導致矽油成本持續上漲,令依賴矽油作為高效消泡劑基礎原料的配方生產商感到擔憂。尤其是在東南亞,利潤微薄的塗料生產商正轉向更便宜的礦物油和聚合物替代品,即使這意味著性能上的妥協。 BYK 的無矽產品 BYK-1642 既滿足了這些注重成本的客戶的需求,也為添加劑供應商提供了一種應對價格上漲的有效途徑。
細分市場分析
至2025年,水性化學產品將佔消泡塗料添加劑市場59.74%的佔有率,預計到2031年將以5.18%的複合年成長率成長,這主要得益於混合商致力於研發符合VOC法規的產品結構。矽油乳液仍然是領先的產品類別,即使在添加量低至0.2%或更低的情況下,也具有快速消除微氣泡和極低表面缺陷風險的特性。同時,對「無矽油」標籤的需求不斷成長,也帶動了對植物油衍生聚合物微乳液的需求。 Allnex公司的生物基產品ADDITOL VXW 4926正是這一趨勢的例證,它在實現與矽油乳液相當的動態表面張力控制的同時,不會引發針對敏感物質的審查。
在極端潮濕環境或高溫固化製程中,當水成為問題時,溶劑型產品仍被使用。對於船舶面漆、化工廠內襯以及特殊重塗的油脂管線,高閃點載體與能夠耐受高達 200 度C固化工藝的矽酮-聚丙烯酸酯消泡劑的組合仍然是首選。粉末型消泡劑,例如 BYK-1693 SD,滿足了客戶對無 VOC、零流變粉末塗料的需求。這些顆粒含有 54% 的生物碳,顯示消泡塗料添加劑市場如何在不影響效果的前提下,平衡永續性和製程便利性。
區域分析
預計到2025年,亞太地區將佔據全球消泡塗料添加劑市場44.10%的佔有率,主要得益於中國、印度和東協地區不斷擴大的建築項目以及汽車組裝廠的集中。該地區5.03%的複合年成長率反映了政府資助的智慧城市項目、新建地鐵網路以及電動車強制生產的大力推進。跨國製造商正在部署一體化工廠和本地合資企業,以降低物流成本並滿足各國特定的合規審計要求。
聯邦政府的基礎設施現代化、對電池工廠的投資以及強勁的住宅需求,使得北美塗料工廠幾乎滿載運作。針對全氟烷基和多氟烷基物質(PFAS)的監管壓力,正推動消泡劑從含氟產品轉向矽基和生物基產品,促使塗料生產商快速認證新產品。歐洲也出現了類似的監管趨勢,但由於更多環狀矽酮將於2025年被列入REACH法規候選清單,情況變得更加複雜,這促使添加劑供應商向市場推出不含PFAS和環狀矽氧烷的產品系列。
儘管南美洲、中東和非洲的市場規模仍然相對較小,但它們在消泡塗料添加劑市場中所佔的佔有率卻不斷成長。巴西的建築獎勵策略和沙烏地阿拉伯的大規模項目正在推動對高水性塗料的需求,因為這類塗料無法承受泡沫的產生。這些地區的塗料製造商通常會引進歐洲技術,並從全球大型公司採購消泡劑,直到本地生產能力成熟。儘管這一趨勢的起點較低,但其成長勢頭正處於高於平均水平的水平。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 建築塗料需求不斷成長
- 汽車塗料需求不斷成長
- 木材和家俱生產擴張
- 數位裝飾印刷生產線的激增
- 在工業應用的擴展應用
- 市場限制因素
- 矽油價格波動
- 紫外粉塗料的興起
- 食品接觸過程中滲出和轉移的標準更加嚴格。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 產品類型
- 水基系統
- 矽
- 乳液
- 聚合物
- 粉末
- 其他
- 溶劑型體系
- 聚合物
- 矽
- 水基系統
- 終端用戶產業
- 建築/施工
- 汽車和交通運輸
- 木材/家具
- 其他終端用戶產業(一般工業、OEM 等)
- 地區
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Allnex GMBH
- ALTANA
- Arkema
- Ashland
- BASF
- CLARIANT
- Dow
- Eastman Chemical Company
- Elementis PLC
- Elkem ASA
- Evonik Industries AG
- Momentive
- Munzing Corporation
- Shin-Etsu Chemical Co., Ltd.
- Solvay
- Wacker Chemie AG
第7章 市場機會與未來展望
According to Mordor Intelligence, defoaming coating additive market size market size in 2026 is estimated at USD 2.12 billion, growing from 2025 value of USD 2.03 billion with 2031 projections showing USD 2.61 billion, growing at 4.32% CAGR over 2026-2031.
This report is Segmented by Product Type (Water-Based Systems and Solvent-Based Systems), End-User Industry (Building and Construction, Automotive and Transportation, Wood and Furniture, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Defoaming Coating Additive Market Trends and Insights
Growing Demand from Construction Coatings
Rapid urbanization and infrastructure renewal elevate foam-control requirements for architectural finishes worldwide. Spray-applied, high-build systems are now commonplace on commercial facades and civil structures, yet even micro-air entrapment compromises adhesion and long-term durability. The push toward low-VOC paints heightens the technical challenge because water-rich formulations entrain more air than solventborne predecessors. BASF boosted its Nanjing additives output in 2024 to supply water-compatible defoamers that reconcile these issues. Emerging economies, led by China, India, and Indonesia, continue to commission mass housing, transport corridors, and industrial parks, embedding sustained pull for high-efficiency defoamers able to maintain gloss uniformity on concrete, metal, and composite substrates.
Increasing Requirement in Automotive Coatings
Electric-vehicle platforms, lightweight substrates, and multi-layer paint stacks create fresh foam-control pain points. Modern primer-surfacer lines run at elevated line speeds, where improperly dispersed air causes crater, pinhole, and blister defects. Allnex's solventborne ADDITOL VXL 4951 N illustrates how the defoaming coating additive market now delivers narrow-range surface-tension control to avoid haze without silicone print-transfer risks. Battery housings, e-motor components, and electrode slurries present additional niches that require zero-silicone formulas for voltage-sensitive zones, nudging OEMs to lock in long-term supply contracts with additive vendors able to certify cleanliness.
Silicone-Oil Price Volatility
Slim supply chains, purity specifications and energy-intensive synthesis periodically lift silicone-oil costs, unsettling formulators who rely on the material as the cornerstone of high-efficiency defoamers. Coating makers operating on narrow margins, particularly in Southeast Asia, pivot toward lower-priced mineral-oil or polymer alternatives despite minor performance trade-offs. BYK's silicone-free BYK-1642 caters to this budget-centric cohort while giving additive suppliers a hedge against price spikes.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Wood and Furniture Production
- Surge in Digital Decor Printing Lines
- Stricter Food-Contact Migration Limits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Water-based chemistries secured 59.74% of the defoaming coating additive market in 2025 and are forecast to advance at 5.18% CAGR through 2031 as formulators pursue VOC-compliant architectures. Silicone emulsions remain the workhorse class, combining rapid micro-bubble rupture with negligible surface-defect risk even at dosages below 0.2%. Meanwhile, the push for silicone-free labelling stimulates polymer microemulsions derived from vegetable oils. Allnex's bio-based ADDITOL VXW 4926 exemplifies this direction, offering equivalent dynamic surface-tension control without triggering substance-of-concern audits.
Solvent-based packages persist where extreme humidity resistance or high-temperature bake cycles make water a liability. Marine topcoats, chemical-plant linings, and specialty refinish fat lines still pick high-flashpoint carriers paired with silicone-polyacrylate defoamers that withstand 200 °C cure schedules. Powder-format defoamers, such as BYK-1693 SD, serve customers migrating to VOC-free zero-flow powder paints. These granules contain 54% bio-carbon, illustrate how the defoaming coating additive market blends sustainability and process convenience without sacrificing efficacy.
Complete Report Scope:
- Product Type
- Water-based Systems
- Silicone
- Emulsion
- Polymer
- Powder
- Others
- Solvent-based Systems
- Polymer
- Silicone
- Water-based Systems
- End-user Industry
- Building and Construction
- Automotive and Transportation
- Wood and Furniture
- Other End-user Industries (General Industrial and OEM, etc.)
- Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific captured 44.10% of the defoaming coating additive market in 2025 on the back of construction expansions and vehicle assembly clusters in China, India, and the ASEAN bloc. Regional CAGR of 5.03% reflects government-funded smart-city projects, new metro corridors, and aggressive EV production mandates. Multinational producers operate integrated Verbund sites and local joint ventures to curtail logistics costs and satisfy country-specific compliance audits.
Federal infrastructure modernization, battery-plant investments, and resilient housing demand keep coatings factories running near capacity in North America. Regulatory pressure against PFAS drives transfer from fluorinated defoamers to silicone or bio-based families, prompting formulators to fast-track new product qualifications. Europe maintains a similar regulatory tone, further complicated by REACH candidate-listing of additional cyclic silicones in 2025, spurring additive vendors to market PFAS-free, cyclic-siloxane-free lines.
South America, and Middle-East and Africa collectively account for a smaller yet rising slice of the defoaming coating additive market. Brazil's construction stimulus and Saudi Arabia's giga-projects draw in advanced waterborne coatings that cannot tolerate foam. Coating producers in these regions often license European technology, integrating defoamers sourced from global majors until local capacity matures. These dynamics translate into above-average growth trajectories, albeit from a comparatively low base.
- Allnex GMBH
- ALTANA
- Arkema
- Ashland
- BASF
- CLARIANT
- Dow
- Eastman Chemical Company
- Elementis PLC
- Elkem ASA
- Evonik Industries AG
- Momentive
- Munzing Corporation
- Shin-Etsu Chemical Co., Ltd.
- Solvay
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand from Construction Coatings
- 4.2.2 Increasing Requirement in Automotive Coatings
- 4.2.3 Expansion of Wood and Furniture Production
- 4.2.4 Surge in Digital Decor Printing Lines
- 4.2.5 Rising Usage in Industrial Applications
- 4.3 Market Restraints
- 4.3.1 Silicone-Oil Price Volatility
- 4.3.2 Rise of UV-Powder Coatings
- 4.3.3 Stricter Food-Contact Migration Limits
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 Product Type
- 5.1.1 Water-based Systems
- 5.1.1.1 Silicone
- 5.1.1.2 Emulsion
- 5.1.1.3 Polymer
- 5.1.1.4 Powder
- 5.1.1.5 Others
- 5.1.2 Solvent-based Systems
- 5.1.2.1 Polymer
- 5.1.2.2 Silicone
- 5.1.1 Water-based Systems
- 5.2 End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Automotive and Transportation
- 5.2.3 Wood and Furniture
- 5.2.4 Other End-user Industries (General Industrial and OEM, etc.)
- 5.3 Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 Japan
- 5.3.1.3 India
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Allnex GMBH
- 6.4.2 ALTANA
- 6.4.3 Arkema
- 6.4.4 Ashland
- 6.4.5 BASF
- 6.4.6 CLARIANT
- 6.4.7 Dow
- 6.4.8 Eastman Chemical Company
- 6.4.9 Elementis PLC
- 6.4.10 Elkem ASA
- 6.4.11 Evonik Industries AG
- 6.4.12 Momentive
- 6.4.13 Munzing Corporation
- 6.4.14 Shin-Etsu Chemical Co., Ltd.
- 6.4.15 Solvay
- 6.4.16 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and unmet-need assessment

 丙烯酸鏈增稠劑市場:全球市場預測,2026-2032年
 全球塗料添加劑市場
 北美油漆和塗料添加劑:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026年全球阻燃塗料添加劑市場報告
 水性塗料添加劑市場規模、佔有率和成長分析:按產品類型、化學類型、功能、應用、最終用途產業和地區分類-2026-2033年產業預測消泡塗料添加劑市場:依原料類型、形態、功能、最終用途及通路分類-2026-2032年全球市場預測
 水性塗料添加劑市場:商業機會、成長要素、產業趨勢分析及 2026-2035 年預測。
 塗料助劑市場規模、佔有率和成長分析:按化學類型、應用類型、最終用途產業、配方類型和地區分類 - 2026-2033 年產業預測
 環保塗料添加劑市場分析與預測(至2035年):類型、產品、應用、技術、最終用戶、成分、形態、材料類型、工藝
 揮發性有機化合物 (VOC) 市場規模、佔有率和成長分析(按化合物類型、應用、最終用途和地區分類)—2026-2033 年行業預測