


 |
市場調查報告書
商品編碼
2045715
水性塗料添加劑市場:商業機會、成長要素、產業趨勢分析及 2026-2035 年預測。Waterborne Coating Additives Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球水性塗料添加劑市場規模預估為51億美元,預計2035年將以5.9%的複合年成長率成長至91億美元。
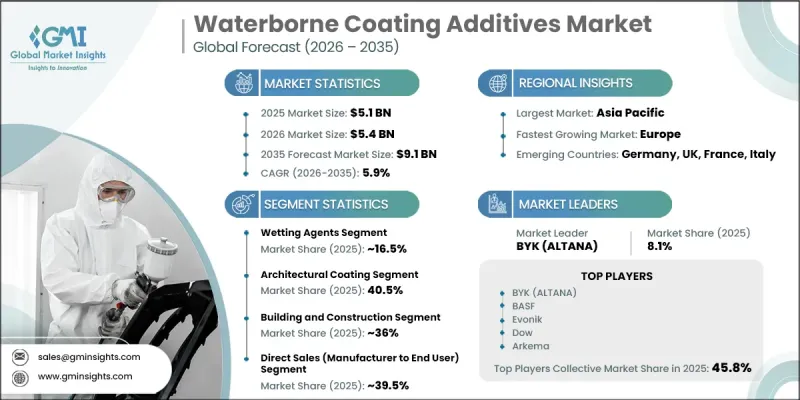
隨著製造商擴大採用水性塗料技術以滿足不斷變化的環境和性能要求,該行業持續擴張。水性塗料添加劑由特殊的化學配方組成,可改善塗料的附著力、表面耐久性、耐候性和施工效率等性能。這些添加劑在最佳化塗料配方方面發揮著至關重要的作用,從而確保在各種終端應用中獲得一致的效果。全球對永續性和減排的排放關注正在加速向低VOC塗料系統的轉型,直接推動了對這些添加劑的需求。監管壓力以及消費者和產業日益增強的環保意識進一步推動了這項轉型。此外,塗料科學和材料工程的不斷進步也促進了高性能添加劑解決方案的開發。在建築、運輸和工業製造等領域的廣泛應用進一步增強了水性塗料添加劑市場的長期成長前景。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 51億美元 |
| 預計金額 | 91億美元 |
| 複合年成長率 | 5.9% |
截至 2025 年,潤濕劑市佔率將達到 16.5%,預計到 2035 年將以 6.3% 的複合年成長率成長。這些添加劑在改善塗料的著色性和表面相互作用方面發揮著至關重要的作用,從而實現均勻塗覆並提高在各種基材上的附著力。
預計到 2025 年,建築和施工領域將佔 36% 的市場佔有率,並從 2026 年到 2035 年以 5.9% 的複合年成長率成長。該領域的需求是由住宅、商業和基礎設施開發項目對高耐用性、高性能和符合環保標準的塗料解決方案的需求所驅動的。
預計到2025年,北美水性塗料添加劑市場佔有率將達到32.5%,主要得益於嚴格的環境法規和對永續產品的大力推廣。該地區擁有高度發展的塗料產業,且各領域的需求穩定,從中受益匪淺。配方技術的持續創新,尤其是在減少排放和提升性能方面的創新,進一步推動了該地區市場的成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章:行業洞察
- 工業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特的分析
- PESTLE分析
- 價格趨勢
- 按地區
- 按類型
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新技術
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續發展計劃
- 減少廢棄物策略
- 生產中的能源效率
- 環保舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 保濕劑
- 分散劑
- 消泡劑
- 蠟添加劑
- 流動性添加劑
- 流變改性劑
- 表面控制添加劑
- 脫氣劑
- 其他
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 建築塗料
- 工業塗料
- 木器漆
- 保護塗層
- 其他
第7章 市場估計與預測:依最終用戶產業分類,2022-2035年
- 建築/施工
- 車
- 包裝
- 其他
第8章 市場估算與預測:依通路分類,2022-2035年
- 直銷(從製造商到最終用戶)
- 銷售代理商和批發商
- 電子商務平台
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 阿拉伯聯合大公國
- 其他中東和非洲國家
第10章:公司簡介
- Allnex
- Arkema
- Ashland
- BASF
- Borchers(Milliken)
- BYK(ALTANA)
- Clariant
- Dow
- Elementis
- Evonik
- Lamberti
- Lubrizol
- Michelman
- Munzing Chemie
- Syensqo
The Global Waterborne Coating Additives Market was valued at USD 5.1 billion in 2025 and is estimated to grow at a CAGR of 5.9% to reach USD 9.1 billion by 2035.
The industry continues to expand as manufacturers increasingly adopt water-based coating technologies to meet evolving environmental and performance requirements. Waterborne coating additives consist of specialized chemical formulations that enhance coating characteristics such as adhesion strength, surface durability, weather resistance, and application efficiency. These additives play a critical role in optimizing coating formulations to achieve consistent results across various end-use applications. Rising global emphasis on sustainability and reduced emissions is accelerating the transition toward low-VOC coating systems, which directly supports demand for these additives. Regulatory pressure, combined with heightened environmental awareness among consumers and industries, is further driving this shift. Additionally, ongoing advancements in coating science and material engineering are enabling the development of high-performance additive solutions. Expanding use across sectors such as construction, transportation, and industrial manufacturing continues to reinforce the long-term growth outlook for the waterborne coating additives market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.1 Billion |
| Forecast Value | $9.1 Billion |
| CAGR | 5.9% |
The wetting agents segment accounted for a share of 16.5% in 2025 and is expected to grow at a CAGR of 6.3% through 2035. These additives play a vital role in improving coating spreadability and surface interaction, allowing coatings to achieve uniform application and enhanced adhesion across different substrates.
The building and construction segment held a 36% share in 2025 and is projected to grow at a CAGR of 5.9% during 2026-2035. Demand within this segment is driven by the need for durable, high-performance, and environmentally compliant coating solutions used in residential, commercial, and infrastructure development projects.
North America Waterborne Coating Additives Market accounted for 32.5% share in 2025, supported by strict environmental regulations and a strong focus on sustainable product adoption. The region benefits from a well-developed coatings industry and steady demand across multiple sectors. Continuous innovation in formulation technologies, particularly those aimed at reducing emissions and improving performance, is further strengthening market growth in this region.
Key companies operating in the Global Waterborne Coating Additives Market include BASF, Dow, Arkema, Evonik, Clariant, Ashland, Allnex, BYK (ALTANA), Elementis, Lubrizol, Michelman, Munzing Chemie, Lamberti, Syensqo, and Borchers (Milliken). Companies in the waterborne coating additives market are adopting strategic approaches to strengthen their market position and expand their global reach. They are increasing investments in research and development to introduce advanced additive formulations with enhanced performance and environmental benefits. Strategic collaborations and partnerships are being leveraged to accelerate innovation and access new application areas. Expansion of production capacities and geographic presence is helping companies meet rising demand and improve supply chain efficiency. Firms are also focusing on sustainable manufacturing practices and compliance with regulatory standards to align with market expectations. Additionally, continuous product innovation, combined with customer-centric solutions and technical support, is enabling companies to differentiate their offerings and maintain a competitive edge in the evolving coatings industry.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product type
- 2.2.3 Application
- 2.2.4 End user industry
- 2.2.5 Distribution channel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By type
- 3.8 Future market trends
- 3.9 Technology and Innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Product Type, 2022-2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Wetting agents
- 5.3 Dispersing agents
- 5.4 Defoamers
- 5.5 Wax additives
- 5.6 Flow additives
- 5.7 Rheology modifiers
- 5.8 Surface control additives
- 5.9 Deaerators
- 5.10 Others
Chapter 6 Market Estimates and Forecast, By Application, 2022-2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Architectural coatings
- 6.3 Industrial coatings
- 6.4 Wood coatings
- 6.5 Protective coatings
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By End User Industry, 2022-2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Building & construction
- 7.3 Automotive
- 7.4 Packaging
- 7.5 Other
Chapter 8 Market Estimates and Forecast, By Distribution Channel, 2022-2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 Direct sales (manufacturer to end user)
- 8.3 Distributors/wholesalers
- 8.4 E-commerce platforms
- 8.5 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022-2035 (USD Billion) (Kilo Tons)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 Saudi Arabia
- 9.6.2 South Africa
- 9.6.3 UAE
- 9.6.4 Rest of Middle East and Africa
Chapter 10 Company Profiles
- 10.1 Allnex
- 10.2 Arkema
- 10.3 Ashland
- 10.4 BASF
- 10.5 Borchers (Milliken)
- 10.6 BYK (ALTANA)
- 10.7 Clariant
- 10.8 Dow
- 10.9 Elementis
- 10.10 Evonik
- 10.11 Lamberti
- 10.12 Lubrizol
- 10.13 Michelman
- 10.14 Munzing Chemie
- 10.15 Syensqo

 丙烯酸鏈增稠劑市場:全球市場預測,2026-2032年
 全球塗料添加劑市場
 北美油漆和塗料添加劑:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026年全球阻燃塗料添加劑市場報告消泡塗料添加劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 水性塗料添加劑市場規模、佔有率和成長分析:按產品類型、化學類型、功能、應用、最終用途產業和地區分類-2026-2033年產業預測消泡塗料添加劑市場:依原料類型、形態、功能、最終用途及通路分類-2026-2032年全球市場預測
 塗料助劑市場規模、佔有率和成長分析:按化學類型、應用類型、最終用途產業、配方類型和地區分類 - 2026-2033 年產業預測
 環保塗料添加劑市場分析與預測(至2035年):類型、產品、應用、技術、最終用戶、成分、形態、材料類型、工藝
 揮發性有機化合物 (VOC) 市場規模、佔有率和成長分析(按化合物類型、應用、最終用途和地區分類)—2026-2033 年行業預測