


 |
市場調查報告書
商品編碼
2066586
聚丙烯包裝薄膜:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Polypropylene Packaging Films - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,聚丙烯包裝薄膜市場預計到 2026 年價值 247 億美元,高於 2025 年的 236.7 億美元,預計到 2031 年將達到 305.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.34%。
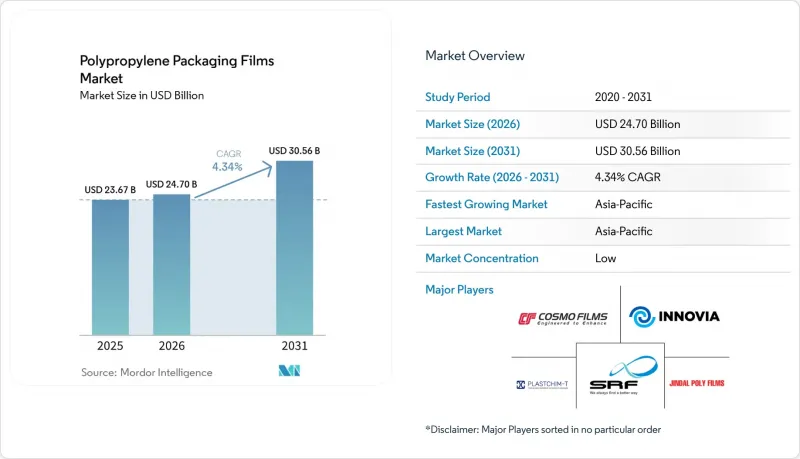
本報告按薄膜類型(如雙軸延伸聚丙烯(BOPP) 薄膜)、包裝形式(如包裝膜和重疊膜、標籤和感壓膠帶、袋子和包裝袋)、最終用途行業(如食品、飲料、藥品和醫療保健)以及地區(北美、歐洲、亞太地區、南美、中東和非洲)進行分類。
全球聚丙烯包裝薄膜市場趨勢與洞察
從硬質塑膠包裝向軟包裝永續轉型
與硬質塑膠相比,軟性聚丙烯薄膜可將包裝重量減輕高達 75%,幫助品牌商降低運輸排放氣體和材料成本。 Klockner Pentaplast 的「kp FlexiFlow」系列採用可回收的枕式包裝結構,其聚丙烯含量超過 93%,性能與傳統包裝相當,同時支援循環經濟。跨國公司正在採用填充用的包裝袋來包裝家居護理和個人保健產品,從而在生產者延伸責任 (EPR) 法規下降低源頭減量成本。薄膜製造商正致力於在不影響抗穿刺性的前提下,降低薄膜厚度並提高再生消費樹脂的比例,從而鞏固聚丙烯作為電子商務和零售通路輕量化包裝材料的地位。
品牌擁有者對單一材料、可回收層壓板的需求。
DNP 的聚丙烯基單材料複合材料符合 CEFLEX 設計指南,可實現高速成型、填充和密封 (FFS) 工藝,並可整合到現有的回收系統中。隨著歐洲包裝和包裝廢棄物法規的加速實施,Saica Flex 開發了 100% 可回收的解決方案,其中包含 5% 的經認證的消費品衍生廢料。阻隔塗層(例如 ORMOCER)和新型丙烯酸化學技術的進步,實現了低於 0.1 cm³/m²*day*bar 的氧氣透過率,從而在滿足保存期限要求的同時兼顧了可回收性。品牌所有者願意接受略微增加的成本,以履行其到 2030 年實現循環經濟的承諾,這正在推動混合材料箔複合材料的快速替代方案。
丙烯和石腦油原料價格波動
2025年初,由於煉油廠停產,供應趨緊,導致聚合級丙烯價格每磅上漲4-5美分,擠壓了加工商的利潤空間。南亞拉菲草價格上漲至每噸970-990美元,反映出地緣政治因素對原油基準價格的影響。薄膜生產商難以將額外成本轉嫁給商品化的零食包裝薄膜,一些區域包裝商正在嘗試波動性較小的聚乙烯薄膜。持續的不確定性使年度供應競標變得更加複雜,也讓企業對投資新的拉伸生產線猶豫不決。
細分市場分析
預計到2025年,雙向拉伸聚丙烯薄膜(BOPP)將引領聚丙烯包裝薄膜市場,佔據65.58%的市佔率。這反映了BOPP在零食、烘焙產品和菸草製品重疊包裝領域的廣泛應用。塗覆丙烯酸或聚對苯二甲酸乙二醇酯(PVDC)層的BOPP薄膜在維持低密度優勢的同時,也能延長糖果甜點的保存期限。 Cosmo Films公司年產能達19.6萬噸,為其全球分銷提供了有力支撐,並增強了BOPP的供應穩定性。此外,東南亞新生產線的投產也降低了運往價格敏感的非洲市場的交付成本。
預計CPP(複合年成長率)將達到6.87%,成為複合年成長率最高的材料,主要得益於殺菌袋和金屬塗層沉澱包裝市場的成長。三井物產的RXC-22鑄膜可在較低溫度下進行封口,進而降低高速泡棉填充封口(FFS)機的能耗。特種CPP在醫療包裝領域具有競爭力,因為該領域對透明度、耐化學性和耐伽馬射線滅菌性要求極高。隨著對便於回收的單一材料複合包裝袋的需求不斷成長,CPP聚丙烯包裝薄膜市場規模預計將進一步擴大。其他一些細分市場的產品,例如用於農產品的透氣微孔薄膜,透過滿足特定的水分和氣體交換需求,也創造了額外的收入。
區域分析
預計到2025年,亞太地區將佔全球銷售額的43.71%,並在2031年之前以6.23%的複合年成長率成長。中國聚丙烯出口量預計將達到260萬噸,為薄膜樹脂的充足供應提供保障。印尼國內需求已達520萬噸,超過其240萬噸的國內產能,儘管對區域供應商徵收了反傾銷稅,但仍需進口。越南龍山裂解裝置將於2025年下半年運作,屆時每年將額外提供40萬噸聚丙烯,緩解供不應求,並促進區域下游加工商的發展。具有成本競爭力的勞動力和不斷壯大的中產階級,支撐著日常消費品、醫藥和電子產品供應鏈的強勁需求。
儘管產量成長緩慢,歐洲仍保持技術領先地位。根據生產者延伸責任制(EPR),費用如今根據可回收性而有所不同,迫使品牌商轉向單一材料聚丙烯解決方案。即將實施的碳邊境調節機制(CBAM)可能會對進口薄膜施加報告要求和隱性碳成本,從而削弱東南亞的價格優勢。歐洲加工商正在投資建造先進的脫墨和溶劑型回收工廠,以實現材料循環利用;同時,英力士(Ineos)正在法國克拉克(Cracker)擴大再生塑膠的生產規模,以滿足歐盟《聚丙烯廢棄物法規》(PPWR)的要求。
北美受益於高食品安全標準和高電子商務滲透率,但也必須應對與原物料價格相關的成本波動。 PureCycle位於俄亥俄州的工廠目前每年生產1.07億磅超高純度再生聚丙烯,供應給需要符合FDA標準的再生材料的加工商。 2021年,美國聚丙烯進口總額達7.892億美元,凸顯了美國對海外單體的依賴,因為國內裂解企業優先生產聚乙烯衍生物。隨著各州法規制定軟包裝的再生材料含量標準,化學回收試驗生產線的投資正在加速成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 從硬質包裝到軟質包裝的永續轉型
- 品牌擁有者對單一材料、可回收層壓板的需求。
- 用於蒸餾的CPP可作為多層高阻隔結構的替代方案
- 電子商務的快速發展帶動了對高透明度重疊薄膜的需求。
- 東南亞產能的快速擴張導致底片價格下降。
- 化學回收製聚丙烯樹脂的商業化
- 市場限制因素
- 丙烯和石腦油原料價格波動
- PET和PE單材料阻隔薄膜的替代品供應量增加。
- 碳邊境調節關稅導致貿易流量中斷
- 遵守生產者延伸責任制(EPR)的成本
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
第5章 市場規模與成長預測
- 按膠片類型
- 雙軸延伸聚丙烯(BOPP)薄膜
- 塗層 BOPP(PVDC、丙烯酸、EVOH)
- 未塗層雙向拉伸聚丙烯薄膜
- 氯化聚丙烯(CPP)薄膜
- 通用 CPP
- 用於蒸餾的CPP
- 金屬化CPP
- 其他聚丙烯(PP)包裝薄膜
- 雙軸延伸聚丙烯(BOPP)薄膜
- 按包裝類型
- 包裝和重疊
- 標籤和感壓膠帶
- 袋子和小袋
- 閱讀薄膜和流動包裝薄膜
- 帶狀包裝
- 產業最終用途
- 食物
- 麵包糖果甜點
- 零食和早餐用麥片穀類
- 生鮮食品
- 肉類、雞肉、魚貝類
- 乳製品
- 飲料
- 非酒精性
- 瓶裝水
- 碳酸飲料
- 果汁
- 其他非酒精飲料
- 酒精飲料
- 啤酒
- 烈酒
- 其他酒精飲料
- 非酒精性
- 藥品和醫療保健
- 個人護理化妝品
- 產業
- 其他終端用戶產業
- 食物
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 肯亞
- 其他非洲國家
- 中東
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor Plc
- Jindal Poly Films Ltd
- Innovia Films
- Cosmo Films Ltd
- Taghleef Industries LLC
- UFlex Ltd
- Polyplex Corporation Ltd
- SRF Ltd
- Plastchim-T
- Toray Plastics(America)Inc.
- ProAmpac LLC
- Inteplast Group
- Oben Holding Group
- Profol GmbH
- Treofan GmbH
- Vibac Group
- Chiripal Poly Films
- Polinas
- Stenta Films
第7章 市場機會與未來展望
According to Mordor Intelligence, polypropylene packaging films market size in 2026 is estimated at USD 24.7 billion, growing from 2025 value of USD 23.67 billion with 2031 projections showing USD 30.56 billion, growing at 4.34% CAGR over 2026-2031.
This report is Segmented by Film Type (Biaxially Oriented Polypropylene (BOPP) Film and More), Packaging Format (Wraps and Over-Wraps, Labels and Pressure-Sensitive Tapes, Bags and Pouches and More), End-Use Industry ( Food, Beverage, Pharmaceutical and Healthcare and More) and Geography (North America, Europe, Asia-Pacific, South America and Middle East and Africa)
Global Polypropylene Packaging Films Market Trends and Insights
Sustainable Shift from Rigid to Flexible Formats
Reducing package weight by as much as 75% versus rigid plastics, flexible polypropylene films help brand owners curb freight emissions and material costs. Klockner Pentaplast's kp FlexiFlow range delivers recyclable flow-wrap structures containing more than 93% polypropylene, illustrating performance parity with legacy formats while offering circularity. Multinationals adopt refill pouches for home-care and personal-care goods, lowering source-reduction fees under Extended Producer Responsibility rules. Film producers leverage downgauging and higher post-consumer-recycled resin loads without sacrificing puncture strength, solidifying polypropylene's role as a lightweight alternative across e-commerce and retail channels.
Brand Owner Demand for Mono-Material Recycle-Ready Laminates
DNP's polypropylene-based mono-material laminates meet CEFLEX design guidelines, allowing high-speed form-fill-seal operations while entering existing recycling streams. European Packaging and Packaging Waste Regulation targets accelerate adoption, prompting Saica Flex to develop 100% recyclable solutions that incorporate 5% certified post-consumer content. Barrier-coating advances such as ORMOCER and new acrylic chemistries achieve oxygen transmission rates below 0.1 cm3/m2*day*bar, aligning shelf-life demands with recyclability. Brand owners accept small cost premiums to reach 2030 circularity pledges, spurring rapid substitution of mixed-material foil laminates.
Volatility in Propylene and Naphtha Feedstock Prices
Polymer-grade propylene rose 4-5 cents / lb in early 2025 after refinery closures tightened supply, squeezing converter margins. South Asian raffia grades climbed to USD 970-990 / t, reflecting geopolitical pressures on crude benchmarks. Film makers struggle to pass through surcharges in commoditized snack wraps, prompting some regional packers to trial less volatile polyethylene films. Persistent uncertainty complicates annual supply tenders and deters capital spending on new orientation lines.
Other drivers and restraints analyzed in the detailed report include:
- Retort-Grade CPP Replacing Multilayer High-Barrier Structures
- E-commerce Boom Driving High-Clarity Over-Wrap Films
- Growing PET and PE Mono-Material Barrier Film Substitutes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
BOPP led the polypropylene packaging films market with 65.58% share in 2025, reflecting broad adoption in snack, bakery, and tobacco over-wraps. Coated BOPP grades with acrylic or PVDC layers extend shelf life in confectionery while retaining low density advantages. Cosmo Films operates 196,000 t / y capacity that supports global distribution, reinforcing BOPP supply security. Volume also flows from new Southeast Asian lines that lower delivered costs into price-sensitive African markets.
CPP posted the quickest 6.87% CAGR forecast, propelled by retort pouches and metallized snack wraps. Mitsui's RXC-22 cast film seals at lower temperatures, trimming energy use on high-speed form-fill-seal machinery. Specialty CPP competes in medical packaging where clarity, chemical resistance, and gamma sterilization tolerance matter. The polypropylene packaging films market size for CPP is set to expand alongside demand for mono-material pouch laminates that facilitate recycling streams. Other niche grades, including breathable microporous films for produce, carve out incremental revenue by solving specific moisture and gas-exchange needs.
Geography Analysis
Asia-Pacific controlled 43.71% of global revenue in 2025 and is poised for a 6.23% CAGR through 2031. China's forecast 2.6 million-ton polypropylene export pool underpins ample film resin supply. Indonesia's national demand of 5.2 million t outstrips domestic capacity of 2.4 million t, necessitating imports even as anti-dumping duties target regional suppliers. Vietnam's Long Son cracker restart in late 2025 will add 400,000 t / y of polypropylene, narrowing deficits and supporting regional downstream processors. Cost-competitive labor and an expanding middle class sustain robust demand across FMCG, pharmaceutical, and electronics supply chains.
Europe remains a technology leader despite modest volume growth. Extended Producer Responsibility fees now vary by recyclability, nudging brands toward mono-material polypropylene solutions. The forthcoming Carbon Border Adjustment Mechanism may impose reporting obligations and implicit carbon costs on imported films, potentially eroding Southeast Asian price advantages. European converters invest in advanced de-inking and solvent-based recycling plants to close material loops, while Ineos ramps recycled-plastic output at its French cracker to comply with EU PPWR mandates.
North America benefits from high food-safety standards and deep e-commerce penetration but battles feedstock-linked cost swings. PureCycle's Ohio plant now produces 107 million lb / y of ultra-pure recycled polypropylene, supplying converters that need FDA-compliant recyclate. US polypropylene imports totaled USD 789.2 million in 2021, revealing reliance on overseas monomer when domestic crackers prioritize polyethylene derivatives. Investment in chemical recycling pilot lines accelerates as state legislation sets recycled-content thresholds for flexible packaging.
- Amcor Plc
- Jindal Poly Films Ltd
- Innovia Films
- Cosmo Films Ltd
- Taghleef Industries LLC
- UFlex Ltd
- Polyplex Corporation Ltd
- SRF Ltd
- Plastchim-T
- Toray Plastics (America) Inc.
- ProAmpac LLC
- Inteplast Group
- Oben Holding Group
- Profol GmbH
- Treofan GmbH
- Vibac Group
- Chiripal Poly Films
- Polinas
- Stenta Films
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Sustainable shift from rigid to flexible formats
- 4.2.2 Brand owner demand for mono-material recycle-ready laminates
- 4.2.3 Retort-grade CPP replacing multilayer high-barrier structures
- 4.2.4 E-commerce boom driving high-clarity over-wrap films
- 4.2.5 Rapid capacity additions in Southeast Asia lowering film prices
- 4.2.6 Chemical-recycling derived PP resin commercialization
- 4.3 Market Restraints
- 4.3.1 Volatility in propylene and naphtha feedstock prices
- 4.3.2 Growing PET and PE mono-material barrier film substitutes
- 4.3.3 Trade-flow disruptions from carbon-border-adjustment tariffs
- 4.3.4 Extended Producer Responsibility (EPR) compliance costs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Film Type
- 5.1.1 Biaxially Oriented Polypropylene (BOPP) Film
- 5.1.1.1 Coated BOPP (PVDC, Acrylic, EVOH)
- 5.1.1.2 Uncoated BOPP
- 5.1.2 Chlorinated Polypropylene (CPP) Film
- 5.1.2.1 General-purpose CPP
- 5.1.2.2 Retort-grade CPP
- 5.1.2.3 Metalized CPP
- 5.1.3 Other Polypropylene (PP) Packaging Films
- 5.1.1 Biaxially Oriented Polypropylene (BOPP) Film
- 5.2 By Packaging Format
- 5.2.1 Wraps and Over-wraps
- 5.2.2 Labels and Pressure-sensitive Tapes
- 5.2.3 Bags and Pouches
- 5.2.4 Lidding and Flow-wrap Films
- 5.2.5 Blister and Strip Packs
- 5.3 By End-use Industry
- 5.3.1 Food
- 5.3.1.1 Bakery and Confectionery
- 5.3.1.2 Snacks and Breakfast Cereals
- 5.3.1.3 Fresh Produce
- 5.3.1.4 Meat, Poultry and Seafood
- 5.3.1.5 Dairy Products
- 5.3.2 Beverage
- 5.3.2.1 Non-Alcoholic
- 5.3.2.1.1 Bottled Water
- 5.3.2.1.2 Carbonated Drinks
- 5.3.2.1.3 Juices
- 5.3.2.1.4 Other Non-Alcoholic Beverages
- 5.3.2.2 Alcoholic
- 5.3.2.2.1 Beer
- 5.3.2.2.2 Spirits
- 5.3.2.2.3 Other Alcoholic Beverages
- 5.3.2.1 Non-Alcoholic
- 5.3.3 Pharmaceutical and Healthcare
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Industrial
- 5.3.6 Other End-use Industry
- 5.3.1 Food
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 Middle East
- 5.4.4.1.1 Saudi Arabia
- 5.4.4.1.2 United Arab Emirates
- 5.4.4.1.3 Turkey
- 5.4.4.1.4 Rest of Middle East
- 5.4.4.2 Africa
- 5.4.4.2.1 South Africa
- 5.4.4.2.2 Kenya
- 5.4.4.2.3 Rest of Africa
- 5.4.4.1 Middle East
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor Plc
- 6.4.2 Jindal Poly Films Ltd
- 6.4.3 Innovia Films
- 6.4.4 Cosmo Films Ltd
- 6.4.5 Taghleef Industries LLC
- 6.4.6 UFlex Ltd
- 6.4.7 Polyplex Corporation Ltd
- 6.4.8 SRF Ltd
- 6.4.9 Plastchim-T
- 6.4.10 Toray Plastics (America) Inc.
- 6.4.11 ProAmpac LLC
- 6.4.12 Inteplast Group
- 6.4.13 Oben Holding Group
- 6.4.14 Profol GmbH
- 6.4.15 Treofan GmbH
- 6.4.16 Vibac Group
- 6.4.17 Chiripal Poly Films
- 6.4.18 Polinas
- 6.4.19 Stenta Films
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 紙箱製造薄膜市場規模、佔有率和成長分析:按薄膜類型、厚度、應用、終端用戶產業、分銷管道和地區分類-產業預測(2026-2033 年)
 Polyvinylidene氯乙烯(PVDC)塗層薄膜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 蛋白質薄膜市場分析及預測(至2035年):類型、產品、技術、應用、形態、材料類型、過程、最終用戶、功能
 全球剝離袋包裝市場規模、佔有率、成長和行業分析:按材料類型、應用和地區分類,預測至2034年
 包裝薄膜市場:依材料、結構、製造技術、包裝形式及應用分類-2026-2032年全球市場預測
 纖維素薄膜市場:按類型、產品類型、應用、最終用途和地區分類高阻隔包裝薄膜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 包裝阻隔膜市場預測至2034年-按材料、包裝類型、最終用戶和地區分類的全球分析高阻隔包裝薄膜市場預測至2034年—按材料、包裝類型、技術、應用和地區分類的全球分析阻隔性軟包裝市場預測至2034年-按材料類型、阻隔類型、包裝形式、技術、最終用戶和地區分類的全球分析