


 |
市場調查報告書
商品編碼
2064407
油田設備租賃服務:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)Oilfield Equipment Rental Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
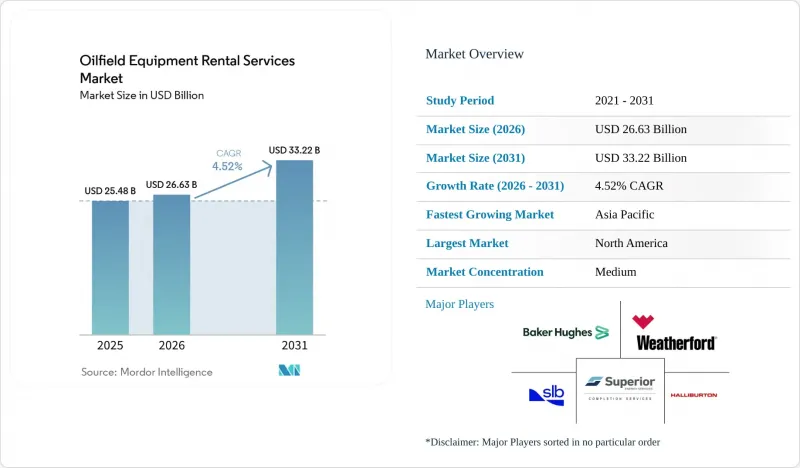
根據 Mordor Intelligence 預測,油田設備租賃服務市場規模將從 2025 年的 254.8 億美元成長到 2026 年的 266.3 億美元,然後在 2031 年達到 332.2 億美元,2026 年至 2031 年的複合年成長率為 4.52%。
本報告按設備類型(鑽井設備、生產/干預設備、成品設備及其他設備)、地點(陸上、海上)、井型(常規井、非常規井)和地區(北美、歐洲、亞太、南美以及中東和非洲)進行分類。市場預測以美元計價。
全球油田設備租賃服務市場趨勢與分析
頁岩油和緻密油鑽探活動增加
二疊紀盆地和鷹灘頁岩油田的水平鑽井作業持續縮短油井週期,儘管鑽機總數有所減少,但每台鑽機每年的鑽井數量卻在增加。模組化租賃設備、壓力輸液設備、纜線作業裝置和撓曲油管系統支援同步壓裂和修整壓裂作業,可同時對多口井進行壓裂,從而在商品價格波動的情況下保持運轉率。 YPF和殼牌公司已擴大在阿根廷瓦卡穆埃爾塔油田的投資,並從北美進口租賃設備以加快開發進程。
回收深海域設備投資
巴西石油公司(Petrobras)已批准一項58億美元的預算,用於建造兩個鹽層下鑽井平台,每個平台都需要數年的鑽井船作業。英國石油公司(BP)位於墨西哥灣的蒂巴爾瓜達盧佩(Tibar Guadalupe)專案需要20,000磅/平方英吋(psi)的海底設備,幾乎全部透過租賃方式提供。 Transocean公司2025年的合約為其累積訂單增加了23億美元,這表明海上租賃需求具有永續性。
原油價格波動
2026年初霍爾木茲海峽暫時關閉後,布蘭特原油價格飆升至每桶103-118美元,但幾週內便跌破82美元。這迫使油氣探勘開發公司推遲鑽機的運作並削減可自由支配的預算。儘管油價暫時上漲,但2026年2月美國陸上運作鑽井鑽機的數量仍比上月下降了4%。
細分市場分析
到2025年,鑽井設備將佔總收入的47.3%,這反映了多年期鑽機合約對大規模資本投資計畫的支持。在油田設備租賃服務市場,成品設備市場預計將以5.2%的複合年成長率成長,超過整體市場成長率,這主要得益於同步壓裂作業的增加。 Helmerich & Payne公司的FlexRig平台已將德克薩斯州的總鑽井時間縮短了30%,這充分說明了高性能租賃設備如何支撐其較高的每日租金。
生產和介入工具、修井鑽機、人工採油系統和油井測試設備均供應給成熟油田,並以較短的租賃週期輪換使用。威德福累計,到2025年,人工採油租賃收入將達到18億美元,其中電動潛水泵將佔該業務板塊收入的60%。
區域分析
以二疊紀盆地和墨西哥灣為中心的北美地區預計在2025年貢獻38.5%的收入。雖然陸上鑽井鑽機的數量仍遠低於2019年的峰值,但營運商利用Simuflac技術提高了租賃設備的周轉率,從而完成了更多油井。 BP的Tibar Guadalupe計畫已獲批准,確保了超深水鑽井船和海底設備的租賃服務直至2031年。
亞太地區預計到2031年將以5.9%的複合年成長率成長,主要受以下因素推動:中國為期7年的非傳統資源計劃需要新增120座鑽井鑽機(其中大部分將以租賃方式運營);印度石油天然氣公司(ONGC)將其陸上鑽井平台租賃降低成本的節省用於海上探勘。馬來西亞國家石油公司(Petronas)已簽署六份升降式鑽井平台租賃協議,將於2025年完工,顯示東南亞淺水租賃市場正在復甦。
歐洲的情況各不相同。在挪威,專案核准仍在繼續,例如AkerBP的Johan Castberg項目和Equinor的Rosebank項目,這表明挪威需要從有限的供應商租賃能夠在惡劣環境下作業的半潛式鑽機。相較之下,在英國,稅收增加抑制了投資,降低了未來對租賃資產的需求。
巴西在南美洲處於主導。巴西石油公司(Petrobras)的SEAP中心和BW能源公司的馬龍巴油田需要多艘鑽井船和海底設備,並簽訂了長期租賃協議。阿根廷的瓦卡穆爾塔油田也持續從北美進口租賃的壓裂和鑽井設備。
中東和非洲市場依然強勁。到2025年底,阿布達比國家石油公司(ADNOC)鑽井部門將擁有118個運作單元,其中許多是租賃的。同時,沙烏地阿美公司的預算重點放在天然氣業務上,上游鑽井業務外包給第三方租賃公司。隨著新發現進入評估階段,奈及利亞和奈米比亞正成為深海鑽井設備租賃的新興市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 頁岩緻密油鑽探活動增加
- 深海域資本投資的復甦
- 油氣探勘開發公司低資本投資趨勢
- 全球老舊鑽機船隊的更新換代
- 模組化井場自動化系統的租賃需求
- 低碳、電動化的租賃車隊
- 市場限制因素
- 原油價格波動
- 加強環境法規
- 價格競爭會對利潤率帶來壓力。
- HPHT組件供應鏈短缺
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 石油和天然氣生產及消費預測
- 陸上及海上運作鑽機數量及預測
- 境內外資本投資預測
第5章:預測市場規模與成長率
- 依設備類型
- 鑽井設備
- 生產和乾預設施
- 已完成的設備
- 其他類型的設備
- 按位置
- 陸上
- 離岸
- 按井的類型
- 傳統的
- 傳統型
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 挪威
- 英國
- 俄羅斯
- 荷蘭
- 德國
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 澳洲
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 伊朗
- 奈及利亞
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Schlumberger Limited
- Halliburton Company
- Baker Hughes Company
- Weatherford International
- Superior Energy Services
- Transocean Ltd
- Valaris plc
- Noble Corporation plc
- Seadrill Ltd
- Patterson-UTI Energy
- Nabors Industries
- Oil States International
- KLX Energy Services
- Key Energy Services
- Precision Drilling
- Expro Group
- Archer Limited
- Trican Well Service
- EnerMech
- Basic Energy Services
第7章 市場機會與未來展望
According to Mordor Intelligence, the oilfield equipment rental services market size is expected to grow from USD 25.48 billion in 2025 to USD 26.63 billion in 2026 and is forecast to reach USD 33.22 billion by 2031 at 4.52% CAGR over 2026-2031.
This report is Segmented by Equipment Type (Drilling Equipment, Production and Intervention Equipment, Completion Equipment, Other Equipment Types), Location (Onshore, Offshore), Well Type (Conventional, Unconventional), and Geography (North America, Europe, Asia Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Oilfield Equipment Rental Services Market Trends and Insights
Rising Shale & Tight-Oil Drilling Activity
Horizontal drilling in the Permian and Eagle Ford continues to shorten well cycles, enabling more wells per rig-year even with a lower total rig count. Modular rental equipment, pressure-pumping spreads, wireline units, and coiled-tubing systems supports simulfrac and trimulfrac operations that fracture multiple wellbores at once, sustaining utilization despite commodity volatility. YPF and Shell increased investment in Argentina's Vaca Muerta, importing North American rental fleets to accelerate development.
Offshore Deep-Water CAPEX Rebound
Petrobras approved USD 5.8 billion for two pre-salt hubs that will each require multi-year drillship campaigns. BP's Tiber-Guadalupe project in the Gulf of Mexico demands 20,000-psi subsea architectures supplied almost entirely on a rental basis. Transocean's 2025 contract wins added USD 2.3 billion to backlog, signaling durable offshore rental demand.
Crude-Price Volatility
Brent spiked to USD 103-118 per barrel after the temporary Strait of Hormuz closure in early 2026, then fell below USD 82 within weeks, prompting E&Ps to delay rig reactivations and squeeze discretionary budgets. U.S. land rig activity slipped 4% month-over-month in February 2026 despite the brief price rally.
Other drivers and restraints analyzed in the detailed report include:
- Cap-Ex-Lite Preference Among E&Ps
- Ageing Global Rig Fleet Replacements
- Stricter Environmental Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Drilling equipment captured 47.3% of 2025 revenue, reflecting multi-year rig-rental contracts that underpin large capital programs. The oilfield equipment rental services market size for completion equipment is projected to expand at a 5.2% CAGR, outpacing aggregate growth as simulfrac operations multiply. Helmerich & Payne's FlexRig platform trimmed total-depth times by 30% in West Texas, illustrating how high-spec rentals justify premium dayrates.
Production and intervention tools, workover rigs, artificial-lift systems, and well-test packages serve mature fields and rotate through shorter rental cycles. Weatherford booked USD 1.8 billion in 2025 artificial-lift rentals, with electric submersible pumps representing 60% of segment sales.
Geography Analysis
North America generated 38.5% of 2025 revenue, anchored by the Permian Basin and Gulf of Mexico. Despite a land-rig count well below the 2019 peak, operators completed more wells by using simulfrac techniques that intensify rental-equipment turnover. BP's Tiber-Guadalupe sanction locks in ultra-deepwater drillship and subsea rentals through 2031.
Asia-Pacific is forecast to grow at a 5.9% CAGR through 2031 as China's seven-year unconventional plan calls for 120 additional drilling rigs most of them leased and India's ONGC channels savings from onshore fleet rentals into offshore exploration. Petronas awarded six jackup charters in 2025, signaling a rebound for Southeast Asian shallow-water rentals.
Europe shows mixed dynamics. Norway continues to approve projects AkerBP's Johan Castberg and Equinor's Rosebank requiring harsh-environment semisubs leased from a narrow supplier base. In contrast, UK investment is cooling under higher taxes, dampening future demand for rental assets.
South America's momentum is dominated by Brazil. Petrobras' SEAP hubs and BW Energy's Maromba field will each consume multiple drillships and subsea packages under long-term rentals. Argentina's Vaca Muerta continues to import frac and drilling rentals from North America.
The Middle East and Africa remain resilient. ADNOC Drilling operated 118 units at end-2025, much of it leased, while Saudi Aramco's budget focuses on gas, leaving upstream drilling to third-party rental providers. Nigeria and Namibia are bright spots for deep-water rentals as new discoveries move toward appraisal.
- Schlumberger Limited
- Halliburton Company
- Baker Hughes Company
- Weatherford International
- Superior Energy Services
- Transocean Ltd
- Valaris plc
- Noble Corporation plc
- Seadrill Ltd
- Patterson-UTI Energy
- Nabors Industries
- Oil States International
- KLX Energy Services
- Key Energy Services
- Precision Drilling
- Expro Group
- Archer Limited
- Trican Well Service
- EnerMech
- Basic Energy Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising shale & tight-oil drilling activity
- 4.2.2 Offshore deep-water CAPEX rebound
- 4.2.3 Cap-ex-lite preference among E&Ps
- 4.2.4 Ageing global rig fleet replacements
- 4.2.5 Modular well-site automation rental demand
- 4.2.6 Low-carbon electrified rental fleets
- 4.3 Market Restraints
- 4.3.1 Crude-price volatility
- 4.3.2 Stricter environmental regulations
- 4.3.3 Margin compression from price wars
- 4.3.4 Supply-chain shortages for HPHT parts
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Crude-Oil and Natural Gas Production & Consumption Outlook
- 4.9 Onshore & Offshore Active-Rig Count and Forecast
- 4.10 Onshore vs Offshore CAPEX Forecast
5 Market Size & Growth Forecasts
- 5.1 By Equipment Type
- 5.1.1 Drilling Equipment
- 5.1.2 Production and Intervention Equipment
- 5.1.3 Completion Equipment
- 5.1.4 Other Equipment Types
- 5.2 By Location
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Well Type
- 5.3.1 Conventional
- 5.3.2 Unconventional
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Norway
- 5.4.2.2 United Kingdom
- 5.4.2.3 Russia
- 5.4.2.4 Netherlands
- 5.4.2.5 Germany
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia
- 5.4.3.7 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Iran
- 5.4.5.4 Nigeria
- 5.4.5.5 South Africa
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Schlumberger Limited
- 6.4.2 Halliburton Company
- 6.4.3 Baker Hughes Company
- 6.4.4 Weatherford International
- 6.4.5 Superior Energy Services
- 6.4.6 Transocean Ltd
- 6.4.7 Valaris plc
- 6.4.8 Noble Corporation plc
- 6.4.9 Seadrill Ltd
- 6.4.10 Patterson-UTI Energy
- 6.4.11 Nabors Industries
- 6.4.12 Oil States International
- 6.4.13 KLX Energy Services
- 6.4.14 Key Energy Services
- 6.4.15 Precision Drilling
- 6.4.16 Expro Group
- 6.4.17 Archer Limited
- 6.4.18 Trican Well Service
- 6.4.19 EnerMech
- 6.4.20 Basic Energy Services
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 旋轉傾斜台市場:全球市場預測,2026-2032年
 海上油田服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)油田設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)油田設備市場:2026-2032年全球市場預測(按設備類型、作業階段、鑽井技術、服務類型、應用和最終用戶分類)
 油田租賃服務市場:全球產業規模、市場佔有率、趨勢、機會和預測(按設備、應用和地區分類)、競爭格局(2021-2031 年)
 油田設備租賃市場規模、佔有率和成長分析:按設備、應用、最終用戶產業和地區分類-2026-2033年產業預測高膨脹可回收橋塞市場:依設定深度、回收機制、材料、額定壓力和應用分類-全球預測,2026-2032年按鑽機移動性、井架類型、負載能力、應用、鑽井深度和最終用戶分類的油井鑽井架市場-全球預測,2026-2032年
 油田設備租賃服務市場規模、佔有率及成長分析(依設備、服務類型、應用、最終用戶及地區分類)-2026-2033年產業預測橋塞市場 - 全球產業規模、佔有率、趨勢、機會、預測(按類型、現狀、材料、應用、地區和競爭格局分類),2021-2031年