


 |
市場調查報告書
商品編碼
2063367
建築攝影機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Construction Camera - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
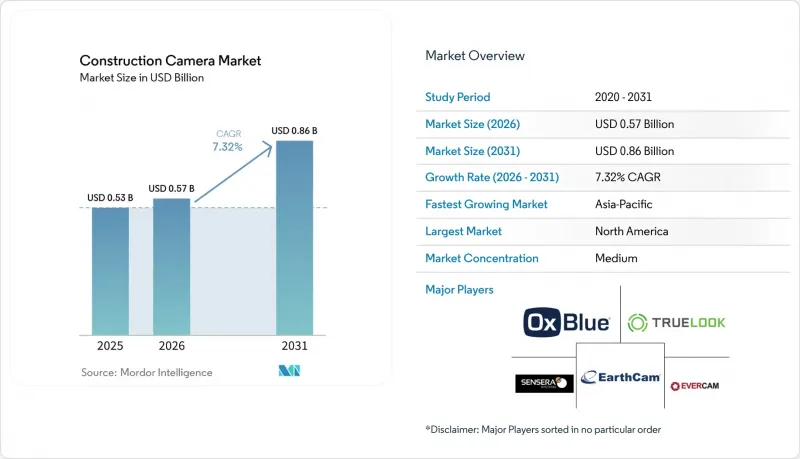
根據 Mordor Intelligence 預測,建築攝影機市場規模將從 2025 年的 5.3 億美元成長到 2026 年的 5.7 億美元,到 2031 年達到 8.6 億美元,2026 年至 2031 年的複合年成長率為 7.32%。
本報告按產品類型(固定攝影機、雲台攝影機等)、電源(交流電源系統、太陽能電源系統等)、連接方式(4G/5G蜂窩網路、Wi-Fi/Mesh網路等)、應用領域(進展監控和記錄等)、終端用戶產業(總承包商等)以及地區進行細分。市場預測以美元計價。
全球建築攝影機市場趨勢及洞察
邊緣人工智慧驅動的安全合規性分析
整合到攝影機中的邊緣處理器現在可以在不到 200 毫秒內偵測到個人防護設備(PPE) 的缺失、近距離危險以及對限制區域的入侵。到 2025 年,早期採用者將使美國職業安全與健康管理局 (OSHA) 記錄的事故數量減少 34%,使承包商能夠協商更低的勞工保險保險費。本地推理確保了隱私,因為只有事件元資料會從現場傳輸,符合加州立法機構第 1221 號法案和 GDPR 的要求。雖然目前該技術的應用仍集中在面臨更高風險的領域,例如鋼骨組裝和電氣作業,但晶片組價格的下降預計將在三年內使普通建設業受益。
與Procore和Autodesk BIM工作流程整合
透過即插即用的應用程式介面 (API),現場主管無需離開專案控制面板,只需開啟每日日誌並點擊時間戳即可存取同步影像。根據 Procore 的投資報酬率 (ROI) 研究,到 2026 年,採用此類整合技術的建設公司返工成本降低了 23%,專案超支減少了 18%。現場工作人員將測量影像與整合的 BIM 模型進行比對後,當安裝超出公差範圍時,設計人員幾乎可以即時收到警報,從而縮短了以往需要數週時間的反饋週期。
多站點營運的初始硬體成本較高
一家管理 10 到 20 個專案的中型建築公司需要投入 5 萬到 15 萬美元的巨額資金來部署多攝影機系統。雖然訂閱模式透過降低前期成本提供了更經濟實惠的實施方案,但通常會將公司束縛在長期合約(通常為 36 個月)中。這些合約可能導致每台設備的總成本高達 10,800 美元,如果在合約期間內專案工作量減少,這將給承包商帶來挑戰。此外,諸如巴西對影像設備徵收 16% 的進口關稅等外部因素進一步增加了採購成本。在一些非洲國家,設備融資管道有限,即使有融資管道,通常也伴隨著高達 12% 的年利率,這又增加了另一個障礙,導致採購決策延遲,並阻礙了這些地區先進攝影機系統的應用。
細分市場分析
施工攝影機市場按產品類型細分,其中固定式攝影機佔42.51%的銷售額。建築公司通常在高速公路和地形平坦的工業工地選擇這些低成本型號,因為單一觀點即可覆蓋長達數月的施工。然而,在高層建築和橋墩等高空作業中,由於工人每週都要重新調整起重機的位置,固定式攝影機會遮擋視線。因此,移動式拖車和起重機安裝式攝影機的年成長率高達9.37%,超過了施工攝影機市場的整體成長率。一台移動式雲台攝影機即可取代多台固定式攝影機,進而減少資料通訊使用量和現場巡檢次數。然而,馬達日益複雜化也增加了維護負擔,尤其是在沿岸地區多塵的沙漠環境和北極地區的強風條件下。
此外,行動解決方案憑藉其先進的分析功能,能夠實現更高的定價。供應商將雲台機器人與邊緣人工智慧模組結合,逐層識別模板施工進展,並將數據回饋到進度管理軟體中,以計算已掙值。租賃設備的擴張源於業主傾向於將設備作為表外資產,並預先安裝蜂窩通訊軟體包。交付亞太和中東地區大型企劃儲備的增加,對易於移動的鑽機的需求也在不斷成長,這預示著產品類型將在預測期內轉變。
到2025年,太陽能發電將佔電力供應的51.33%,目前在建築攝影機市場中佔據最大佔有率。轉換效率將達到22%,而磷酸鋰鐵鋰電池帶來的更長運作時間預計將使複合年成長率達到9.53%,優於交流電供電的替代方案。鑑於電網擴建成本仍高達每英里1.5萬至3萬美元,如果施工地點每六個月更換一次,太陽能發電在總體擁有成本方面將更具優勢。一項預計於2025年投入使用的專利蜂窩通訊頻寬控制技術,即使在電池電量較低的情況下也能降低影像位元率,因此無需添加新的太陽能電池板即可維持運作時間。
對於工期少於90天的拆除和場地準備工程,如果無法進行太陽能板折舊,則純電池供電和混合供電系統較為適用。在都市區改造區域,由於拖車和塔式起重機的臨時電源已到位,交流供電的PoE攝影機仍然可行。總體而言,太陽能發電可靠性的提高及其符合公共競標中的碳減排目標,正在鞏固其在建築攝影機市場的長期核心地位。
區域分析
到2025年,北美將佔全球銷售額的38.83%。這得益於保險費扣除,該扣除可將建築公司的責任成本降低高達25%。美國的大型企劃,例如耗資59億美元的戈迪·豪國際大橋,正在部署數十套行動雲台鑽機,並受益於用於即時影像分發的專用5G骨幹網路。加拿大的貿易多元化走廊基金強制要求在聯邦政府資助的道路和港口進行延時拍攝,從而催生了對攝影機競標的需求。在墨西哥,近岸工業工廠需要遵守美國的出口管制審計,因此要求從運作第一天起就實施持續的視訊監控系統。
亞太地區預計將以9.57%的複合年成長率實現最高成長,這主要得益於各國政府投入數十億美元用於交通走廊、海底隧道和智慧城區建設。中國420億美元的城市現代化計畫要求提供反腐敗措施的視覺證據作為獲得資金的條件。在印度,為了滿足國家公路管理局的品質標準,布拉馬普特拉河隧道和杜布里-胡爾巴里大橋的EPC合約中都加入了安裝攝影機的條款。日本的地震重建指南要求所有抗震加固工程都必須安裝攝影機,而韓國正在試行將BIM連結的影像疊加技術應用於現場,以縮短未完成項目清單的處理週期。這些政策正在創造對施工攝影機的長期需求。
在歐洲,商業機會與合規摩擦之間正尋求平衡。 GDPR法規將影像的保留期限限制在30天,除非與事件相關,這迫使供應商提供匿名化服務。英國的《建築安全法》強制要求高層建築安裝數位雙胞胎,使攝影機成為貫穿設施管理整個生命週期的工具。在中東,政府主導的城市發展項目,例如NEOM,需要在數千平方公里的範圍內安裝太陽能攝影機。阿提哈德鐵路公司耗資110億美元的鐵路網路在偏遠的沙漠線路上安裝了60個鏡頭,這表明極端溫度正在加速對耐環境設備的需求。由於進口關稅和高昂的借貸成本,南美洲和非洲的發展相對滯後,但隨著收費公路特許經營模式中開始明確規定攝影機要求,成長的種子正在播下。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 遠端專案管理平台的廣泛應用
- 用於相關人員行銷的高解析度縮時攝影
- 與Procore/Autodesk和BIM工作流程的整合
- 利用太陽能進行自主部署
- 邊緣人工智慧驅動的安全合規性分析
- 基於視覺記錄的保費折扣
- 市場限制因素
- 多站點部署涉及較高的初始硬體成本
- 頻寬和雲端儲存支出
- 加強隱私保護和員工監控的法規
- 成像組件電子設備關稅的變化
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 固定攝影機
- 雲台攝影機
- 360°/全景相機
- 移動拖車和起重機安裝式攝影機
- 透過動力來源
- 交流電源系統
- 太陽能發電系統
- 純電池/混合動力系統
- 連結性別
- 4G/5G蜂窩網路
- Wi-Fi/Mesh
- 有線乙太網路/PoE
- 透過使用
- 進展監測和記錄
- 安全監控
- 行銷與利害關係人相關人員
- 按最終用戶行業分類
- 總承包商
- 業主/開發商
- 政府和基礎設施機構
- 工業EPC和能源公司
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- EarthCam, Inc.
- OxBlue Corporation
- Sensera Systems, Inc.
- TrueLook, Inc.
- Evercam Limited
- Brinno Inc.
- iBEAM Systems, Inc.
- CamDo Solutions Inc.
- Jobcam Pty Ltd
- Buildcam LLC
- HoloBuilder, Inc.
- SiteCams LLC
- OnSite View, Inc.
- Fast Motion GmbH
- Structionsite(DroneDeploy)
- Matterport, Inc.
- Forsight AI, Inc.
- Digital Eagle Technology Development Co., Ltd.
- IVC Mobile Vision, Inc.
- Outdoor Cameras Pty Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the construction camera market size is expected to increase from USD 0.53 billion in 2025 to USD 0.57 billion in 2026 and reach USD 0.86 billion by 2031, growing at a CAGR of 7.32% over 2026-2031.
This report is Segmented by Product Type (Fixed Position Cameras, PTZ Cameras, and More), Power Source (AC-Powered Systems, Solar-Powered Systems, and More), Connectivity (4G/5G Cellular, Wi-Fi/Mesh, and More), Application (Progress Monitoring and Documentation, and More), End-User Industry (General Contractors, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Construction Camera Market Trends and Insights
Edge AI Safety-Compliance Analytics
Edge processors in cameras now flag missing PPE, proximity hazards, and restricted-zone intrusions in under 200 milliseconds. Early adopters cut OSHA-recordable incidents by 34% in 2025, helping contractors negotiate lower workers' compensation premiums. Local inference preserves privacy because only incident metadata leaves the jobsite, satisfying California Assembly Bill 1221 and GDPR mandates. Uptake remains concentrated among steel erection and electrical trades that face higher severity risks, but declining chipset prices should extend the benefits to general trades within three years.
Integration with Procore and Autodesk BIM Workflows
Plug-and-play application programming interfaces allow superintendents to open a daily log, click a timestamp, and call up synchronized imagery without leaving their project dashboard. Construction firms using such integrations reported 23% lower rework costs and 18% fewer schedule overruns in 2026, according to Procore's ROI study. As field crews align as-built imagery with federated BIM models, designers receive near-real-time alerts when installations deviate from tolerances, closing feedback loops that once spanned weeks.
High Upfront Multi-Site Hardware Costs
Mid-size contractors managing 10-20 projects are required to allocate a significant investment of USD 50,000-150,000 to deploy multi-camera systems. While subscription-based models provide a more accessible entry point by reducing upfront costs, they often bind firms into long-term commitments, typically 36-month contracts. These contracts can add up to a total cost of USD 10,800 per unit, posing challenges for contractors if their project workloads decrease during the contract period. Additionally, external factors, such as the 16% import duty on imaging equipment in Brazil, further inflate costs, making procurement more expensive. In several African nations, limited access to equipment financing options, often available at high 12% APR rates, adds another layer of difficulty, delaying purchase decisions and hindering the adoption of advanced camera systems in these regions.
Other drivers and restraints analyzed in the detailed report include:
- Solar-Powered Autonomous Deployments
- Growing Adoption of Remote Project-Management Platforms
- Stricter Privacy and Worker-Surveillance Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The construction camera market size is by product type, with fixed-position units accounting for 42.51% of revenue. Contractors choose these low-cost models for highways and flat industrial sites where a single vantage point covers months of work. Yet on skyscrapers and bridge pylons, crews reposition cranes weekly, and fixed units lose sightlines. Mobile trailer and crane-mounted rigs, therefore, grow at 9.37% annually, outpacing the overall construction camera market. One mobile PTZ can replace several static units, reducing data plan usage and truck rolls. However, increased motor complexity raises maintenance, especially in dusty Gulf deserts or Arctic winds.
Mobile solutions also unlock premium pricing through advanced analytics. Vendors bundle pan-tilt-zoom robotics with edge AI modules that recognize formwork progression floor by floor, feeding earned-value metrics into scheduling software. Rental fleets expand because owners prefer off-balance-sheet equipment that arrives pre-configured with cellular packages. As megaproject pipelines thicken in Asia-Pacific and the Middle East, demand for easily relocated rigs cements the product-type shift over the forecast horizon.
Solar installations commanded 51.33% of the power-source segment in 2025, giving the category the highest construction camera market share at present. Rising conversion efficiencies now reach 22%, and lithium iron phosphate batteries lengthen runtime, driving a 9.53% CAGR projection that outstrips AC-powered alternatives. Extending grid service still costs USD 15,000-30,000 per mile, so the total cost of ownership favors solar when jobsites move every six months. Cellular throttling tech patented in 2025 cuts image bitrate under low-battery states, preserving uptime without new panels.
Battery-only and hybrid systems are suitable for demolition and site prep contracts lasting under 90 days, where panel amortization is unrealistic. In urban infill, AC-powered PoE cameras remain viable because temporary service already exists for trailers and tower cranes. Overall, solar's expanding reliability and compliance with carbon-reduction targets in public bids assure its position as the long-term backbone of the construction camera market.
Geography Analysis
North America accounted for 38.83% of global revenue in 2025, sustained by insurer premium credits that cut builders' liability costs by up to 25%. US megaprojects like the USD 5.9 billion Gordie Howe International Bridge deploy dozens of mobile PTZ rigs and benefit from private 5G backbones for real-time feed delivery. Canada's Trade Diversification Corridors Fund requires time-lapse documentation on federally financed roads and ports, creating a pipeline of camera tenders. Mexico follows with near-shoring industrial plants that must meet US export-control audits and, therefore, install continuous visual monitoring from day one.
Asia-Pacific is forecast to post the highest CAGR of 9.57% as governments allocate multibillion-dollar budgets for transport corridors, underwater tunnels, and smart-city districts. China's USD 42 billion urban modernization program ties funding to visual proof of anti-corruption safeguards. India's Brahmaputra tunnel and Dhubri-Phulbari Bridge embed camera clauses into EPC contracts to satisfy National Highways Authority quality protocols. Japan's earthquake reconstruction guidelines mandate cameras on all seismic retrofits, while South Korea pilots BIM-linked video overlays that shorten punch-list cycles. These policies embed long-term demand into the construction camera market.
Europe balances opportunity with compliance friction. GDPR rules limit footage retention to 30 days unless tagged to incidents, pushing vendors to offer anonymization services. The United Kingdom's Building Safety Act requires digital twins for high-rise assets, turning cameras into lifelong facility management tools. In the Middle East, sovereign-funded cities like NEOM require solar-powered cameras across thousands of square kilometers. Etihad Rail's USD 11 billion network mounted 60 units along remote desert trackage, demonstrating how thermal extremes accelerate demand for ruggedized rigs. South America and Africa trail because of import tariffs and high borrowing costs, yet concession models for toll roads are beginning to state camera deliverables, planting early seeds for growth.
- EarthCam, Inc.
- OxBlue Corporation
- Sensera Systems, Inc.
- TrueLook, Inc.
- Evercam Limited
- Brinno Inc.
- iBEAM Systems, Inc.
- CamDo Solutions Inc.
- Jobcam Pty Ltd
- Buildcam LLC
- HoloBuilder, Inc.
- SiteCams LLC
- OnSite View, Inc.
- Fast Motion GmbH
- Structionsite (DroneDeploy)
- Matterport, Inc.
- Forsight AI, Inc.
- Digital Eagle Technology Development Co., Ltd.
- IVC Mobile Vision, Inc.
- Outdoor Cameras Pty Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Remote Project-Management Platforms
- 4.2.2 High-Resolution Time-Lapse for Stakeholder Marketing
- 4.2.3 Integration with Procore/Autodesk and BIM Workflows
- 4.2.4 Solar-Powered Autonomous Deployments
- 4.2.5 Edge AI Safety-Compliance Analytics
- 4.2.6 Insurance Premium Discounts for Visual Documentation
- 4.3 Market Restraints
- 4.3.1 High Upfront Multi-Site Hardware Costs
- 4.3.2 Bandwidth and Cloud-Storage Expenditures
- 4.3.3 Stricter Privacy/Worker-Surveillance Regulations
- 4.3.4 Electronics-Tariff Volatility on Imaging Components
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Fixed Position Cameras
- 5.1.2 PTZ Cameras
- 5.1.3 360°/Panoramic Cameras
- 5.1.4 Mobile Trailer and Crane-Mounted Cameras
- 5.2 By Power Source
- 5.2.1 AC-Powered Systems
- 5.2.2 Solar-Powered Systems
- 5.2.3 Battery-Only/Hybrid Systems
- 5.3 By Connectivity
- 5.3.1 4G/5G Cellular
- 5.3.2 Wi-Fi / Mesh
- 5.3.3 Wired Ethernet/PoE
- 5.4 By Application
- 5.4.1 Progress Monitoring and Documentation
- 5.4.2 Security and Surveillance
- 5.4.3 Marketing and Stakeholder Engagement
- 5.5 By End-User Industry
- 5.5.1 General Contractors
- 5.5.2 Owners / Developers
- 5.5.3 Government and Infrastructure Agencies
- 5.5.4 Industrial EPC and Energy Firms
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 EarthCam, Inc.
- 6.4.2 OxBlue Corporation
- 6.4.3 Sensera Systems, Inc.
- 6.4.4 TrueLook, Inc.
- 6.4.5 Evercam Limited
- 6.4.6 Brinno Inc.
- 6.4.7 iBEAM Systems, Inc.
- 6.4.8 CamDo Solutions Inc.
- 6.4.9 Jobcam Pty Ltd
- 6.4.10 Buildcam LLC
- 6.4.11 HoloBuilder, Inc.
- 6.4.12 SiteCams LLC
- 6.4.13 OnSite View, Inc.
- 6.4.14 Fast Motion GmbH
- 6.4.15 Structionsite (DroneDeploy)
- 6.4.16 Matterport, Inc.
- 6.4.17 Forsight AI, Inc.
- 6.4.18 Digital Eagle Technology Development Co., Ltd.
- 6.4.19 IVC Mobile Vision, Inc.
- 6.4.20 Outdoor Cameras Pty Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 工業相機市場規模:按類型、感測器類型、應用、地區和預測分類
 無人機系統用相機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 工業相機市場機會、成長要素、產業趨勢分析及2026-2035年預測
 機器人相機支架市場預測—按類型、應用、最終用戶和地區分類的全球分析—2034年滑軌機器人相機市場預測至2034年—按類型、分銷管道、運動範圍、應用和地區分類的全球分析
 攝影系統市場:依產品類型、技術和地區分類
 2026年全球建築攝影解決方案市場報告
 凸輪端面加工系統市場規模、佔有率和成長分析:按操作技術、系統整合、葉片配置、車輛類型、銷售管道和地區分類 - 產業預測,2026-2033 年
 建築攝影解決方案市場:全球市場按產品類型、連接方式、應用和部署模式分類的預測 - 2026-2032 年全球建築攝影機市場規模、佔有率、趨勢和成長分析報告(2026-2034)