


 |
市場調查報告書
商品編碼
2146281
威脅情報市場:依解決方案、服務、應用、產業和地區分類-全球預測至2031年Threat Intelligence Market by Solution (Threat Intelligence Platform (TIPS), SIEM Integration), Services (Risk Assessment and Threat Hunting, MDR), Application (Incident Response, Fraud, Threat Hunting), Vertical, and Region - Global Forecast to 2031 |
||||||

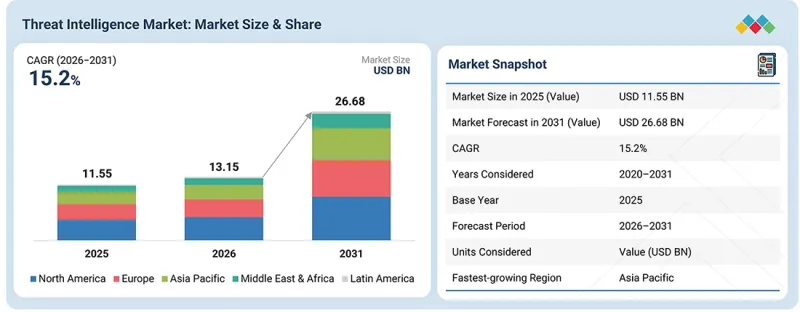
預計在預測期內,威脅情報市場將以 15.2% 的複合年成長率成長,從 2026 年的 131.5 億美元成長到 2031 年的 266.8 億美元。
| 調查範圍 | |
|---|---|
| 調查期 | 2020-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(百萬美元/十億美元) |
| 部分 | 可用性、應用、類型、部署模式、組織規模、產業和地區 |
| 目標區域 | 北美、歐洲、亞太地區、中東和非洲以及拉丁美洲 |
安全策略正從單純的事件回應轉向預防和早期偵測,這種轉變推動了對高階威脅情報的需求。同時,量子運算研究的快速發展也引發了人們對現有加密方法長期安全性的擔憂,促使企業尋求更先進的情報能力來預測和緩解新興風險。這些趨勢共同推動了對能夠提供持續監控、預測分析和可操作洞察的解決方案的投資,從而幫助企業在不斷演變的網路威脅面前保持領先地位。
“按應用領域分類,預計到 2026 年,欺詐和金融犯罪檢測領域將佔據最大的市場佔有率。”
到2026年,隨著金融機構擴大利用威脅情報來識別詐騙基礎設施、被盜憑證、惡意域名、網路釣魚宣傳活動和有組織的威脅行為者,詐騙和金融犯罪檢測領域預計將佔據最大的市場佔有率。隨著網路犯罪和金融犯罪的融合,對能夠將外部威脅訊號與可疑交易和客戶行為聯繫起來的情報的需求日益成長。根據國際刑警組織發布的《2026年全球金融詐騙威脅評估報告》,人工智慧驅動的詐騙行為的利潤是傳統方法的4.5倍,而犯罪網路在網路犯罪、詐騙和洗錢方面的活動也日益協調。此外,GoogleMandiant發布的《2025年M趨勢》顯示,2024年活躍的威脅組織中有55%是出於經濟動機,凸顯了網路攻擊背後強烈的經濟動機。因此,金融機構正利用威脅情報在詐騙宣傳活動造成經濟損失之前將其識別出來,加強對帳戶劫持和支付詐騙的偵測,並揭露看似孤立事件之間的關聯。威脅情報透過關聯IP位址、網域名稱、裝置資訊、惡意軟體和被盜憑證等指標來支援調查。隨著數位銀行、即時支付、線上貸款和嵌入式金融服務的擴展,將網路威脅情報與詐騙和金融犯罪分析相結合的需求日益成長,這也鞏固了該領域的領先地位。
“按解決方案分類,預計外部攻擊面管理 (EASM) 細分市場在預測期內將錄得最高的成長率。”
隨著企業面臨日益分散且動態的數位化環境,涵蓋雲端資產、應用程式、API、網域、公共服務和第三方基礎設施,外部攻擊面管理 (EASM) 領域預計將實現最高成長率。傳統的安全方法通常對安全團隊未知的資產缺乏可見性,因此需要持續發現外部資產並進行風險暴露監控。根據 SANS 發布的《2025 年攻擊面管理調查》,基於安全領導者的回饋,89% 的企業希望量化所有資產的風險,而 67% 的企業希望在漏洞被利用時獲得可操作的緩解措施指導。調查還發現,55% 的企業希望攻擊面管理 (ASM) 能夠同時保護內部和外部資產,這表明企業正在轉向更廣泛的風險暴露管理模式。根據 Palo Alto Networks 發布的《Unit 42 全球事件回應報告 2026》(基於 2025 年的研究),87% 的事件涉及跨越兩個或多個攻擊面的活動,其中身分、終端、網路、應用程式、電子郵件和雲端均被認定為攻擊面。 EASM 解決方案透過持續偵測暴露於網路的資產、識別漏洞和錯誤配置、監控變更並根據潛在威脅的相關性確定暴露優先順序來應對這種複雜性。與威脅情報的整合使組織能夠將暴露的資產與活躍的威脅行為者、惡意基礎設施和已知的攻擊活動關聯起來,從而增強主動風險管理。
“從區域分類來看,預計到 2026 年,北美將佔據最大的市場佔有率。”
預計到2026年,北美將佔據最大的市場佔有率,這得益於其成熟的網路安全基礎設施、企業對先進安全技術的高採用率、大量的網路安全支出以及領先的威脅情報供應商的存在。美國是該地區需求的主要驅動力,這主要源於日益複雜的網路威脅、嚴格的網路安全要求以及雲端和數位技術的廣泛應用。根據Palo Alto Networks發布的《2026年Unit 42全球事件回應報告》,在2025年調查的事件中,89%與身分相關問題,其次是終端(61%)和網路(50%),顯示企業面臨的攻擊面日益複雜。因此,北美的企業正在保全行動、事件回應、威脅搜尋、詐欺偵測、漏洞管理和數位風險防護等各環節採用威脅情報。該地區還擁有強大的技術提供者、網路安全專業人員、政府機構和研究機構組成的生態系統,這些機構持續產生和利用威脅情報。人們越來越意識到勒索軟體、供應鏈攻擊、身分外洩和新興的人工智慧驅動威脅,這促使各組織將即時情報整合到保全行動中,進一步鞏固了其在北美市場的領先地位。
初步調查參與者組成
本次調查匯集了來自各行各業專家的見解,包括零件供應商、一級供應商和整車製造商。主要受訪者組成如下:
- 按公司類型分類:一級供應商 - 35%,二級供應商 - 45%,三級供應商 - 20%
- 按職位:首席級別主管 - 60%,經理及其他人員 - 40%
- 區域細分:北美 -3%,歐洲 -26%,亞太地區 -21%,中東和非洲 -10%,拉丁美洲 -5%
威脅情報市場的主要供應商包括 Palo Alto Networks(美國)、思科(美國)、Check Point(以色列)、CrowdStrike(美國)、IBM(美國)、Recorded Future(美國)、Google(美國)、Flashpoint(美國)、Group-IB(新加坡)、卡巴斯基(俄羅斯)、Tapix(美國)、Rrellti7) CPX(阿拉伯聯合大公國)。
本研究對威脅情報市場的主要參與者進行了詳細的競爭分析,包括公司簡介、近期發展和主要市場策略。
調查範圍
本報告對威脅情報市場進行細分,並按產品(解決方案、服務)、應用(數位風險和品牌保護、詐欺和金融犯罪偵測、威脅搜尋、事件回應、內部威脅偵測、風險和合規管理、其他(漏洞情報和第三方情報))、類型(策略、營運、戰術、技術)、部署計畫(本地部署、雲端部署、混合部署)、小型企業組織(大型企業、營運、戰術性、技術)、部署產業間(本地部署、雲端部署、混合部署)、小型企業組織(大型企業、營運、戰術、技術)、部署產業間(本地部署、雲端部署、混合部署)、小型企業組織(大型企業中金融企業) (BFSI)、政府、國防和情報機構、醫療保健、零售、旅遊、航空和物流、IT、ITeS 和電信、能源和工業、媒體和娛樂、其他(教育、建築、房地產))以及地區(北美、歐洲、亞太地區、中東和非洲、拉丁美洲)預測市場規模。
此外,本研究還包括對主要市場參與者的詳細競爭分析、公司簡介、有關其產品和服務的主要觀察、近期發展和主要市場策略。
購買本報告的主要好處
本報告為市場領導和新參與企業提供威脅情報市場及其細分領域最準確的收入預測。它幫助相關人員了解競爭格局,最佳化業務定位,並制定合適的打入市場策略。此外,本報告還幫助相關人員了解市場趨勢,並提供關鍵市場促進因素、限制因素、挑戰和機會的資訊。
本報告深入分析了以下幾點:
- 對關鍵促進因素(網路犯罪加劇和入侵方法不斷演變、轉向主動威脅情報、透過策略性收購和合作實現業務擴張、以及透過投資網路安全加速創新)、阻礙因素(初始部署和整合成本高、缺乏跨平台標準化)、機會(聯網設備和物聯網風險的擴展、日益嚴峻的雲端安全挑戰以及人工智慧和機器學習的濫用)和挑戰(有訓練的威脅)
- 產品開發/創新:深入了解威脅情報市場中即將出現的技術、研發活動、新產品和服務推出。
- 市場發展:有關盈利市場的全面資訊(本報告分析了各個地區的威脅情報市場)。
- 市場多元化:全面介紹威脅情報市場的新解決方案和服務、未開發的地區、最新趨勢和投資機會。
- 競爭分析:我們將對威脅情報市場主要參與者的市場佔有率、成長策略和服務產品進行詳細評估,這些參與者包括 Palo Alto Networks(美國)、思科(美國)、Check Point(以色列)、CrowdStrike(美國)、IBM(美國)、Recorded Future(美國)、Google(美國)、Flashpoint(美國)、Group-IB(新加坡)、卡巴斯基(俄羅斯)、Trellix(美國)、Rapid7(美國)、Fortinet(美國)、ReliaQuest(美國)和 CPX(阿拉伯聯合大公國)。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 威脅情報市場為企業提供了極具吸引力的機會。
- 威脅情報市場:依服務類型分類
- 威脅情報市場:依解決方案分類
- 威脅情報市場:依應用領域分類
- 威脅情報市場:依產業分類
- 威脅情報市場:按地區分類
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 相互關聯的市場
- 跨產業機遇
- 一級/二級/三級主要公司的策略性舉措
- 各層級戰略模式
- 策略趨勢
第5章 產業趨勢
- 波特五力分析
- 新進入者的威脅
- 替代品的威脅
- 供應商的議價能力
- 買方的議價能力
- 競爭公司之間的競爭強度
- 總體經濟指標
- GDP趨勢與預測
- 全球資訊通訊技術產業趨勢
- 全球網路安全產業的趨勢
- 價值鏈分析
- 規劃與設計
- 威脅情報解決方案
- 系統整合
- 諮詢
- 按行業
- 生態系分析
- 價格分析
- 主要企業威脅情報解決方案的平均售價(2025 年)
- 2025年按應用領域分類的參考價格分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 美國關稅在2025年的影響概述
- 主要關稅稅率
- 價格影響分析
- 對國家和地區的影響
- 產業
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要技術
- 互補技術
- 鄰近技術
- 人工智慧在威脅情報市場的應用
- 全球人工智慧在威脅情報市場的發展趨勢
- 推動人工智慧在威脅情報市場應用的因素
- 技術藍圖
- 短期(2026-2027 年)| 基礎設施建設和初始平台擴展
- 中期計劃(2027-2030 年)| 規模化、自動化和智慧整合
- 長期(2030-2035 年及以後)| 自主、適應性與預測性威脅情報
- 專利分析
- 未來應用
- 人工智慧驅動的威脅情報和自動化分析
- 預測性和行為威脅情報
- 雲端運算、物聯網、營運技術以及以身分為中心的威脅情報
- 嵌入式和跨平台威脅情報
- 整合威脅情報與保全行動生態系統
- 人工智慧/通用人工智慧對威脅情報市場的影響
- 威脅情報市場的最佳實踐
- 人工智慧在威脅情報市場的應用案例研究
- 相互關聯的鄰近生態系及其對市場參與者的影響
- 威脅情報市場中客戶對生成式人工智慧的採用準備情況
- 成功案例和實際應用
- 微軟:人工智慧驅動的保全行動和整合威脅情報
- Fortinet:基於人工智慧的多租戶安全營運中心,整合威脅情報
第7章 監理情勢
- 監理情勢
- 監管機構、政府機構和其他組織
- 業界標準
- 貿易分析
- 出口方案
- 導入場景
第8章 消費者趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 採購過程中的關鍵相關人員
- 購買標準
- 實施障礙和內部挑戰
- 各終端用戶產業未滿足的需求
- 獲利潛力
- 成本趨勢
- 提高關鍵應用領域利潤率的機會
第9章 威脅情報市場:依產品/服務分類
- 透過提供解決方案
- 服務
第10章 威脅情報市場:依應用領域分類
- 偵查詐欺和金融犯罪
- 威脅狩獵
- 內部威脅偵測
- 事件回應
- 風險與合規管理
- 其他用途
第11章 威脅情報市場:依部署模式分類
- 雲
- 現場
- 混合
第12章 威脅情報市場:按類型分類
- 策略
- 手術
- 策略
- 科技
第13章 威脅情報市場:依組織規模分類
- 大公司
- 小型企業
第14章 威脅情報市場:依產業分類
- 銀行業、金融服務業及保險業
- 政府
- 國防和情報機構
- 醫療保健
- 零售
- 旅遊、航空、物流
- 資訊科技、資訊科技服務和通訊
- 能源與工業
- 媒體與娛樂
- 其他行業
第15章 威脅情報市場:按地區分類
- 北美洲
- 北美:市場促進因素
- 美國
- 加拿大
- 歐洲
- 歐洲:市場促進因素
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 亞太地區:市場促進因素
- 中國
- 日本
- 印度
- 新加坡
- 亞太其他地區
- 中東和非洲
- 中東和非洲:市場促進因素
- 中東
- 非洲
- 拉丁美洲
- 拉丁美洲:市場促進因素
- 巴西
- 墨西哥
- 其他拉丁美洲
第16章 競爭格局
- 概述
- 主要參與企業的策略/優勢
- 收入分析(2021-2025)
- 市佔率分析(2025 年)
- 品牌對比
- 企業估值與財務指標(2026)
- 企業估值矩陣:主要公司,2025 年
- 明星公司
- 新興領導者
- 具有廣泛影響力的公司
- 參與企業
- 企業企業發展:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 先進公司
- 應對力的公司
- 充滿活力的公司
- 起跑器
- 競爭標竿分析:新創企業/中小企業,2025 年
- 競爭格局
- 產品發布與開發
- 交易
第17章:公司簡介
- 大公司
- PALO ALTO NETWORKS
- CROWDSTRIKE
- IBM
- CISCO
- FORTINET
- CYBLE
- CHECK POINT
- TRELLIX
- RAPID7
- RECORDED FUTURE(MASTERCARD)
- GROUP-IB
- KASPERSKY
- ANOMALI
- CPX(G42)
- KELA
- SOCRADAR
- ZEROFOX
- ORANGE
- RESECURITY
- HELP AG(ETISALAT)
- GATEWATCHER
- CYBERINT
- THREATCONNECT(DATAMINR)
- QUOINTELLIGENCE
- THREATMON
- SECURITY PACT
- SECURIUM SOLUTIONS
- FLASHPOINT
- RELIAQUEST
- SECURONIX
- FILIGRAN
- CLOUDSEK
- SEKOIA.IO
- INTEL 471
- NEBULOCK
- STRIKEREADY
- DREAM
- CYETHACK SOLUTIONS
- DOMAINTOOLS
- BITSIGHT
- THREATBOOK
第18章:調查方法
第19章附錄
The threat intelligence market is projected to grow from USD 13.15 billion in 2026 to USD 26.68 billion by 2031 at a CAGR of 15.2% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2020-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/USD Billion) |
| Segments | Offering, Application, Type, Deployment Mode, Organization Size, Vertical, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
The growing shift toward proactive security strategies, where organizations focus on prevention and early detection instead of purely reacting to incidents, is fueling demand for advanced threat intelligence. At the same time, the rapid progress in quantum computing research is raising concerns over the long-term security of current encryption methods, pushing enterprises to seek more sophisticated intelligence capabilities to anticipate and mitigate emerging risks. Together, these trends are driving investment in solutions that deliver continuous monitoring, predictive analytics, and actionable insights to stay ahead of evolving cyber threats
"By application, the fraud and financial crime detection segment holds the largest market share in 2026."
The fraud and financial crime detection segment holds the largest market share in 2026 as financial institutions increasingly use threat intelligence to identify fraud infrastructure, compromised credentials, malicious domains, phishing campaigns, and coordinated threat actors. The growing convergence of cybercrime and financial crime is strengthening demand for intelligence that can connect external threat signals with suspicious transactions and customer activity. According to INTERPOL's 2026 Global Financial Fraud Threat Assessment, AI enhanced fraud is reported to be 4.5 times more profitable than traditional methods, while criminal networks are increasingly collaborating across cybercrime, fraud, and money laundering operations. Google Mandiant's M Trends 2025 also found that financially motivated groups represented 55% of threat groups active in 2024, highlighting the strong financial motivation behind cyberattacks. Financial institutions are therefore using threat intelligence to identify fraud campaigns before they result in monetary losses, strengthen account takeover and payment fraud detection, and uncover connections between seemingly isolated incidents. Threat intelligence also supports investigation by correlating indicators such as IP addresses, domains, device information, malware, and compromised credentials. As digital banking, instant payments, online lending, and embedded financial services expand, the need to combine cyber threat intelligence with fraud and financial crime analytics is increasing, supporting the segment's leading position.
"By solution, the external attack surface management (EASM) segment is expected to record the fastest growth rate during the forecast period."
The external attack surface management (EASM) segment is expected to record the fastest growth as organizations face increasingly distributed and dynamic digital environments containing cloud assets, applications, APIs, domains, exposed services, and third-party infrastructure. Traditional security approaches often provide limited visibility into assets that security teams do not know exist, creating demand for continuous external discovery and exposure monitoring. The 2025 SANS Attack Surface Management Survey, based on responses from security leaders, found that 89% of organizations expect risk quantification for every asset, while 67% want actionable mitigation guidance when vulnerabilities have public exploits. The survey also found that 55% expect ASM to protect both internal and external assets, demonstrating the shift toward broader exposure management. Palo Alto Networks' 2026 Unit 42 Global Incident Response Report, based on investigations conducted during 2025, found that 87% of incidents involved activity across two or more attack surfaces, while identity, endpoints, networks, applications, email, and cloud were all observed as attack surfaces. EASM solutions address this complexity by continuously discovering internet-facing assets, identifying vulnerabilities and misconfigurations, monitoring changes, and prioritizing exposures based on their potential threat relevance. Integration with threat intelligence enables organizations to correlate exposed assets with active threat actors, malicious infrastructure, and known exploitation activity, strengthening proactive risk management.
"By region, North America is projected to hold the largest market share in 2026."
North America is projected to hold the largest market share in 2026, supported by mature cybersecurity infrastructure, high enterprise adoption of advanced security technologies, substantial cybersecurity spending, and the presence of major threat intelligence vendors. The US represents the principal contributor to regional demand, driven by sophisticated cyber threats, stringent cybersecurity requirements, and extensive adoption of cloud and digital technologies. Palo Alto Networks' 2026 Unit 42 Global Incident Response Report found that identity was involved in 89% of investigated incidents during 2025, followed by endpoints at 61% and networks at 50%, illustrating the increasingly complex attack surfaces faced by organizations. North American organizations are consequently adopting threat intelligence across security operations, incident response, threat hunting, fraud detection, vulnerability management, and digital risk protection. The region also benefits from a strong ecosystem of technology providers, cybersecurity specialists, government agencies, and research organizations that continuously generate and consume threat intelligence. High awareness of ransomware, supply chain attacks, identity compromise, and emerging AI-enabled threats is encouraging organizations to integrate real-time intelligence into their security operations, reinforcing North America's leading market position.
Breakdown of Primaries
The study draws insights from a range of industry experts, including component suppliers, Tier 1 companies, and OEMs. The breakdown of primaries is as follows:
- By Company Type: Tier 1 - 35%, Tier 2 - 45%, and Tier 3 - 20%
- By Designation: C-level Executives - 60%, and Managerial & Other Levels - 40%
- By Region: North America - 3%, Europe - 26%, Asia Pacific - 21%, Middle East and Africa - 10%, Latin America - 5%
Major vendors in the threat intelligence market include Palo Alto Networks (US), Cisco (US), Check Point (Israel), CrowdStrike (US), IBM (US), Recorded Future (US), Google (US), Flashpoint (US), Group-IB (Singapore), Kaspersky (Russia), Trellix (US), Rapid7 (US), Fortinet (US), ReliaQuest (US), and CPX (UAE), among others.
The study includes an in-depth competitive analysis of the key players in the threat intelligence market, their company profiles, recent developments, and key market strategies.
Research Coverage
The report segments the threat intelligence market and forecasts its size by offering (solutions, services), application (digital risk & brand protection, fraud & financial crime detection, threat hunting, incident response, insider threat detection, risk & compliance management, others (vulnerability intelligence and third-party intelligence)), type (strategic, operational, tactical, technical), deployment mode (on-premises, cloud, hybrid), organization size (large enterprises, SMEs), vertical ( Banking, Financial Services and Insurance (BFSI), government, defense & intelligence, healthcare, retail, travel, aviation, & logistics, IT, ITeS, & telecom, energy & industrial, media & entertainment, other verticals (education, construction, and real estate)), and region (North America, Europe, Asia Pacific, Middle East & Africa And Latin America).
The study also includes an in-depth competitive analysis of the market's key players, their company profiles, key observations related to product and business offerings, recent developments, and key market strategies.
Key Benefits of Buying the Report
The report will help market leaders/new entrants with information on the closest approximations of revenue numbers for the overall threat intelligence market and its subsegments. This report will help stakeholders understand the competitive landscape and gain valuable insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Escalating cybercrime and evolving breach tactics, Shift toward proactive threat intelligence, Expansion through strategic acquisitions and alliances, Acceleration of innovation through cybersecurity funding), restraints (High initial deployment and integration costs, Lack of standardization across platforms), opportunities (Expansion of connected devices and IoT risks, Rising cloud security challenges, Malicious use of AI and Machine Learning), and challenges (Lack of trained security analysts to analyze threat intelligence systems, Management of voluminous data)
- Product Development/Innovation: Detailed insights on upcoming technologies, research and development activities, new products, and service launches in the threat intelligence market
- Market Development: Comprehensive information about lucrative markets (The report analyses the threat intelligence market across various regions).
- Market Diversification: Exhaustive information about new solutions and services, untapped geographies, recent developments, and investments in the threat intelligence market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as Palo Alto Networks (US), Cisco (US), Check Point (Israel), CrowdStrike (US), IBM (US), Recorded Future (US), Google (US), Flashpoint (US), Group-IB (Singapore), Kaspersky (Russia), Trellix (US), Rapid7 (US), Fortinet (US), ReliaQuest (US), and CPX (UAE), among others, in the threat intelligence market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIONS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN THREAT INTELLIGENCE MARKET
- 3.2 THREAT INTELLIGENCE MARKET, BY OFFERING
- 3.3 THREAT INTELLIGENCE MARKET, BY SOLUTION
- 3.4 THREAT INTELLIGENCE MARKET, BY APPLICATION
- 3.5 THREAT INTELLIGENCE MARKET, BY VERTICAL
- 3.6 THREAT INTELLIGENCE MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Escalating cybercrime and evolving breach tactics
- 4.2.1.2 Shift toward proactive threat intelligence
- 4.2.1.3 Expansion through strategic acquisitions and alliances
- 4.2.1.4 Advancing threat intelligence capabilities through cybersecurity funding
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial deployment and integration costs
- 4.2.2.2 Lack of standardization across platforms
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of connected devices and IoT risks
- 4.2.3.2 Rising cloud security challenges
- 4.2.3.3 Malicious use of AI and machine learning
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of trained security analysts to analyze threat intelligence systems
- 4.2.4.2 Management of voluminous data
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 CROSS-TIER STRATEGIC PATTERNS
- 4.5.2 STRATEGIC TRENDS
- 4.5.2.1 AI-Driven Threat Intelligence and Automation
- 4.5.2.2 Convergence of Threat Intelligence with Security Operations
- 4.5.2.3 Expansion into External and Emerging Attack Surfaces
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL ICT INDUSTRY
- 5.2.4 TRENDS IN GLOBAL CYBERSECURITY INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 PLANNING AND DESIGNING
- 5.3.2 THREAT INTELLIGENCE SOLUTION
- 5.3.3 SYSTEM INTEGRATION
- 5.3.4 CONSULTATION
- 5.3.5 VERTICALS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF THREAT INTELLIGENCE SOLUTIONS, BY KEY PLAYER, 2025
- 5.5.2 INDICATIVE PRICING ANALYSIS, BY APPLICATION, 2025
- 5.6 KEY CONFERENCES AND EVENTS IN 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.10 IMPACT OF 2025 US TARIFF - OVERVIEW
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 North America
- 5.10.4.1.1 United States
- 5.10.4.1.2 Canada
- 5.10.4.1.3 Mexico
- 5.10.4.1.4 Market Challenges
- 5.10.4.1.5 Mitigation Measures
- 5.10.4.2 Europe
- 5.10.4.2.1 Germany
- 5.10.4.2.2 France
- 5.10.4.2.3 United Kingdom
- 5.10.4.2.4 Market Challenges
- 5.10.4.2.5 Mitigation Measures
- 5.10.4.3 Asia Pacific
- 5.10.4.3.1 China
- 5.10.4.3.2 India
- 5.10.4.3.3 Japan
- 5.10.4.4 Market Challenges
- 5.10.4.5 Mitigation Measures
- 5.10.4.1 North America
- 5.10.5 INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 AI/ML
- 6.1.1.2 Endpoint Detection and Response
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Extended Detection and Response
- 6.1.2.2 Network Detection and Response
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Deception
- 6.1.3.2 Firewall and Intrusion Detection/Prevention Systems
- 6.1.1 KEY TECHNOLOGIES
- 6.2 AI IN THREAT INTELLIGENCE MARKET
- 6.2.1 GLOBAL AI TRENDS IN THREAT INTELLIGENCE MARKET
- 6.2.1.1 Integration of AI with Cyber Threat Intelligence
- 6.2.1.2 Advancements in Natural Language Processing
- 6.2.1.3 Surge in Cloud-based AI threat intelligence solutions
- 6.2.1.4 Adoption of predictive AI threat intelligence
- 6.2.1.5 Accelerated adoption of AI for military-grade cyber threat detection
- 6.2.1.6 Rise of AI-powered botnets
- 6.2.2 FACTORS DRIVING ADOPTION OF AI IN THREAT INTELLIGENCE MARKET
- 6.2.2.1 Growing demand for automated security solutions
- 6.2.2.2 Generative AI advancements
- 6.2.2.3 Emerging AI regulations and governance frameworks
- 6.2.1 GLOBAL AI TRENDS IN THREAT INTELLIGENCE MARKET
- 6.3 TECHNOLOGY ROADMAP
- 6.3.1 SHORT-TERM (2026-2027) | FOUNDATION & EARLY PLATFORM EXPANSION
- 6.3.2 MID-TERM (2027-2030) | SCALING, AUTOMATION & INTELLIGENCE CONSOLIDATION
- 6.3.3 LONG-TERM (2030-2035+) | AUTONOMOUS, ADAPTIVE & PREDICTIVE THREAT INTELLIGENCE
- 6.4 PATENT ANALYSIS
- 6.5 FUTURE APPLICATIONS
- 6.5.1 AI-DRIVEN THREAT INTELLIGENCE AND AUTOMATED ANALYSIS
- 6.5.2 PREDICTIVE AND BEHAVIORAL THREAT INTELLIGENCE
- 6.5.3 CLOUD, IOT, OT, AND IDENTITY-CENTRIC THREAT INTELLIGENCE
- 6.5.4 EMBEDDED AND CROSS-PLATFORM THREAT INTELLIGENCE
- 6.5.5 UNIFIED THREAT INTELLIGENCE AND SECURITY OPERATIONS ECOSYSTEMS
- 6.6 IMPACT OF AI/GEN AI ON THREAT INTELLIGENCE MARKET
- 6.6.1 BEST PRACTICES IN THREAT INTELLIGENCE MARKET
- 6.6.2 CASE STUDIES OF AI IMPLEMENTATION IN THREAT INTELLIGENCE MARKET
- 6.6.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN THREAT INTELLIGENCE MARKET
- 6.7 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.7.1 MICROSOFT: AI-POWERED SECURITY OPERATIONS AND INTEGRATED THREAT INTELLIGENCE
- 6.7.2 FORTINET: AI-POWERED MULTITENANT SOC WITH INTEGRATED THREAT INTELLIGENCE
7 REGULATORY LANDSCAPE
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 TRADE ANALYSIS
- 7.2.1 EXPORT SCENARIO
- 7.2.2 IMPORT SCENARIO
8 CONSUMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS & BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.4.1 REVENUE POTENTIAL
- 8.4.2 COST DYNAMICS
- 8.4.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 THREAT INTELLIGENCE MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: THREAT INTELLIGENCE MARKET DRIVERS
- 9.2 SOLUTIONS
- 9.2.1 THREAT INTELLIGENCE PLATFORMS
- 9.2.1.1 Surge in targeted attacks, ransomware, and APTs to drive market
- 9.2.2 SIEM/SOAR INTEGRATION
- 9.2.2.1 High volume of alerts from SIEM and SOAR platforms to enrich security events with contextualized threat data
- 9.2.3 THREAT FEED AGGREGATORS
- 9.2.3.1 Reduction of false positives to build cost-effective threat monitoring capabilities
- 9.2.3.1.1 Commercial
- 9.2.3.1.2 Open-source
- 9.2.3.1 Reduction of false positives to build cost-effective threat monitoring capabilities
- 9.2.4 MALWARE & VULNERABILITY TOOLS
- 9.2.4.1 Surge in phishing, trojans, and fileless attacks to boost demand for advanced behavioral malware detection
- 9.2.5 THREAT ENRICHMENT API
- 9.2.5.1 API-driven enrichment supporting proactive threat hunting and SOC playbooks to reduce mean time to detect
- 9.2.6 DIGITAL RISK PROTECTION
- 9.2.6.1 Growing online presence and digital footprint to boost adoption of threat intelligence solutions
- 9.2.7 EXTERNAL ATTACK SURFACE MANAGEMENT
- 9.2.7.1 Technological advancements, shifting economic landscapes, and evolving security measures to drive market
- 9.2.1 THREAT INTELLIGENCE PLATFORMS
- 9.3 SERVICES
- 9.3.1 PROFESSIONAL SERVICES
- 9.3.1.1 Organizations seeking proactive threat hunting and vulnerability assessments to leverage expert services and reduce risks
- 9.3.1.2 Designing, integration, and deployment
- 9.3.1.3 Consulting & advisory services
- 9.3.1.4 Risk assessment & threat hunting
- 9.3.1.4.1 Forensic investigation & post-breach analysis
- 9.3.1.4.2 Threat hunting & incident detection
- 9.3.1.4.3 Cyber risk & exposure assessment
- 9.3.1.5 Training & support
- 9.3.2 MANAGED SERVICES
- 9.3.2.1 Adoption of tailored security strategies and continuous risk assessments to drive market
- 9.3.2.2 Managed detection & response
- 9.3.2.3 Threat Intelligence as a Service
- 9.3.1 PROFESSIONAL SERVICES
10 THREAT INTELLIGENCE MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.1.1 APPLICATION: THREAT INTELLIGENCE MARKET DRIVERS
- 10.2 FRAUD & FINANCIAL CRIME DETECTION
- 10.2.1 INCREASING CYBER FRAUD, PAYMENT FRAUD, AND IDENTITY THEFT TO DRIVE DEPLOYMENT OF AI/ML-POWERED DETECTION SYSTEMS
- 10.3 THREAT HUNTING
- 10.3.1 GROWING SOPHISTICATION OF ATTACKS AND TARGETED APT CAMPAIGNS TO BOOST MARKET
- 10.4 INSIDER THREAT DETECTION
- 10.4.1 PERSISTENT INSIDER RISKS IN REMOTE AND HYBRID WORK ENVIRONMENTS TO DRIVE DEPLOYMENT OF BEHAVIOR ANALYTICS
- 10.5 INCIDENT RESPONSE
- 10.5.1 ESCALATING CYBER INCIDENTS AND BREACH COMPLEXITY TO DRIVE ADOPTION OF AUTOMATED AND EXPERT-LED RESPONSE FRAMEWORKS
- 10.6 RISK & COMPLIANCE MANAGEMENT
- 10.6.1 EXPANDING REGULATORY MANDATES TO DRIVE IMPLEMENTATION OF INTEGRATED RISK AND COMPLIANCE PLATFORMS
- 10.7 OTHER APPLICATIONS
11 THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE
- 11.1 INTRODUCTION
- 11.1.1 DEPLOYMENT MODE: THREAT INTELLIGENCE MARKET DRIVERS
- 11.2 CLOUD
- 11.2.1 COST-EFFECTIVENESS AND EASE OF SECURING APPLICATIONS ON CLOUD TO BOOST MARKET
- 11.3 ON-PREMISES
- 11.3.1 COMPLETE CONTROL OVER PLATFORMS, SYSTEMS, AND DATA TO BOOST DEMAND FOR ON-PREMISES SOLUTIONS
- 11.4 HYBRID
- 11.4.1 PHASED CLOUD MIGRATION TO DRIVE DEMAND FOR HYBRID XDR UNIFIED SECURITY
12 THREAT INTELLIGENCE MARKET, BY TYPE
- 12.1 INTRODUCTION
- 12.2 STRATEGIC
- 12.2.1 RISING ADVANCED PERSISTENT THREATS TO BOOST DEMAND FOR ACTIONABLE INTELLIGENCE
- 12.3 OPERATIONAL
- 12.3.1 ESCALATING INSIDER THREATS TO DRIVE DEMAND FOR OPERATIONAL THREAT INTELLIGENCE IN ANOMALY DETECTION
- 12.4 TACTICAL
- 12.4.1 INCREASING SPEED OF CYBERATTACKS TO BOOST ADOPTION OF REAL-TIME TACTICAL FEEDS
- 12.5 TECHNICAL
- 12.5.1 AI-GENERATED MALWARE TO DRIVE NEED FOR DEEPER TECHNICAL ANALYSIS
13 THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE
- 13.1 INTRODUCTION
- 13.1.1 ORGANIZATION SIZE: THREAT INTELLIGENCE MARKET DRIVERS
- 13.2 LARGE ENTERPRISES
- 13.2.1 SURGING DEMAND FOR EFFECTIVE MANAGEMENT OF BUSINESS APPLICATIONS TO BOOST MARKET
- 13.3 SMALL & MEDIUM-SIZED ENTERPRISES
- 13.3.1 ADOPTION OF REMOTE WORK TO CREATE DEMAND FOR INTELLIGENCE-DRIVEN MONITORING SOLUTIONS
14 THREAT INTELLIGENCE MARKET, BY VERTICAL
- 14.1 INTRODUCTION
- 14.1.1 VERTICAL: THREAT INTELLIGENCE MARKET DRIVERS
- 14.2 BANKING, FINANCIAL SERVICES, AND INSURANCE
- 14.2.1 RAPID GROWTH OF DIGITAL BANKING, MOBILE WALLETS, AND FINTECH TO DRIVE MARKET
- 14.3 GOVERNMENT
- 14.3.1 PROTECTION OF CRITICAL INFRASTRUCTURE AND SENSITIVE CITIZEN DATA TO BOOST TIP ADOPTION
- 14.4 DEFENSE & INTELLIGENCE
- 14.4.1 PROTECTION OF CLASSIFIED DATA, SATELLITE SYSTEMS, AND MILITARY COMMUNICATIONS TO BOOST ADOPTION
- 14.5 HEALTHCARE
- 14.5.1 RISING RANSOMWARE AND DATA BREACH INCIDENTS TARGETING HOSPITALS AND CLINICS TO DRIVE MARKET
- 14.6 RETAIL
- 14.6.1 E-COMMERCE FRAUD, PAYMENT THEFT, AND BOT ATTACKS TO DRIVE MARKET
- 14.7 TRAVEL, AVIATION, AND LOGISTICS
- 14.7.1 RISING RANSOMWARE ATTACKS ON AIRLINES AND LOGISTICS TO BOOST DEMAND FOR THREAT INTELLIGENCE SYSTEMS
- 14.8 IT, ITES, AND TELECOM
- 14.8.1 RAPID DIGITAL TRANSFORMATION ACROSS IT & ITES TO DRIVE MARKET
- 14.9 ENERGY & INDUSTRIAL
- 14.9.1 INCREASING CYBERATTACKS ON OT AND ICS SYSTEMS TO FUEL ADOPTION OF TIP SYSTEMS
- 14.10 MEDIA & ENTERTAINMENT
- 14.10.1 INCREASING DDOS ATTACKS ON STREAMING PLATFORMS TO BOOST ADOPTION OF THREAT INTELLIGENCE SOLUTIONS
- 14.11 OTHER VERTICALS
15 THREAT INTELLIGENCE MARKET, BY REGION
- 15.1 INTRODUCTION
- 15.2 NORTH AMERICA
- 15.2.1 NORTH AMERICA: MARKET DRIVERS
- 15.2.2 US
- 15.2.2.1 Rising regulatory and compliance pressures to drive broader adoption of threat intelligence solutions
- 15.2.3 CANADA
- 15.2.3.1 Rising awareness among SMEs and large enterprises of reputational and financial risks from cyber incidents
- 15.3 EUROPE
- 15.3.1 EUROPE: MARKET DRIVERS
- 15.3.2 UK
- 15.3.2.1 Growing demand for automated threat detection and real-time intelligence platforms to drive market
- 15.3.3 GERMANY
- 15.3.3.1 Rising awareness among businesses and public institutions of cyber risks and reputational impact to drive market
- 15.3.4 FRANCE
- 15.3.4.1 Rising cyberattacks and data breaches to drive adoption of advanced security solutions
- 15.3.5 ITALY
- 15.3.5.1 Digitalization in public and private sectors to increase exposure to cyber threats and advanced security solutions
- 15.3.6 REST OF EUROPE
- 15.4 ASIA PACIFIC
- 15.4.1 ASIA PACIFIC: MARKET DRIVERS
- 15.4.2 CHINA
- 15.4.2.1 Growing sophistication of AI-driven malware, phishing, and social engineering attacks to drive market
- 15.4.3 JAPAN
- 15.4.3.1 Expansion of public-private collaboration and intelligence-sharing initiatives to drive market
- 15.4.4 INDIA
- 15.4.4.1 Rapid digital transformation and fintech expansion to drive market
- 15.4.5 SINGAPORE
- 15.4.5.1 Growing cross-industry collaboration to counter transnational cybercrime
- 15.4.6 REST OF ASIA PACIFIC
- 15.5 MIDDLE EAST & AFRICA
- 15.5.1 MIDDLE EAST & AFRICA: MARKET DRIVERS
- 15.5.2 MIDDLE EAST
- 15.5.2.1 Regional conflicts and state-sponsored campaigns to increase sophistication and frequency of cyberattacks
- 15.5.2.2 KSA
- 15.5.2.3 UAE
- 15.5.2.4 Rest of Middle East
- 15.5.3 AFRICA
- 15.5.3.1 Regional alliances and intelligence-sharing initiatives to counter cross-border cybercrime
- 15.6 LATIN AMERICA
- 15.6.1 LATIN AMERICA: MARKET DRIVERS
- 15.6.2 BRAZIL
- 15.6.2.1 Rising cyberattacks to drive demand for threat intelligence solutions
- 15.6.3 MEXICO
- 15.6.3.1 Implementation of cybersecurity laws and sector-specific mandates to drive adoption of structured threat intelligence
- 15.6.4 REST OF LATIN AMERICA
16 COMPETITIVE LANDSCAPE
- 16.1 OVERVIEW
- 16.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 16.3 REVENUE ANALYSIS, 2021-2025
- 16.4 MARKET SHARE ANALYSIS, 2025
- 16.5 BRAND COMPARISON
- 16.6 COMPANY VALUATION AND FINANCIAL METRICS, 2026
- 16.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.7.1 STARS
- 16.7.2 EMERGING LEADERS
- 16.7.3 PERVASIVE PLAYERS
- 16.7.4 PARTICIPANTS
- 16.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.7.5.1 Company footprint
- 16.7.5.2 Region footprint
- 16.7.5.3 Offering footprint
- 16.7.5.4 Deployment mode footprint
- 16.7.5.5 Vertical footprint
- 16.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.8.1 PROGRESSIVE COMPANIES
- 16.8.2 RESPONSIVE COMPANIES
- 16.8.3 DYNAMIC COMPANIES
- 16.8.4 STARTING BLOCKS
- 16.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.8.5.1 Detailed list of key startups/SMEs
- 16.8.5.2 Competitive benchmarking of key startups/SMEs
- 16.9 COMPETITIVE SCENARIO
- 16.9.1 PRODUCT LAUNCHES/DEVELOPMENTS
- 16.9.2 DEALS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS
- 17.1.1 PALO ALTO NETWORKS
- 17.1.1.1 Business overview
- 17.1.1.2 Products/Solutions/Services offered
- 17.1.1.3 Recent developments
- 17.1.1.3.1 Product launches/developments
- 17.1.1.3.2 Deals
- 17.1.1.4 MnM view
- 17.1.1.4.1 Key strengths
- 17.1.1.4.2 Strategic choices
- 17.1.1.4.3 Weaknesses and competitive threats
- 17.1.2 CROWDSTRIKE
- 17.1.2.1 Business overview
- 17.1.2.2 Products/Solutions/Services offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Product launches/developments
- 17.1.2.3.2 Deals
- 17.1.2.4 MnM view
- 17.1.2.4.1 Key strengths
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses and competitive threats
- 17.1.3 IBM
- 17.1.3.1 Business overview
- 17.1.3.2 Products/Solutions/Services offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Product launches/developments
- 17.1.3.3.2 Deals
- 17.1.3.4 MnM view
- 17.1.3.4.1 Key strengths
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses and competitive threats
- 17.1.4 CISCO
- 17.1.4.1 Business overview
- 17.1.4.2 Products/Solutions/Services offered
- 17.1.4.3 Recent developments
- 17.1.4.3.1 Product launches/developments
- 17.1.4.3.2 Deals
- 17.1.4.4 MnM view
- 17.1.4.4.1 Key strengths
- 17.1.4.4.2 Strategic choices
- 17.1.4.4.3 Weaknesses and competitive threats
- 17.1.5 GOOGLE
- 17.1.5.1 Business overview
- 17.1.5.2 Products/Solutions/Services offered
- 17.1.5.3 Recent developments
- 17.1.5.3.1 Product launches/developments
- 17.1.5.3.2 Deals
- 17.1.5.4 MnM view
- 17.1.5.4.1 Key strengths
- 17.1.5.4.2 Strategic choices
- 17.1.5.4.3 Weaknesses and competitive threats
- 17.1.6 FORTINET
- 17.1.6.1 Business overview
- 17.1.6.2 Products/Solutions/Services offered
- 17.1.6.3 Recent developments
- 17.1.6.3.1 Product launches/developments
- 17.1.6.3.2 Deals
- 17.1.7 CYBLE
- 17.1.7.1 Business Overview
- 17.1.7.2 Products/Solutions/Services offered
- 17.1.7.3 Recent developments
- 17.1.7.3.1 Product launches
- 17.1.7.3.2 Deals
- 17.1.8 CHECK POINT
- 17.1.8.1 Business overview
- 17.1.8.2 Products/Solutions/Services offered
- 17.1.8.3 Recent developments
- 17.1.8.3.1 Product launches/developments
- 17.1.8.3.2 Deals
- 17.1.9 TRELLIX
- 17.1.9.1 Business overview
- 17.1.9.2 Products/Solutions/Services offered
- 17.1.9.3 Recent developments
- 17.1.9.3.1 Product launches/developments
- 17.1.9.3.2 Deals
- 17.1.9.3.3 Expansions
- 17.1.10 RAPID7
- 17.1.10.1 Business overview
- 17.1.10.2 Products/Solutions/Services offered
- 17.1.10.3 Recent developments
- 17.1.10.3.1 Product launches/developments
- 17.1.10.3.2 Deals
- 17.1.11 RECORDED FUTURE (MASTERCARD)
- 17.1.11.1 Business overview
- 17.1.11.2 Products/Solutions/Services offered
- 17.1.11.3 Recent developments
- 17.1.11.3.1 Product launches/developments
- 17.1.11.3.2 Deals
- 17.1.12 GROUP-IB
- 17.1.12.1 Business overview
- 17.1.12.2 Products/Solutions/Services offered
- 17.1.12.3 Recent developments
- 17.1.12.3.1 Product launches/developments
- 17.1.12.3.2 Deals
- 17.1.13 KASPERSKY
- 17.1.13.1 Business overview
- 17.1.13.2 Products/Solutions/Services offered
- 17.1.13.3 Recent developments
- 17.1.13.3.1 Product launches/developments
- 17.1.13.3.2 Deals
- 17.1.14 ANOMALI
- 17.1.14.1 Business overview
- 17.1.14.2 Products/Solutions/Services offered
- 17.1.14.3 Recent developments
- 17.1.14.3.1 Product launches/developments
- 17.1.14.3.2 Deals
- 17.1.15 CPX (G42)
- 17.1.15.1 Business overview
- 17.1.15.2 Products/Solutions/Services offered
- 17.1.15.3 Recent developments
- 17.1.15.3.1 Deals
- 17.1.16 KELA
- 17.1.16.1 Business overview
- 17.1.16.2 Products/Solutions/Services offered
- 17.1.16.3 Recent developments
- 17.1.16.3.1 Product launches
- 17.1.16.3.2 Deals
- 17.1.17 SOCRADAR
- 17.1.17.1 Business overview
- 17.1.17.2 Products/Solutions/Services offered
- 17.1.17.3 Recent developments
- 17.1.17.3.1 Product launches
- 17.1.17.3.2 Deals
- 17.1.18 ZEROFOX
- 17.1.19 ORANGE
- 17.1.20 RESECURITY
- 17.1.21 HELP AG (ETISALAT)
- 17.1.22 GATEWATCHER
- 17.1.23 CYBERINT
- 17.1.24 THREATCONNECT (DATAMINR)
- 17.1.25 QUOINTELLIGENCE
- 17.1.26 THREATMON
- 17.1.27 SECURITY PACT
- 17.1.28 SECURIUM SOLUTIONS
- 17.1.29 FLASHPOINT
- 17.1.30 RELIAQUEST
- 17.1.31 SECURONIX
- 17.1.32 FILIGRAN
- 17.1.33 CLOUDSEK
- 17.1.34 SEKOIA.IO
- 17.1.35 INTEL 471
- 17.1.36 NEBULOCK
- 17.1.37 STRIKEREADY
- 17.1.38 DREAM
- 17.1.39 CYETHACK SOLUTIONS
- 17.1.40 DOMAINTOOLS
- 17.1.41 BITSIGHT
- 17.1.42 THREATBOOK
- 17.1.1 PALO ALTO NETWORKS
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY DATA
- 18.1.2 PRIMARY DATA
- 18.1.2.1 Breakdown of primary profiles
- 18.1.2.2 Key industry insights
- 18.2 DATA TRIANGULATION
- 18.3 MARKET SIZE ESTIMATION
- 18.3.1 TOP-DOWN APPROACH
- 18.3.2 BOTTOM-UP APPROACH
- 18.4 MARKET FORECAST
- 18.5 RESEARCH ASSUMPTIONS
- 18.6 RESEARCH LIMITATIONS
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS
List of Tables
- TABLE 1 USD EXCHANGE RATES, 2021-2025
- TABLE 2 TYPES OF THREAT INTELLIGENCE
- TABLE 3 UNMET NEEDS AND WHITE SPACES IN THREAT INTELLIGENCE MARKET
- TABLE 4 STRATEGIC MOVES BY PLAYERS IN THREAT INTELLIGENCE MARKET
- TABLE 5 CROSS-TIER STRATEGIC PATTERNS OF VENDORS
- TABLE 6 IMPACT OF PORTER'S FIVE FORCES ON THREAT INTELLIGENCE MARKET
- TABLE 7 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2030
- TABLE 8 ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 9 AVERAGE SELLING PRICE OF THREAT INTELLIGENCE SOLUTIONS, BY KEY PLAYER, 2025 (USD)
- TABLE 10 INDICATIVE PRICING OF KEY PLAYERS, BY APPLICATION, 2025
- TABLE 11 THREAT INTELLIGENCE MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 12 FIRST FINANCIAL BANK ADOPTED PERCH'S COMMUNITY DEFENSE PLATFORM TO OVERCOME CHALLENGES IN THREAT INTELLIGENCE
- TABLE 13 MAJOR UK GOVERNMENT ORGANIZATION USES CYWARE TO 'DEFEND AS ONE' WITH UNIFIED THREAT INTELLIGENCE MANAGEMENT
- TABLE 14 EUROPEAN BANKS' SUCCESS IN MITIGATING RISK OF COMPROMISED ACCOUNTS
- TABLE 15 CYMULATE EMPOWERED GLOBELEQ WITH IN-HOUSE SECURITY & THREAT VALIDATION
- TABLE 16 ANOMALI HELPED CENTERS FOR MEDICARE & MEDICAID SERVICES REDUCE THIRD-PARTY RISK
- TABLE 17 KEY TARIFF RATES
- TABLE 18 LIST OF TOP PATENTS IN THREAT INTELLIGENCE MARKET, 2024-2026
- TABLE 19 TOP USE CASES AND MARKET POTENTIAL
- TABLE 20 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 21 THREAT INTELLIGENCE MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 22 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 23 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 26 REST OF WORLD: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 27 GLOBAL INDUSTRY STANDARDS IN THREAT INTELLIGENCE MARKET
- TABLE 28 EXPORT DATA FOR HS CODE 851762-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 29 IMPORT DATA FOR HS CODE 851762-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 30 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- TABLE 31 KEY BUYING CRITERIA FOR TOP THREE VERTICALS
- TABLE 32 UNMET NEEDS IN THREAT INTELLIGENCE MARKET, BY END-USE INDUSTRY
- TABLE 33 THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 34 THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 35 THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 36 THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 37 SOLUTIONS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 38 SOLUTIONS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 39 THREAT INTELLIGENCE PLATFORMS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 40 THREAT INTELLIGENCE PLATFORMS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 41 SIEM/SOAR: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 42 SIEM/SOAR: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 43 THREAT FEED AGGREGATORS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 44 THREAT FEED AGGREGATORS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 45 MALWARE & VULNERABILITY TOOLS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 46 MALWARE & VULNERABILITY TOOLS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 47 THREAT ENRICHMENT API: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 48 THREAT ENRICHMENT API: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 49 DIGITAL RISK PROTECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 50 DIGITAL RISK PROTECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 51 EXTERNAL ATTACK SURFACE MANAGEMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 52 EXTERNAL ATTACK SURFACE MANAGEMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 53 THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 54 THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 55 SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 56 SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 57 THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 58 THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 59 PROFESSIONAL SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 60 PROFESSIONAL SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 61 DESIGNING, INTEGRATION, AND DEPLOYMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 62 DESIGNING, INTEGRATION, AND DEPLOYMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 63 CONSULTING & ADVISORY: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 64 CONSULTING & ADVISORY: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 65 RISK ASSESSMENT & THREAT HUNTING: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 66 RISK ASSESSMENT & THREAT HUNTING: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 67 TRAINING & SUPPORT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 68 TRAINING & SUPPORT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 69 THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 70 THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 71 MANAGED SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 72 MANAGED SERVICES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 73 MANAGED DETECTION & RESPONSE: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 74 MANAGED DETECTION & RESPONSE: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 75 THREAT INTELLIGENCE AS A SERVICE: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 76 THREAT INTELLIGENCE AS A SERVICE: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 77 THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 78 THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 79 FRAUD & FINANCIAL CRIME DETECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 80 FRAUD & FINANCIAL CRIME DETECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 81 THREAT HUNTING: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 82 THREAT HUNTING: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 83 INSIDER THREAT DETECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 84 INSIDER THREAT DETECTION: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 85 INCIDENT RESPONSE: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 86 INCIDENT RESPONSE: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 87 RISK & COMPLIANCE MANAGEMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 88 RISK & COMPLIANCE MANAGEMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 89 OTHER APPLICATIONS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 90 OTHER APPLICATIONS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 91 THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 92 THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 93 CLOUD: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 94 CLOUD: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 95 ON-PREMISES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 96 ON-PREMISES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 97 HYBRID: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 98 HYBRID: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 99 THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 100 THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 101 LARGE ENTERPRISES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 102 LARGE ENTERPRISES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 103 SMALL AND MEDIUM-SIZED ENTERPRISES: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 104 SMALL AND MEDIUM-SIZED ENTERPRISES: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 105 THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 106 THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 107 BFSI: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 108 BFSI: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 109 GOVERNMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 110 GOVERNMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 111 DEFENSE & INTELLIGENCE: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 112 DEFENSE & INTELLIGENCE: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 113 HEALTHCARE: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 114 HEALTHCARE: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 115 RETAIL: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 116 RETAIL: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 117 TRAVEL, AVIATION, AND LOGISTICS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 118 TRAVEL, AVIATION, AND LOGISTICS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 119 IT, ITES, AND TELECOM: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 120 IT, ITES, AND TELECOM: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 121 ENERGY & INDUSTRIAL: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 122 ENERGY & INDUSTRIAL: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 123 MEDIA & ENTERTAINMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 124 MEDIA & ENTERTAINMENT: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 125 OTHER VERTICALS: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 126 OTHER VERTICALS: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 127 THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 128 THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 129 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 130 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 131 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 132 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 133 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 134 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 135 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 136 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 137 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 138 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 139 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 140 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 141 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 142 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 143 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 144 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 145 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 146 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 147 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 148 NORTH AMERICA: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 149 US: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 150 US: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 151 US: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 152 US: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 153 US: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 154 US: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 155 US: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 156 US: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 157 US: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 158 US: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 159 US: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 160 US: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 161 US: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 162 US: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 163 US: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 164 US: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 165 US: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 166 US: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 167 CANADA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 168 CANADA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 169 CANADA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 170 CANADA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 171 CANADA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 172 CANADA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 173 CANADA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 174 CANADA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 175 CANADA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 176 CANADA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 177 CANADA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 178 CANADA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 179 CANADA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 180 CANADA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 181 CANADA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 182 CANADA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 183 CANADA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 184 CANADA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 185 EUROPE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 186 EUROPE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 187 EUROPE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 188 EUROPE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 189 EUROPE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 190 EUROPE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 191 EUROPE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 192 EUROPE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 193 EUROPE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 194 EUROPE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 195 EUROPE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 196 EUROPE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 197 EUROPE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 198 EUROPE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 199 EUROPE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 200 EUROPE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 201 EUROPE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 202 EUROPE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 203 EUROPE: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 204 EUROPE: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 205 UK: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 206 UK: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 207 UK: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 208 UK: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 209 UK: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 210 UK: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 211 UK: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 212 UK: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 213 UK: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 214 UK: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 215 UK: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 216 UK: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 217 UK: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 218 UK: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 219 UK: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 220 UK: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 221 UK: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 222 UK: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 223 GERMANY: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 224 GERMANY: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 225 GERMANY: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 226 GERMANY: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 227 GERMANY: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 228 GERMANY: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 229 GERMANY: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 230 GERMANY: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 231 GERMANY: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 232 GERMANY: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 233 GERMANY: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 234 GERMANY: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 235 GERMANY: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 236 GERMANY: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 237 GERMANY: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 238 GERMANY: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 239 GERMANY: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 240 GERMANY: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 241 FRANCE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 242 FRANCE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 243 FRANCE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 244 FRANCE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 245 FRANCE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 246 FRANCE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 247 FRANCE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 248 FRANCE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 249 FRANCE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 250 FRANCE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 251 FRANCE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 252 FRANCE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 253 FRANCE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 254 FRANCE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 255 FRANCE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 256 FRANCE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 257 FRANCE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 258 FRANCE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 259 ITALY: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 260 ITALY: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 261 ITALY: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 262 ITALY: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 263 ITALY: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 264 ITALY: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 265 ITALY: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 266 ITALY: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 267 ITALY: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 268 ITALY: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 269 ITALY: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 270 ITALY: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 271 ITALY: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 272 ITALY: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 273 ITALY: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 274 ITALY: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 275 ITALY: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 276 ITALY: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 277 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 278 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 279 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 280 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 281 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 282 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 283 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 284 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 285 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 286 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 287 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 288 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 289 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 290 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 291 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 292 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 293 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 294 REST OF EUROPE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 295 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 296 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 297 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 298 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 299 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 300 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 301 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 302 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 303 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 304 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 305 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 306 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 307 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 308 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 309 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 310 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 311 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 312 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 313 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 314 ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 315 CHINA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 316 CHINA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 317 CHINA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 318 CHINA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 319 CHINA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 320 CHINA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 321 CHINA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 322 CHINA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 323 CHINA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 324 CHINA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 325 CHINA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 326 CHINA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 327 CHINA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 328 CHINA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 329 CHINA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 330 CHINA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 331 CHINA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 332 CHINA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 333 JAPAN: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 334 JAPAN: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 335 JAPAN: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 336 JAPAN: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 337 JAPAN: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 338 JAPAN: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 339 JAPAN: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 340 JAPAN: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 341 JAPAN: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 342 JAPAN: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 343 JAPAN: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 344 JAPAN: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 345 JAPAN: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 346 JAPAN: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 347 JAPAN: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 348 JAPAN: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 349 JAPAN: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 350 JAPAN: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 351 INDIA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 352 INDIA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 353 INDIA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 354 INDIA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 355 INDIA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 356 INDIA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 357 INDIA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 358 INDIA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 359 INDIA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 360 INDIA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 361 INDIA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 362 INDIA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 363 INDIA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 364 INDIA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 365 INDIA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 366 INDIA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 367 INDIA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 368 INDIA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 369 SINGAPORE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 370 SINGAPORE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 371 SINGAPORE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 372 SINGAPORE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 373 SINGAPORE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 374 SINGAPORE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 375 SINGAPORE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 376 SINGAPORE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 377 SINGAPORE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 378 SINGAPORE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 379 SINGAPORE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 380 SINGAPORE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 381 SINGAPORE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 382 SINGAPORE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 383 SINGAPORE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 384 SINGAPORE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 385 SINGAPORE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 386 SINGAPORE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 387 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 388 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 389 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 390 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 391 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 392 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 393 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 394 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 395 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 396 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 397 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 398 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 399 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 400 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 401 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 402 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 403 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 404 REST OF ASIA PACIFIC: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 405 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 406 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 407 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 408 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 409 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 410 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 411 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 412 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 413 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 414 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 415 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 416 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 417 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 418 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 419 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 420 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 421 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 422 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 423 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 424 MIDDLE EAST & AFRICA: THREAT INTELLIGENCE MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 425 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 426 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 427 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 428 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 429 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 430 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 431 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 432 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 433 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 434 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 435 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 436 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 437 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 438 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 439 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 440 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 441 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 442 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 443 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 444 MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 445 KSA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 446 KSA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 447 KSA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 448 KSA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 449 KSA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 450 KSA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 451 KSA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 452 KSA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 453 KSA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 454 KSA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 455 KSA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 456 KSA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 457 KSA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 458 KSA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 459 KSA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 460 KSA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 461 KSA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 462 KSA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 463 UAE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 464 UAE: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 465 UAE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 466 UAE: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 467 UAE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 468 UAE: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 469 UAE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 470 UAE: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 471 UAE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 472 UAE: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 473 UAE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 474 UAE: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 475 UAE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 476 UAE: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 477 UAE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 478 UAE: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 479 UAE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 480 UAE: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 481 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 482 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 483 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 484 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 485 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 486 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 487 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 488 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 489 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 490 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 491 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 492 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 493 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 494 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 495 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 496 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 497 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 498 REST OF MIDDLE EAST: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 499 AFRICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 500 AFRICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 501 AFRICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 502 AFRICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 503 AFRICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 504 AFRICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 505 AFRICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 506 AFRICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 507 AFRICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 508 AFRICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 509 AFRICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 510 AFRICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 511 AFRICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 512 AFRICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 513 AFRICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 514 AFRICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 515 AFRICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 516 AFRICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 517 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 518 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 519 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 520 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 521 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 522 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 523 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 524 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 525 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 526 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 527 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 528 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 529 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 530 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 531 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 532 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 533 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 534 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 535 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 536 LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 537 BRAZIL: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 538 BRAZIL: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 539 BRAZIL: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 540 BRAZIL: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 541 BRAZIL: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 542 BRAZIL: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 543 BRAZIL: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 544 BRAZIL: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 545 BRAZIL: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 546 BRAZIL: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 547 BRAZIL: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 548 BRAZIL: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 549 BRAZIL: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 550 BRAZIL: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 551 BRAZIL: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 552 BRAZIL: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 553 BRAZIL: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 554 BRAZIL: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 555 MEXICO: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 556 MEXICO: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 557 MEXICO: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 558 MEXICO: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 559 MEXICO: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 560 MEXICO: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 561 MEXICO: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 562 MEXICO: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 563 MEXICO: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 564 MEXICO: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 565 MEXICO: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 566 MEXICO: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 567 MEXICO: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 568 MEXICO: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 569 MEXICO: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 570 MEXICO: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 571 MEXICO: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 572 MEXICO: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 573 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2021-2025 (USD MILLION)
- TABLE 574 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 575 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2021-2025 (USD MILLION)
- TABLE 576 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 577 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2021-2025 (USD MILLION)
- TABLE 578 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 579 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2021-2025 (USD MILLION)
- TABLE 580 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY PROFESSIONAL SERVICE, 2026-2031 (USD MILLION)
- TABLE 581 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2021-2025 (USD MILLION)
- TABLE 582 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY MANAGED SERVICE, 2026-2031 (USD MILLION)
- TABLE 583 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 584 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 585 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2021-2025 (USD MILLION)
- TABLE 586 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY DEPLOYMENT MODE, 2026-2031 (USD MILLION)
- TABLE 587 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2021-2025 (USD MILLION)
- TABLE 588 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 589 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2021-2025 (USD MILLION)
- TABLE 590 REST OF LATIN AMERICA: THREAT INTELLIGENCE MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 591 OVERVIEW OF STRATEGIES ADOPTED BY KEY THREAT INTELLIGENCE VENDORS, 2024-2026
- TABLE 592 THREAT INTELLIGENCE MARKET: DEGREE OF COMPETITION
- TABLE 593 THREAT INTELLIGENCE MARKET: REGION FOOTPRINT
- TABLE 594 THREAT INTELLIGENCE MARKET: OFFERING FOOTPRINT
- TABLE 595 THREAT INTELLIGENCE MARKET: DEPLOYMENT MODE FOOTPRINT
- TABLE 596 THREAT INTELLIGENCE MARKET: VERTICAL FOOTPRINT
- TABLE 597 THREAT INTELLIGENCE MARKET: KEY STARTUPS/SMES
- TABLE 598 THREAT INTELLIGENCE MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- TABLE 599 THREAT INTELLIGENCE MARKET: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 600 THREAT INTELLIGENCE MARKET: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 601 PALO ALTO NETWORKS: COMPANY OVERVIEW
- TABLE 602 PALO ALTO NETWORKS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 603 PALO ALTO NETWORKS: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 604 PALO ALTO NETWORKS: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 605 CROWDSTRIKE: COMPANY OVERVIEW
- TABLE 606 CROWDSTRIKE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 607 CROWDSTRIKE: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 608 CROWDSTRIKE: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 609 IBM: COMPANY OVERVIEW
- TABLE 610 IBM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 611 IBM: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2023-AUGUST 2025
- TABLE 612 IBM: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 613 CISCO: COMPANY OVERVIEW
- TABLE 614 CISCO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 615 CISCO: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 616 CISCO: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 617 GOOGLE: COMPANY OVERVIEW
- TABLE 618 GOOGLE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 619 GOOGLE: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 620 GOOGLE: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 621 FORTINET: COMPANY OVERVIEW
- TABLE 622 FORTINET: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 623 FORTINET: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 624 FORTINET: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 625 CYBLE: BUSINESS OVERVIEW
- TABLE 626 CYBLE: PRODUCTS/SOLUTIONS/SERVICES OFFERINGS
- TABLE 627 CYBLE: PRODUCT LAUNCHES
- TABLE 628 CYBLE: DEALS
- TABLE 629 CHECK POINT: COMPANY OVERVIEW
- TABLE 630 CHECK POINT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 631 CHECK POINT: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 632 CHECK POINT: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 633 TRELLIX: COMPANY OVERVIEW
- TABLE 634 TRELLIX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 635 TRELLIX: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 636 TRELLIX: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 637 TRELLIX: EXPANSIONS, JANUARY 2024-SEPTEMBER 2026
- TABLE 638 RAPID7: COMPANY OVERVIEW
- TABLE 639 RAPID7: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 640 RAPID7: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 641 RAPID7: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 642 RECORDED FUTURE (MASTERCARD): COMPANY OVERVIEW
- TABLE 643 RECORDED FUTURE (MASTERCARD): PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 644 RECORDED FUTURE (MASTERCARD): PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 645 RECORDED FUTURE (MASTERCARD): DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 646 GROUP-IB: COMPANY OVERVIEW
- TABLE 647 GROUP-IB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 648 GROUP-IB: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 649 GROUP-IB: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 650 KASPERSKY: COMPANY OVERVIEW
- TABLE 651 KASPERSKY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 652 KASPERSKY: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
- TABLE 653 KASPERSKY: DEALS, JANUARY 2024-SEPTEMBER 2026
- TABLE 654 ANOMALI: COMPANY OVERVIEW
- TABLE 655 ANOMALI: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 656 ANOMALI: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2023-JUNE 2025
- TABLE 657 ANOMALI: DEALS, JANUARY 2023-JUNE 2025
- TABLE 658 CPX: COMPANY OVERVIEW
- TABLE 659 CPX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 660 CPX: DEALS, JANUARY 2023-JUNE 2025
- TABLE 661 KELA: COMPANY OVERVIEW
- TABLE 662 KELA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 663 KELA: PRODUCT LAUNCHES/DEVELOPMENTS, JANUARY 2023-JUNE 2025
- TABLE 664 KELA: DEALS, JANUARY 2023-JUNE 2025
- TABLE 665 SOCRADAR: COMPANY OVERVIEW
- TABLE 666 SOCRADAR: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 667 SOCRADAR: PRODUCT LAUNCHES
- TABLE 668 SOCRADAR: DEALS
- TABLE 669 FACTOR ANALYSIS
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 GLOBAL THREAT INTELLIGENCE MARKET, 2021-2031 (USD MILLION)
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN THREAT INTELLIGENCE MARKET, 2025
- FIGURE 4 DISRUPTIVE TRENDS INFLUENCING GROWTH OF THREAT INTELLIGENCE MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN THREAT INTELLIGENCE MARKET, 2026-2031
- FIGURE 6 ASIA PACIFIC TO REGISTER FASTEST GROWTH DURING FORECAST PERIOD
- FIGURE 7 RISE IN CYBERATTACKS, REGULATORY COMPLIANCE, AND DIGITAL TRANSFORMATION TO DRIVE MARKET
- FIGURE 8 SOLUTIONS SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE
- FIGURE 9 THREAT INTELLIGENCE PLATFORMS (TIPS) SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE
- FIGURE 10 FRAUD & FINANCIAL CRIME DETECTION SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE
- FIGURE 11 BFSI SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE
- FIGURE 12 ASIA PACIFIC TO EMERGE AS BEST MARKET FOR INVESTMENT IN NEXT FIVE YEARS
- FIGURE 13 THREAT INTELLIGENCE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 THREAT INTELLIGENCE MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 THREAT INTELLIGENCE MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 THREAT INTELLIGENCE MARKET: ECOSYSTEM
- FIGURE 17 AVERAGE SELLING PRICE OF THREAT INTELLIGENCE SOLUTIONS, BY KEY PLAYER, 2025
- FIGURE 18 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 19 INVESTMENTS & FUNDING IN THREAT INTELLIGENCE MARKET, 2020-2025
- FIGURE 20 NUMBER OF PATENTS GRANTED FOR THREAT INTELLIGENCE MARKET, 2016-2026
- FIGURE 21 THREAT INTELLIGENCE MARKET: REGIONAL ANALYSIS OF PATENTS GRANTED
- FIGURE 22 FUTURE APPLICATIONS OF THREAT INTELLIGENCE
- FIGURE 23 EXPORT SCENARIO FOR HS CODE 851762-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025
- FIGURE 24 IMPORT SCENARIO FOR HS CODE 851762-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025
- FIGURE 25 THREAT INTELLIGENCE MARKET: DECISION-MAKING FACTORS
- FIGURE 26 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- FIGURE 27 KEY BUYING CRITERIA FOR TOP THREE VERTICALS
- FIGURE 28 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 29 SOLUTIONS SEGMENT TO HOLD LARGER MARKET
- FIGURE 30 DIGITAL RISK PROTECTION SEGMENT TO HOLD LARGEST MARKET SHARE
- FIGURE 31 PROFESSIONAL SERVICES SEGMENT TO ACCOUNT FOR LARGER MARKET
- FIGURE 32 DESIGNING, INTEGRATION, AND DEPLOYMENT SEGMENT TO ACCOUNT FOR LARGEST MARKET
- FIGURE 33 THREAT INTELLIGENCE AS A SERVICE (TIAAS) SEGMENT TO ACCOUNT FOR LARGER MARKET
- FIGURE 34 INCIDENT RESPONSE SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 35 CLOUD SEGMENT TO ACCOUNT FOR LARGEST MARKET
- FIGURE 36 LARGE ENTERPRISES SEGMENT TO ACCOUNT FOR LARGER MARKET
- FIGURE 37 IT, ITES, AND TELECOM SEGMENT TO ACCOUNT FOR LARGEST MARKET
- FIGURE 38 ASIA PACIFIC TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 39 NORTH AMERICA: MARKET SNAPSHOT
- FIGURE 40 ASIA PACIFIC: MARKET SNAPSHOT
- FIGURE 41 REVENUE ANALYSIS OF KEY THREAT INTELLIGENCE PROVIDERS, 2021-2025 (USD MILLION)
- FIGURE 42 THREAT INTELLIGENCE MARKET SHARE ANALYSIS OF KEY VENDORS, 2025
- FIGURE 43 BRAND COMPARISON
- FIGURE 44 COMPANY VALUATION OF KEY VENDORS, 2026 (USD BILLION)
- FIGURE 45 FINANCIAL METRICS OF KEY VENDORS, 2026
- FIGURE 46 THREAT INTELLIGENCE MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 47 THREAT INTELLIGENCE MARKET: COMPANY FOOTPRINT
- FIGURE 48 THREAT INTELLIGENCE MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 49 PALO ALTO NETWORKS: COMPANY SNAPSHOT
- FIGURE 50 CROWDSTRIKE: COMPANY SNAPSHOT
- FIGURE 51 IBM: COMPANY SNAPSHOT
- FIGURE 52 CISCO: COMPANY SNAPSHOT
- FIGURE 53 GOOGLE: COMPANY SNAPSHOT
- FIGURE 54 FORTINET: COMPANY SNAPSHOT
- FIGURE 55 CHECK POINT: COMPANY SNAPSHOT
- FIGURE 56 RAPID7: COMPANY SNAPSHOT
- FIGURE 57 THREAT INTELLIGENCE MARKET: RESEARCH DESIGN
- FIGURE 58 THREAT INTELLIGENCE MARKET: DATA TRIANGULATION
- FIGURE 59 THREAT INTELLIGENCE MARKET: RESEARCH FLOW
- FIGURE 60 MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 1 (SUPPLY SIDE) - REVENUE OF SOLUTIONS/SERVICES OF THREAT INTELLIGENCE VENDORS
- FIGURE 61 MARKET SIZE ESTIMATION METHODOLOGY: SUPPLY-SIDE ANALYSIS
- FIGURE 62 MARKET SIZE ESTIMATION METHODOLOGY FOR SOLUTIONS/SERVICES: APPROACH 1, BOTTOM-UP (DEMAND SIDE)
- FIGURE 63 MARKET SIZE ESTIMATION METHODOLOGY-APPROACH 2, BOTTOM-UP (SUPPLY SIDE): COLLECTIVE REVENUE FROM ALL SOLUTIONS AND SERVICES

 威脅情報市場預測至 2034 年——按組件、類型、部署模式、組織規模、應用、最終用戶和地區分類的全球分析
 醫療語意智慧市場:按組件、技術、應用、最終用戶和地區分類
 威脅情報市場規模、佔有率、成長率及全球產業分析、區域趨勢及2026年至2034年預測
 威脅情報市場:依組件、威脅情報類型、應用、部署模式和組織規模分類-2026-2032年全球市場預測
 威脅建模工具:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)威脅情報:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 威脅建模工具市場規模、佔有率和趨勢分析報告:按組件、部署類型、企業規模、行業、地區和細分市場預測(2026-2033 年)
 威脅建模工具市場分析及預測(至 2035 年):類型、產品類型、服務、技術、組件、應用、部署模式、最終用戶、功能、解決方案威脅情報市場分析及預測(至 2035 年):類型、產品類型、服務、技術、組件、應用、部署模式、最終用戶、解決方案、交付模式
 2026年全球人工智慧驅動威脅情報市場報告