


 |
市場調查報告書
商品編碼
2126792
全球排煙脫硫(FGD)系統市場(至2031年):按類型(濕式FGD系統、乾式和半乾式FGD系統)、部署方式(待開發區和棕地)、終端用戶行業(發電、化工和石化)及地區分類Flue Gas Desulfurization System Market by Type (Wet FGD Systems, Dry & Semi-Dry FGD Systems), Installation (Greenfield, Brownfield), End-Use Industry (Power Generation, Chemicals & Petrochemicals), and Region - Global Forecast To 2031 |
||||||

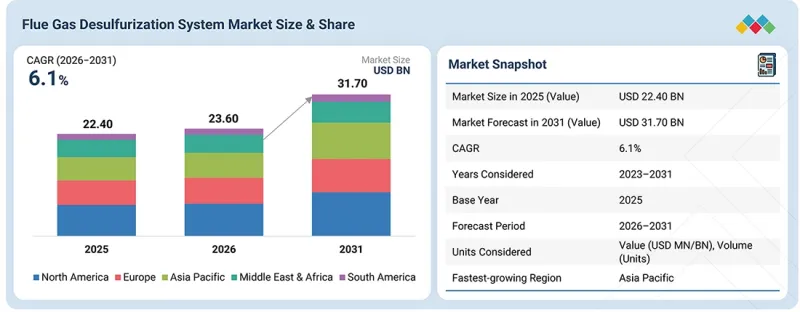
全球排煙脫硫(FGD)系統市場預計將從 2026 年的 236 億美元成長到 2031 年的 317 億美元,預計在預測期內將以 6.1% 的複合年成長率成長。
市場成長的驅動力來自燃煤電廠、水泥製造廠和工業鍋爐等行業對符合排放標準的廢氣處理系統日益成長的需求。除了日益嚴格的二氧化硫排放標準帶來的壓力外,開發中國家持續依賴煤炭作為基本負載能源也為市場成長創造了機會。
| 調查範圍 | |
|---|---|
| 調查期 | 2023-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 單元 | 金額(美元) 數量(單位) |
| 部分 | 類型、部署方式、最終用戶產業 |
| 目標區域 | 北美洲、亞太地區、歐洲、中東和非洲、南美洲 |
從一開始就配備排煙脫硫(FGD) 設施的新建燃煤發電廠建設速度加快,加上針對現有電廠的大規模維修計劃,進一步推動了市場發展勢頭。
“從 2026 年到 2031 年,乾式和半乾式煙氣脫硫系統領域預計將呈現最高的複合年成長率。”
此領域的成長歸因於諸多因素,例如與濕式煙氣脫硫系統相比,其用水量更低、廢棄物處理更簡單、輔助電力需求更低。這些系統正擴大應用於水資源有限的地區以及希望在不安裝濕式洗滌器所需大型基礎設施的情況下確保可靠脫除二氧化硫的小規模設施中。尤其是在乾旱或缺水地區運作的燃煤發電廠、工業鍋爐和水泥窯,由於乾式和半乾式系統所需的資本投入相對較低、廢水處理需求少且易於整合到現有設施中,因此正擴大採用這些系統。此外,乾式和半乾式系統可以採用小規模模組化配置,為那些難以透過濕式煙氣脫硫系統實現規模經濟的中型工業排放企業提供了更大的設計柔軟性。
“預計到2031年,發電領域將佔據最大的市場佔有率。”
從終端用戶產業來看,預計到2031年,發電業將佔最大佔有率,這主要是因為亞太、歐洲和北美部分地區嚴重依賴燃煤發電廠提供基本負載電力。燃煤發電廠高度依賴煙氣脫硫(FGD)系統來達到二氧化硫(SO2)排放標準,避免受到監管處罰和強制減產。煤炭依賴型經濟體發電能力的提升、超低排放標準執行力度的加強以及對人口密集區附近工業區空氣品質監測的強化,都推動了發電業對煙氣脫硫系統的需求。此外,全球整體燃煤電廠的龐大規模,以及各國分階段運作的強制性維修,也支撐了發電業佔最大佔有率。
“在預測期內,歐洲有望成為全球市場第二大地區。”
預計在2026年至2031年間,歐洲將佔據第二大市場佔有率,這得益於其長期以來完善的大型燃燒設施和工業排放監管制度框架。該地區擁有多家主要的煙氣脫硫(FGD)系統和排放氣體控制設備製造商,這些製造商在先進脫硫技術領域保持著創新活力和強大的供應鏈。工業排放指令和最佳技術(BAT)標準的嚴格執行、剩餘燃煤電廠持續的監管合規義務,以及煙氣脫硫相關監管合規要求擴展至非歐盟的東南歐市場,都在推動著區域市場的發展。另一方面,由於歐洲燃煤電廠老化且產能逐漸萎縮,預計歐洲市場的成長速度將低於亞太地區。
本報告考察了全球排煙脫硫(FGD)系統市場,提供了市場概述、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、歷史和預測市場規模、按細分市場/地區/主要國家/地區進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求
- 閒置頻段的機遇
- 與相關市場和不同產業相關的跨領域機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 價值鏈分析
- 生態系分析
- 價格分析
- 宏觀經濟展望
- 全球GDP趨勢
- 美國關稅對排煙脫硫系統市場的影響
- 貿易分析
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 2026-2027 年主要會議和活動
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要技術
- 互補技術
- 技術/產品藍圖
- 短期(2025-2027 年)| 系統效率提升與數位化監控
- 中期規劃(2027-2030年)| 智慧排煙脫硫系統及資源最佳化
- 長期(2030 年及以後)| 自主式、低資源消耗、一體化排煙脫硫系統
- 專利分析
- 未來應用
- 先進的濕式煙氣脫硫系統和高效二氧化硫去除
- 適用於水資源受限環境的乾式和半乾式煙氣脫硫系統
- 人工智慧驅動的煙氣脫硫製程最佳化和預測控制
- 先進的石膏回收、廢水處理和資源管理。
- 多種污染物的綜合控制和數位化排放監測
- 人工智慧/生成式人工智慧對排煙脫硫設備市場的影響
第7章:監理情勢與永續性舉措
- 當地法規和合規性
- 監理政策對永續性舉措的影響
- 認證、標籤檢視、環境標準
第8章:顧客趨勢與購買行為
- 決策流程
- 參與採購流程的關鍵相關人員及其採購標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第9章排煙脫硫(FGD)系統市場:按類型分類
- 濕式煙氣脫硫系統
- 石灰石
- 海水
- 其他
- 乾式和半乾式煙氣脫硫系統
第10章排煙脫硫(FGD)系統市場:依安裝方式分類
- 待開發區
- 棕地
第11章排煙脫硫(FGD)系統市場:依應用領域分類
- 發電
- 化學
- 鋼
- 水泥製造
- 其他
第12章排煙脫硫(FGD)系統市場:依地區分類
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 其他
- 南美洲
- 巴西
- 阿根廷
- 其他
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他
- 中東和非洲
- GCC
- 其他
第13章 競爭格局
- 概述
- 主要公司/領先公司的競爭策略
- 收入分析
- 市佔率分析
- 產品對比
- 三菱重工(排煙脫硫(FGD))
- 企業估值矩陣:主要公司
- 公司估值矩陣:新創企業/中小企業
- 企業估值和財務指標
- 競爭格局
第14章:公司簡介
- 大公司
- MITSUBISHI HEAVY INDUSTRIES, LTD.
- GE VERNOVA
- DOOSAN LENTJES
- BABCOCK & WILCOX ENTERPRISES, INC.
- ANDRITZ
- VALMET
- KAWASAKI HEAVY INDUSTRIES, LTD.
- BHARAT HEAVY ELECTRICALS LIMITED
- LONGKING ENVIRONMENTAL PROTECTION
- KC COTTRELL
- 其他公司
- THERMAX LIMITED
- MET
- DUCON
- CHIYODA CORPORATION
- CHINA BOQI ENVIRONMENTAL (HOLDING) CO., LTD
- MACROTEK INC.
- RUDRIS
- STEINMULLER ENGINEERING GMBH
- BAOLAN EP INC.
- TSUKISHIMA KIKAI CO., LTD.
- WUHAN KAIDI ELECTRIC POWER ENVIRONMENTAL CO., LTD.
- RIECO INDUSTRIES LIMITED
- ACMEFIL ENGINEERING SYSTEMS PVT LTD.
- TNBI INDUSTRIES PVT. LTD.
- ERGIL
第15章:調查方法
第16章附錄
The global flue gas desulfurization system market is anticipated to be valued at USD 23.60 billion in 2026 and USD 31.70 billion by 2031, registering a CAGR of 6.1% during the forecast period. Rising demand for compliant emission-control systems across coal-fired power generation, cement manufacturing, and industrial boilers is driving the market. The mounting pressure to meet stringent SO2 emission norms and the continued reliance on coal as a baseload fuel source in developing economies create market growth opportunities.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion), Volume (Units) |
| Segments | Type, Installation, and End-use Industry |
| Regions covered | North America, Asia Pacific, Europe, the Middle East & Africa, and South America |
Furthermore, the increasing pace of new-build coal capacity equipped with flue gas desulfurization (FGD) from inception, combined with large-scale retrofit programs targeting existing thermal power fleets, also adds to the momentum of the market.
"Dry & semi-dry FGD systems segment to exhibit the highest CAGR from 2026 to 2031"
In terms of type, the dry & semi-dry FGD systems segment is anticipated to be the fastest-growing in the flue gas desulfurization system market during the forecast period. The segmental growth is attributed to its lower water consumption, simpler waste handling, and reduced auxiliary power requirements compared with wet FGD systems. These systems are increasingly embraced in water-constrained regions and smaller-capacity installations seeking reliable SO2 control without the infrastructure burden of wet scrubbing. Coal-fired power plants, industrial boilers, and cement kilns operating in arid or water-stressed geographies are among the key adopters of these systems, owing to their lower capital footprint, reduced wastewater treatment needs, and simpler retrofit integration. In addition, dry & semi-dry systems can be deployed in smaller, modular configurations, offering design flexibility for mid-sized industrial emitters that wet FGD's scale economics do not favor.
"Power generation segment to account for the largest market share in 2031"
In terms of end-use industry, the power generation segment is projected to capture the largest share of the flue gas desulfurization system market in 2031, owing to the extensive reliance on coal-fired plants for baseload electricity across Asia Pacific, Europe, and parts of North America. Coal-based thermal power stations heavily depend on FGD systems to maintain compliance with SO2 emission standards and avoid regulatory penalties or forced curtailment. Increasing capacity additions in coal-dependent economies, rising enforcement of ultra-low-emission mandates, and growing scrutiny of ambient air quality near densely populated industrial corridors augment the demand for FGD in the power generation industry. Moreover, the sheer scale of the installed coal power fleet globally, combined with the phased nature of national retrofit mandates, solidifies the leadership of the segment.
"Europe to be the second-largest region in the global market during the forecast period"
In terms of region, Europe is anticipated to hold the second-largest share of the flue gas desulfurization system market between 2026 and 2031 due to its long-established regulatory framework governing large combustion plants and industrial emissions. The region houses several prominent manufacturers of FGD systems and emission-control equipment, hence sustaining innovation and supply-chain depth in advanced desulfurization technologies. Strict enforcement of Industrial Emissions Directive and Best Available Techniques standards, continued compliance obligations on the remaining coal fleet, and extension of FGD-accession compliance into non-EU Southeastern European markets are driving the regional market, even as Europe's aging and gradually shrinking coal capacity tempers the pace of forward growth relative to Asia Pacific.
Breakdown of Primary Interviews:
By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
By Designation: Directors: 30%, Managers: 20%, and Others: 50%
By Region: North America: 20%, Europe: 10%, Asia Pacific: 40%, South America: 10%, and Middle East & Africa: 20%
Notes: Others include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million-1 Billion; and Tier 3: <USD 500 million
Companies Covered: Mitsubishi Heavy Industries, Ltd. (Japan), GE Vernova (US), Doosan Lentjes (Germany), Babcock & Wilcox Enterprises, Inc. (US), ANDRITZ (Austria), Valmet (Finland), Kawasaki Heavy Industries, Ltd. (Japan), Bharat Heavy Electricals Limited (India), Longking Environmental Protection (China), and KC Cottrell (South Korea), among others, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the flue gas desulfurization system market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the flue gas desulfurization system market based on type (wet FGD systems and dry & semi-dry FGD systems), installation (greenfield and brownfield), and end-use industry (power generation, cement manufacturing, iron & steel, chemicals & petrochemicals, and other end-use industries). The report's scope covers detailed information regarding drivers, restraints, challenges, and opportunities influencing the market growth. A detailed analysis of the key industry players has been done to provide insights into their business overviews, products offered, and key strategies, such as mergers, acquisitions, product launches, and expansions, associated with the market. This report covers a competitive analysis of upcoming startups in the flue gas desulfurization system ecosystem.
Reasons to Buy the Report
The report will offer the market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall flue gas desulfurization system market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will also help stakeholders understand the pulse of the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
- Analysis of key drivers (Stringent environmental regulations to reduce sulfur dioxide (SO2) emission, Growing retrofit installations in aging thermal power plants, Increasing investments in coal-fired power plants in emerging economies), restraints (High capital investment and operating costs, Declining coal-fired power generation in developed economies), opportunities (Expansion of emission control investments in emerging economies, Modernization and digitalization of emission control systems), and challenges (Managing FGD by-products and wastewater, Balancing emission compliance with global energy transition)
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the flue gas desulfurization system market
- Market Development: Comprehensive information about profitable markets (the report analyzes the market across varied regions)
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players such as Mitsubishi Heavy Industries, Ltd. (Japan), GE Vernova (US), Doosan Lentjes (Germany), Babcock & Wilcox Enterprises, Inc. (US), ANDRITZ (Austria), Valmet (Finland), Kawasaki Heavy Industries, Ltd. (Japan), Bharat Heavy Electricals Limited (India), Longking Environmental Protection (China), and KC Cottrell (South Korea), among others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNIT CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN FGD SYSTEMS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN THE FGD SYSTEMS MARKET
- 3.2 FGD SYSTEMS MARKET, BY TYPE
- 3.3 FGD SYSTEMS MARKET, BY INSTALLATION
- 3.4 FGD SYSTEMS MARKET, BY END-USE INDUSTRY
- 3.5 FGD SYSTEMS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Enforcement of stringent environmental regulations to reduce sulfur dioxide emissions
- 4.2.1.2 Growing demand for FGD retrofits in aging thermal power plants
- 4.2.1.3 Expansion of coal-fired power capacity in emerging economies
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital investment and operating costs of FGD systems
- 4.2.2.2 Declining coal-fired power generation in developed economies
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing environmental compliance investments across emerging economies
- 4.2.3.2 Escalating need for modernization and digitalization of emission control systems
- 4.2.4 CHALLENGES
- 4.2.4.1 Effective management of FGD byproducts and wastewater
- 4.2.4.2 Tension between stringent SO2 compliance with transition toward lower carbon energy
- 4.2.5 UNMET NEEDS IN FGD SYSTEMS MARKET
- 4.2.6 WHITE SPACE OPPORTUNITIES
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.3.1 INTERCONNECTED/ADJACENT MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.4.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 VALUE CHAIN ANALYSIS
- 5.2.1 RAW MATERIAL & COMPONENT SUPPLIERS
- 5.2.2 FGD SYSTEM MANUFACTURERS/TECHNOLOGY PROVIDERS
- 5.2.3 EPC, ENGINEERING, AND SERVICE PROVIDERS
- 5.2.4 END USERS
- 5.3 ECOSYSTEM ANALYSIS
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE SELLING PRICE TREND OF OF FGD SYSTEMS, BY REGION
- 5.4.2 PRICING TREND OF FGD SYSTEMS, BY TYPE, 2023-2025
- 5.5 MACROECONOMIC OUTLOOK
- 5.5.1 GLOBAL GDP TRENDS
- 5.6 IMPACT OF US TARIFFS ON FGD SYSTEMS MARKET
- 5.6.1 INTRODUCTION
- 5.6.2 KEY TARIFF RATES
- 5.6.3 PRICE IMPACT ANALYSIS
- 5.6.4 IMPACT ON COUNTRIES/REGIONS
- 5.6.4.1 US
- 5.6.4.2 Europe
- 5.6.4.3 Asia Pacific
- 5.6.5 IMPACT ON END-USE INDUSTRIES
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 842139)
- 5.7.2 EXPORT SCENARIO (HS CODE 842139)
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 MACROTEK INC. IMPLEMENTS HYDROGEN PEROXIDE-BASED FGD SYSTEM FOR SO2 REMOVAL AND SULPHURIC ACID PRODUCTION
- 5.10.2 THERMAX COMMISSIONS FGD SYSTEM FOR COAL-BASED POWER PLANT
- 5.10.3 BABCOCK & WILCOX IMPLEMENTS WET FGD SYSTEMS AT MITCHELL STATION
- 5.11 KEY CONFERENCES AND EVENTS, 2026-2027
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Advanced wet limestone-gypsum flue gas desulfurization systems
- 6.1.1.2 Dry and semi-dry flue gas desulfurization systems
- 6.1.1.3 AI-enabled FGD systems for process optimization and predictive control
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Advanced gypsum dewatering and byproduct recovery systems
- 6.1.2.2 Advanced flue gas monitoring, sensors, and emissions control systems
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT TERM (2025-2027) | SYSTEM EFFICIENCY & DIGITAL MONITORING
- 6.2.2 MID-TERM (2027-2030) | SMART FGD SYSTEMS & RESOURCE OPTIMIZATION
- 6.2.3 LONG TERM (2030-2030+) | AUTONOMOUS, LOW-RESOURCE & INTEGRATED FGD SYSTEMS
- 6.3 PATENT ANALYSIS
- 6.3.1 LEGAL STATUS OF PATENTS
- 6.3.2 JURISDICTION ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 ADVANCED WET FGD SYSTEMS AND HIGH-EFFICIENCY SO2 REMOVAL
- 6.4.2 DRY & SEMI-DRY FGD SYSTEMS FOR WATER-CONSTRAINED APPLICATIONS
- 6.4.3 AI-ENABLED FGD PROCESS OPTIMIZATION AND PREDICTIVE CONTROL
- 6.4.4 ADVANCED GYPSUM RECOVERY, WASTEWATER TREATMENT, AND RESOURCE MANAGEMENT
- 6.4.5 INTEGRATED MULTI-POLLUTANT CONTROL AND DIGITAL EMISSION MONITORING
- 6.5 IMPACT OF AI/GEN AI ON FGD SYSTEMS MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL OF FGD SYSTEMS
- 6.5.2 BEST PRACTICES FOLLOWED BY PLAYERS IN FGD SYSTEMS MARKET
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN FGD SYSTEMS MARKET
- 6.5.4 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN FGD SYSTEMS MARKET
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.5 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.6 MARKET PROFITABILITY
- 8.6.1 REVENUE POTENTIAL
- 8.6.2 COST DYNAMICS
- 8.6.3 MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES
9 FGD SYSTEMS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 WET FGD SYSTEMS
- 9.2.1 HIGH SULFUR DIOXIDE REMOVAL EFFICIENCY AND LOW OPERATING COST TO BOOST ADOPTION
- 9.2.2 LIMESTONE
- 9.2.3 SEAWATER
- 9.2.4 OTHER WET FGD SYSTEMS
- 9.3 DRY & SEMI-DRY FGD SYSTEMS
- 9.3.1 GROWING USE IN CEMENT, IRON & STEEL MANUFACTURING, AND GAS-FIRED POWER PLANTS TO FUEL SEGMENTAL GROWTH
10 FGD SYSTEMS MARKET, BY INSTALLATION
- 10.1 INTRODUCTION
- 10.2 GREENFIELD
- 10.2.1 DESIGN FLEXIBILITY AND EASIER EMISSION COMPLIANCE IN NEW PLANTS TO SUPPORT SEGMENTAL GROWTH
- 10.3 BROWNFIELD
- 10.3.1 AGING FGD ASSETS AND PLANT LIFE-EXTENSION PROGRAMS TO BOOST BROWNFIELD UPGRADES
11 FGD SYSTEMS MARKET, BY END-USE INDUSTRY
- 11.1 INTRODUCTION
- 11.2 POWER GENERATION
- 11.2.1 SHIFT FROM NEW INSTALLATIONS TO RETROFITS AND UPGRADES IN CHINA TO SHAPE SEGMENTAL DEMAND
- 11.3 CHEMICALS
- 11.3.1 CHEMICAL PROCESSING CAPACITY EXPANSION IN ASIA PACIFIC AND MIDDLE EAST TO CREATE GREENFIELD AND RETROFIT OPPORTUNITIES
- 11.4 IRON & STEEL
- 11.4.1 ULTRA-LOW-EMISSION MANDATES IN CHINA'S STEEL INDUSTRY TO ACCELERATE DESULFURIZATION UPGRADES
- 11.5 CEMENT MANUFACTURING
- 11.5.1 STRINGENT KILN EMISSION STANDARDS AND PLANT MODERNIZATION EFFORTS TO FOSTER SEGMENTAL GROWTH
- 11.6 OTHER END-USE INDUSTRIES
12 FGD SYSTEMS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 US
- 12.2.1.1 Stringent environmental regulations and continued investment in emission control infrastructure to support demand
- 12.2.2 CANADA
- 12.2.2.1 Stringent environmental standards and modernization of power and industrial infrastructure to support market growth
- 12.2.3 MEXICO
- 12.2.3.1 Industrial modernization and environmental regulations to fuel market growth
- 12.2.1 US
- 12.3 EUROPE
- 12.3.1 GERMANY
- 12.3.1.1 Strong industrial base and stringent emission control requirements to facilitate market growth
- 12.3.2 FRANCE
- 12.3.2.1 Continued industrial activity and brownfield projects to stimulate market growth
- 12.3.3 UK
- 12.3.3.1 Stringent emission standards and established industrial base to contribute to market growth
- 12.3.4 ITALY
- 12.3.4.1 Rising need for brownfield retrofits and established cement industry to boost demand
- 12.3.5 SPAIN
- 12.3.5.1 Emphasis on industrial decarbonization, energy efficiency, renewable energy to accelerate market growth
- 12.3.6 REST OF EUROPE
- 12.3.1 GERMANY
- 12.4 SOUTH AMERICA
- 12.4.1 BRAZIL
- 12.4.1.1 Established thermal power capacity to drive market
- 12.4.2 ARGENTINA
- 12.4.2.1 Thermal power generation efforts to create growth opportunities
- 12.4.3 REST OF SOUTH AMERICA
- 12.4.1 BRAZIL
- 12.5 ASIA PACIFIC
- 12.5.1 CHINA
- 12.5.1.1 Strong focus on air-pollution reduction and cleaner industrial production to drive market
- 12.5.2 JAPAN
- 12.5.2.1 Brownfield modernization initiatives to create growth opportunities
- 12.5.3 INDIA
- 12.5.3.1 Make in India, industrial corridors, and infrastructure development initiatives to foster market growth
- 12.5.4 SOUTH KOREA
- 12.5.4.1 Aging industrial infrastructure and stringent emission control requirements to contribute to market growth
- 12.5.5 REST OF ASIA PACIFIC
- 12.5.1 CHINA
- 12.6 MIDDLE EAST & AFRICA
- 12.6.1 GCC
- 12.6.1.1 Saudi Arabia
- 12.6.1.1.1 Large oil & gas and refining base, expanding petrochemical and industrial capacity to support market growth
- 12.6.1.2 UAE
- 12.6.1.2.1 Expanding oil & gas, petrochemical, power generation, and water infrastructure to support market growth
- 12.6.1.3 Rest of GCC
- 12.6.1.4 South Africa
- 12.6.1.4.1 Aging coal-fired power infrastructure and stringent emission-control requirements to drive demand
- 12.6.1.1 Saudi Arabia
- 12.6.2 REST OF MIDDLE EAST & AFRICA
- 12.6.1 GCC
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER COMPETITIVE STRATEGIES/ RIGHT TO WIN, 2022-2026
- 13.3 REVENUE ANALYSIS, 2021-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.4.1 MITSUBISHI HEAVY INDUSTRIES, LTD.
- 13.4.2 LONGKING ENVIRONMENTAL PROTECTION
- 13.4.3 BHARAT HEAVY ELECTRICALS LIMITED
- 13.4.4 DOOSAN LENTJES
- 13.4.5 BABCOCK & WILCOX ENTERPRISES, INC.
- 13.5 PRODUCT COMPARISON
- 13.6 MITSUBISHI HEAVY INDUSTRIES. (FLUE GAS DESULFURIZATION (FGD))
- 13.6.1 GE VERNOVA (WET & DRY FGD SOLUTIONS)
- 13.6.2 DOOSAN LENTJES (FGD SYSTEM)
- 13.6.3 BABCOCK & WILCOX (WET SCRUBBER FGD)
- 13.6.4 ANDRITZ (MULTI-STAGE FLUE GAS CLEANING SYSTEMS)
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.5.2 Region footprint
- 13.7.5.3 Type footprint
- 13.7.5.4 Installation footprint
- 13.7.5.5 End-use industry footprint
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.5.2 Competitive benchmarking of key startups/SMEs
- 13.9 COMPANY VALUATION AND FINANCIAL METRICS
- 13.9.1 FINANCIAL METRICS
- 13.9.2 COMPANY VALUATION
- 13.10 COMPETITIVE SCENARIO
- 13.10.1 DEALS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 MITSUBISHI HEAVY INDUSTRIES, LTD.
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 MnM view
- 14.1.1.3.1 Right to win
- 14.1.1.3.2 Strategic choices
- 14.1.1.3.3 Weaknesses and competitive threats
- 14.1.2 GE VERNOVA
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 MnM view
- 14.1.2.3.1 Right to win
- 14.1.2.3.2 Strategic choices
- 14.1.2.3.3 Weaknesses and competitive threats
- 14.1.3 DOOSAN LENTJES
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 MnM view
- 14.1.3.3.1 Right to win
- 14.1.3.3.2 Strategic choices
- 14.1.3.3.3 Weaknesses and competitive threats
- 14.1.4 BABCOCK & WILCOX ENTERPRISES, INC.
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Deals
- 14.1.4.4 MnM view
- 14.1.4.4.1 Right to win
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 ANDRITZ
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Deals
- 14.1.5.4 MnM view
- 14.1.5.4.1 Right to win
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 VALMET
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 MnM view
- 14.1.7 KAWASAKI HEAVY INDUSTRIES, LTD.
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 MnM view
- 14.1.8 BHARAT HEAVY ELECTRICALS LIMITED
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 MnM view
- 14.1.9 LONGKING ENVIRONMENTAL PROTECTION
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.9.3 MnM view
- 14.1.10 KC COTTRELL
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 MnM view
- 14.1.1 MITSUBISHI HEAVY INDUSTRIES, LTD.
- 14.2 OTHER PLAYERS
- 14.2.1 THERMAX LIMITED
- 14.2.2 MET
- 14.2.3 DUCON
- 14.2.4 CHIYODA CORPORATION
- 14.2.5 CHINA BOQI ENVIRONMENTAL (HOLDING) CO., LTD
- 14.2.6 MACROTEK INC.
- 14.2.7 RUDRIS
- 14.2.8 STEINMULLER ENGINEERING GMBH
- 14.2.9 BAOLAN EP INC.
- 14.2.10 TSUKISHIMA KIKAI CO., LTD.
- 14.2.11 WUHAN KAIDI ELECTRIC POWER ENVIRONMENTAL CO., LTD.
- 14.2.12 RIECO INDUSTRIES LIMITED
- 14.2.13 ACMEFIL ENGINEERING SYSTEMS PVT LTD.
- 14.2.14 TNBI INDUSTRIES PVT. LTD.
- 14.2.15 ERGIL
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.1.2 List of key secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.2.3 Breakdown of primary interviews
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 DATA TRIANGULATION
- 15.4 STUDY ASSUMPTIONS
- 15.5 RESEARCH LIMITATIONS AND RISK ANALYSIS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS
List of Tables
- TABLE 1 STUDY INCLUSIONS AND EXCLUSIONS
- TABLE 2 SUMMARY OF CHANGES
- TABLE 3 FGD SYSTEMS MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 4 ROLES OF COMPANIES IN ECOSYSTEM
- TABLE 5 AVERAGE SELLING PRICE TREND OF FGD SYSTEMS, BY REGION, 2023-2025 (USD MILLION/UNIT)
- TABLE 6 AVERAGE SELLING PRICE TREND OF FGD SYSTEM TYPES, 2023-2025 (USD MILLION/UNIT)
- TABLE 7 GDP TRENDS AND FORECAST OF MAJOR ECONOMIES, 2023-2030 (USD BILLION)
- TABLE 8 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 9 IMPORT DATA FOR HS CODE 842139-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 10 EXPORT SCENARIO FOR HS CODE 842139-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 FGD SYSTEMS MARKET: CONFERENCES & EVENTS, 2026-2027
- TABLE 12 TOP USE CASES AND MARKET POTENTIAL
- TABLE 13 BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES
- TABLE 14 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 15 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS
- TABLE 16 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS
- TABLE 17 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS
- TABLE 18 SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS
- TABLE 19 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, INDUSTRY ASSOCIATIONS, AND OTHER ORGANIZATIONS
- TABLE 20 GLOBAL STANDARDS IN FGD SYSTEMS MARKET
- TABLE 21 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN FGD SYSTEMS MARKET
- TABLE 22 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY END-USE INDUSTRIES (%)
- TABLE 23 KEY BUYING CRITERIA FOR KEY END-USE INDUSTRIES
- TABLE 24 FGD SYSTEMS MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES
- TABLE 25 FGD: AVAILABLE TECHNOLOGIES
- TABLE 26 WET FGD SYSTEMS VS. DRY & SEMI-DRY FGD SYSTEMS
- TABLE 27 FGD CLASSIFICATION AND CO-PRODUCTS BASED ON FGD PROCESS
- TABLE 28 FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 29 FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 30 FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 31 FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 32 FGD SYSTEMS MARKET, BY INSTALLATION, 2023-2025 (USD MILLION)
- TABLE 33 FGD SYSTEMS MARKET, BY INSTALLATION, 2026-2031 (USD MILLION)
- TABLE 34 FGD SYSTEMS MARKET, BY INSTALLATION, 2023-2025 (UNITS)
- TABLE 35 FGD SYSTEMS MARKET, BY INSTALLATION, 2026-2031 (UNITS)
- TABLE 36 FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 37 FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 38 FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 39 FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 40 FGD SYSTEMS MARKET, BY REGION, 2023-2025 (USD MILLION)
- TABLE 41 FGD SYSTEMS MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 42 FGD SYSTEMS MARKET, BY REGION, 2023-2025 (UNITS)
- TABLE 43 FGD SYSTEMS MARKET, BY REGION, 2026-2031 (UNITS)
- TABLE 44 NORTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 45 NORTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 46 NORTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (UNITS)
- TABLE 47 NORTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (UNITS)
- TABLE 48 NORTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 49 NORTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 50 NORTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 51 NORTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 52 NORTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 53 NORTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 54 NORTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 55 NORTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 56 US: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 57 US: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 58 US: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 59 US: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 60 CANADA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 61 CANADA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 62 CANADA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 63 CANADA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 64 MEXICO: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 65 MEXICO: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 66 MEXICO: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 67 MEXICO: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 68 EUROPE: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 69 EUROPE: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 70 EUROPE: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (UNITS)
- TABLE 71 EUROPE: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (UNITS)
- TABLE 72 EUROPE: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 73 EUROPE: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 74 EUROPE: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 75 EUROPE: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 76 EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 77 EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 78 EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 79 EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 80 GERMANY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 81 GERMANY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 82 GERMANY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 83 GERMANY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 84 FRANCE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 85 FRANCE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 86 FRANCE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 87 FRANCE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 88 UK: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 89 UK: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 90 UK: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 91 UK: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 92 ITALY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 93 ITALY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 94 ITALY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 95 ITALY: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 96 SPAIN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 97 SPAIN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 98 SPAIN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 99 SPAIN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 100 REST OF EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 101 REST OF EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 102 REST OF EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 103 REST OF EUROPE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 104 SOUTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 105 SOUTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 106 SOUTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (UNITS)
- TABLE 107 SOUTH AMERICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (UNITS)
- TABLE 108 SOUTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 109 SOUTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 110 SOUTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 111 SOUTH AMERICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 112 SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 113 SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 114 SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 115 SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 116 BRAZIL: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 117 BRAZIL: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 118 BRAZIL: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 119 BRAZIL: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 120 ARGENTINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 121 ARGENTINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 122 ARGENTINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 123 ARGENTINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 124 REST OF SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 125 REST OF SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 126 REST OF SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 127 REST OF SOUTH AMERICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 128 ASIA PACIFIC: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 129 ASIA PACIFIC: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 130 ASIA PACIFIC: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (UNITS)
- TABLE 131 ASIA PACIFIC: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (UNITS)
- TABLE 132 ASIA PACIFIC: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 133 ASIA PACIFIC: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 134 ASIA PACIFIC: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 135 ASIA PACIFIC: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 136 ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 137 ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 138 ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 139 ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 140 CHINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 141 CHINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 142 CHINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 143 CHINA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 144 JAPAN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 145 JAPAN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 146 JAPAN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 147 JAPAN: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 148 INDIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 149 INDIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 150 INDIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 151 INDIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 152 SOUTH KOREA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 153 SOUTH KOREA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 154 SOUTH KOREA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 155 SOUTH KOREA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 156 REST OF ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 157 REST OF ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 158 REST OF ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 159 REST OF ASIA PACIFIC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 160 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 161 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 162 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY COUNTRY, 2023-2025 (UNITS)
- TABLE 163 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY COUNTRY, 2026-2031 (UNITS)
- TABLE 164 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 165 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 166 MIDDLES EAST & AFRICA: FGD SYSTEMS MARKET, BY TYPE, 2023-2025 (UNITS)
- TABLE 167 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY TYPE, 2026-2031 (UNITS)
- TABLE 168 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 169 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 170 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 171 MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 172 GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 173 GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 174 GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 175 GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 176 SAUDI ARABIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 177 SAUDI ARABIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 178 SAUDI ARABIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 179 SAUDI ARABIA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 180 UAE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 181 UAE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 182 UAE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 183 UAE: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 184 REST OF GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 185 REST OF GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 186 REST OF GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 187 REST OF GCC: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 188 SOUTH AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 189 SOUTH AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 190 SOUTH AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 191 SOUTH AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 192 REST OF MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (USD MILLION)
- TABLE 193 REST OF MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (USD MILLION)
- TABLE 194 REST OF MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2023-2025 (UNITS)
- TABLE 195 REST OF MIDDLE EAST & AFRICA: FGD SYSTEMS MARKET, BY END-USE INDUSTRY, 2026-2031 (UNITS)
- TABLE 196 KEY STRATEGIES ADOPTED BY MAJOR PLAYERS IN FGD SYSTEMS MARKET, JANUARY 2022-JULY 2026
- TABLE 197 FGD SYSTEMS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 198 FGD SYSTEMS MARKET: REGION FOOTPRINT
- TABLE 199 FGD SYSTEMS MARKET: TYPE FOOTPRINT
- TABLE 200 FGD SYSTEMS MARKET: INSTALLATION FOOTPRINT
- TABLE 201 FGD SYSTEMS MARKET: END-USE INDUSTRY FOOTPRINT
- TABLE 202 FLUE GAS DESULFURIZATION SYSTEM MARKET: DETAILED LIST OF KEY STARTUPS/SME PLAYERS
- TABLE 203 FLUE GAS DESULFURIZATION MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SME PLAYERS, BY TYPE, END-USE INDUSTRY, AND REGION
- TABLE 204 FLUE GAS DESULFURIZATION SYSTEM MARKET: DEALS, JANUARY 2022-JULY 2026
- TABLE 205 MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY OVERVIEW
- TABLE 206 MITSUBISHI HEAVY INDUSTRIES, LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 207 GE VERNOVA: COMPANY OVERVIEW
- TABLE 208 GE VERNOVA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 209 DOOSAN LENTJES: COMPANY OVERVIEW
- TABLE 210 DOOSAN LENTJES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 211 BABCOCK & WILCOX ENTERPRISES, INC.: COMPANY OVERVIEW
- TABLE 212 BABCOCK & WILCOX ENTERPRISES, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 213 BABCOCK & WILCOX ENTERPRISES, INC.: DEALS
- TABLE 214 ANDRITZ: COMPANY OVERVIEW
- TABLE 215 ANDRITZ: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 216 ANDRITZ: DEALS
- TABLE 217 VALMET: COMPANY OVERVIEW
- TABLE 218 VALMET: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 219 KAWASAKI HEAVY INDUSTRIES, LTD.: COMPANY OVERVIEW
- TABLE 220 KAWASAKI HEAVY INDUSTRIES, LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 221 BHARAT HEAVY ELECTRICALS LIMITED: COMPANY OVERVIEW
- TABLE 222 BHARAT HEAVY ELECTRICALS LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 223 LONGKING ENVIRONMENTAL PROTECTION: COMPANY OVERVIEW
- TABLE 224 LONGKING ENVIRONMENTAL PROTECTION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 225 KC COTTRELL: COMPANY OVERVIEW
- TABLE 226 KC COTTRELL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 227 THERMAX LIMITED: COMPANY OVERVIEW
- TABLE 228 MET: COMPANY OVERVIEW
- TABLE 229 DUCON: COMPANY OVERVIEW
- TABLE 230 CHIYODA CORPORATION: COMPANY OVERVIEW
- TABLE 231 CHINA BOQI ENVIRONMENTAL (HOLDING) CO., LTD: COMPANY OVERVIEW
- TABLE 232 MACROTEK INC.: COMPANY OVERVIEW
- TABLE 233 RUDRIS: COMPANY OVERVIEW
- TABLE 234 STEINMULLER ENGINEERING GMBH: COMPANY OVERVIEW
- TABLE 235 BAOLAN EP INC.: COMPANY OVERVIEW
- TABLE 236 TSUKISHIMA KIKAI CO., LTD.: COMPANY OVERVIEW
- TABLE 237 WUHAN KAIDI ELECTRIC POWER ENVIRONMENTAL CO., LTD.: COMPANY OVERVIEW
- TABLE 238 RIECO INDUSTRIES LIMITED: COMPANY OVERVIEW
- TABLE 239 ACMEFIL ENGINEERING SYSTEMS PVT LTD.: COMPANY OVERVIEW
- TABLE 240 TNBI INDUSTRIES PVT. LTD.: COMPANY OVERVIEW
- TABLE 241 ERGIL: COMPANY OVERVIEW
- TABLE 243 RESEARCH LIMITATIONS AND RISK ASSESSMENT
List of Figures
- FIGURE 1 MARKETS COVERED AND REGIONAL SCOPE
- FIGURE 2 DURATION COVERED
- FIGURE 3 MARKET HIGHLIGHTS AND KEY INSIGHTS
- FIGURE 4 FGD SYSTEMS MARKET, 2023-2031
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN FGD SYSTEMS MARKET (2022-2026)
- FIGURE 6 DISRUPTIVE TRENDS IMPACTING GROWTH OF FGD SYSTEMS MARKET DURING FORECAST PERIOD
- FIGURE 7 HIGH-GROWTH SEGMENTS IN FGD SYSTEMS MARKET, 2026-2031
- FIGURE 8 ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 9 ASIA PACIFIC TO OFFER LUCRATIVE OPPORTUNITIES FOR FGD SYSTEMS MARKET PLAYERS
- FIGURE 10 WET FGD SYSTEMS TO CAPTURE PROMINENT MARKET SHARE, IN TERMS OF VOLUME, IN 2031
- FIGURE 11 BROWNFIELD INSTALLATIONS TO HOLD MAJORITY OF MARKET SHARE, IN TERMS OF VOLUME, IN 2031
- FIGURE 12 POWER GENERATION INDUSTRY TO LEAD MARKET, IN TERMS OF VOLUME, THROUGHOUT FORECAST PERIOD
- FIGURE 13 INDIA TO BE MOST LUCRATIVE MARKET GLOBALLY DURING FORECAST PERIOD
- FIGURE 14 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN FGD SYSTEMS MARKET
- FIGURE 15 FGD SYSTEMS MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 16 FLUE GAS DESULFURIZATION SYSTEM VALUE CHAIN ANALYSIS
- FIGURE 17 FLUE GAS DESULFURIZATION SYSTEM ECOSYSTEM ANALYSIS
- FIGURE 18 AVERAGE SELLING PRICE TREND OF FGD SYSTEMS, BY REGION, 2023-2025
- FIGURE 19 AVERAGE SELLING PRICE TREND OF FGD SYSTEMS, BY TYPE, 2023-2025 (USD MILLION/UNIT)
- FIGURE 20 IMPORT SCENARIO FOR HS CODE 842139-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025
- FIGURE 21 EXPORT SCENARIO FOR HS CODE 842139-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025
- FIGURE 22 TRENDS/DISRUPTIONS INFLUENCING FGD SYSTEMS MARKET GROWTH
- FIGURE 23 INVESTMENT AND FUNDING SCENARIO, 2020-2025
- FIGURE 24 LIST OF MAJOR PATENTS FOR FLU GAS DESULFURIZATION SYSTEMS, 2016-2025
- FIGURE 25 PATENT ANALYSIS, BY LEGAL STATUS
- FIGURE 26 TOP JURISDICTION, BY DOCUMENT
- FIGURE 27 FGD SYSTEMS MARKET: DECISION-MAKING FACTORS
- FIGURE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY END-USE INDUSTRIES
- FIGURE 29 KEY BUYING CRITERIA FOR TOP 3 END-USE INDUSTRIES
- FIGURE 30 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 31 WET FGD SYSTEMS TO LEAD MARKET THROUGHOUT FORECAST PERIOD
- FIGURE 32 FGD SYSTEMS MARKET, BY INSTALLATION, 2026 VS. 2031
- FIGURE 33 POWER GENERATION INDUSTRY TO DOMINATE MARKET FROM 2026 TO 2031
- FIGURE 34 INDIA TO BE FASTEST-GROWING GLOBAL MARKET FOR FGD SYSTEMS DURING FORECAST PERIOD
- FIGURE 35 NORTH AMERICA: FGD SYSTEM MARKET SNAPSHOT
- FIGURE 36 EUROPE: FGD SYSTEMS MARKET SNAPSHOT
- FIGURE 37 ASIA PACIFIC: FGD SYSTEMS MARKET SNAPSHOT
- FIGURE 38 REVENUE ANALYSIS OF KEY PLAYERS IN FGD SYSTEMS MARKET, 2021-2025
- FIGURE 39 FGD SYSTEMS MARKET SHARE ANALYSIS, 2025
- FIGURE 40 FGD SYSTEMS MARKET: PRODUCT COMPARATIVE ANALYSIS
- FIGURE 41 FGD SYSTEMS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 42 FGD SYSTEMS MARKET: COMPANY FOOTPRINT
- FIGURE 43 FLUE GAS DESULFURIZATION SYSTEM MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 44 EV/EBITDA OF KEY MANUFACTURERS IN FGD SYSTEMS MARKET
- FIGURE 45 COMPANY VALUATION OF KEY PLAYERS IN FLUE GAS DESULFURIZATION SYSTEM MARKET (2025)
- FIGURE 46 MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY SNAPSHOT
- FIGURE 47 GE VERNOVA: COMPANY SNAPSHOT
- FIGURE 48 BABCOCK & WILCOX ENTERPRISES, INC.: COMPANY SNAPSHOT
- FIGURE 49 ANDRITZ: COMPANY SNAPSHOT
- FIGURE 50 VALMET: COMPANY SNAPSHOT
- FIGURE 51 KAWASAKI HEAVY INDUSTRIES, LTD.: COMPANY SNAPSHOT
- FIGURE 52 BHARAT HEAVY ELECTRICALS LIMITED: COMPANY SNAPSHOT
- FIGURE 53 LONGKING ENVIRONMENTAL PROTECTION: COMPANY SNAPSHOT
- FIGURE 54 KC COTTRELL: COMPANY SNAPSHOT
- FIGURE 55 FGD SYSTEMS MARKET: RESEARCH DESIGN
- FIGURE 56 BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY, DESIGNATION, AND REGION
- FIGURE 57 MARKET SIZE ESTIMATION: BOTTOM-UP APPROACH
- FIGURE 58 MARKET SIZE ESTIMATION: TOP-DOWN APPROACH
- FIGURE 59 FGD SYSTEMS MARKET: DATA TRIANGULATION
- FIGURE 60 ASSUMPTIONS CONSIDERED

 排煙脫硫(FGD):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 廢氣脫硫系統市場-2026-2032年全球市場預測
 排煙脫硫設備市場機會、成長要素、產業趨勢分析及2026-2035年預測
 洗滌器(FGDs)工業廢氣脫硫塔市場:依技術、材料、安裝、塔型和最終用戶分類,全球預測(2026-2032)
 全球廢氣脫硫市場規模、佔有率、趨勢及成長分析報告(2026-2034年)
 2026年全球濕式煙氣脫硫系統市場報告2026年全球煙道氣體脫硫系統市場報告
 煙氣脫硫市場 - 全球產業規模、佔有率、趨勢、機會及預測(按類型、終端用戶產業、安裝量、地區和競爭格局分類,2021-2031年)
 排煙脫硫(FGD)市場按材料類型、最終用途行業和地區分類