

 |
市場調查報告書
商品編碼
2121190
類比前端積體電路市場機會、成長要素、產業趨勢分析及2026-2035年預測Analog Front-End (AFE) IC Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球類比前端積體電路市場預計到 2025 年將達到 31 億美元,年複合成長率為 9.2%,到 2035 年將達到 74 億美元。
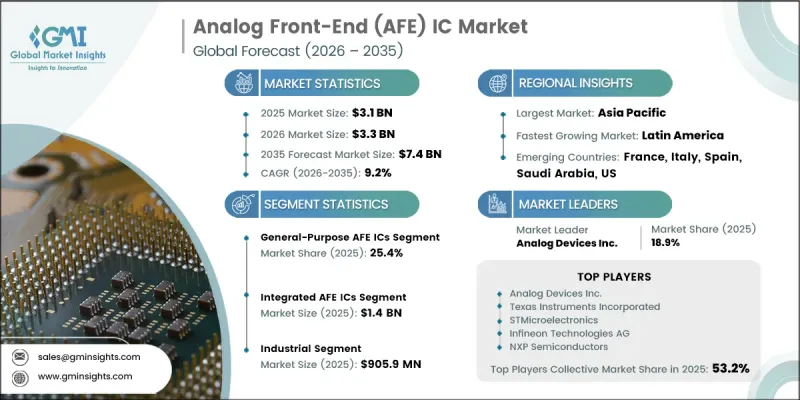
互聯和自動化技術對半導體的需求不斷成長,為模擬前端積體電路 (AFE) 製造商創造了新的成長機會。智慧工業系統、電動車、先進醫療電子設備、邊緣運算設備以及新興無線技術的日益普及,正在推動市場擴張。類比前端積體電路在電子系統中扮演著至關重要的角色,它接收原始類比訊號並將其轉換為數位訊號,以便進行後續處理。這些晶片執行訊號調理、放大、濾波和類比數位轉換等功能,幫助電子系統精確處理來自感測器的資訊。隨著製造商開發出更小巧、更智慧、更節能的設備,市場對能夠提供可靠訊號擷取並支援緊湊型系統設計的 AFE 解決方案的需求日益成長。預計對自動化、電氣化、連網型設備和先進電子技術的持續投資將進一步擴大模擬前端積體電路在多個應用領域的應用。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 31億美元 |
| 預計金額 | 74億美元 |
| 複合年成長率 | 9.2% |
由於工業自動化、互聯工業環境和數位化製造系統的擴展,類比前端 (AFE) IC 市場正蓬勃發展,這些系統對精確感測和即時訊號擷取的需求日益成長。攜帶式和穿戴式電子設備的日益普及也為 AFE 技術創造了更多機遇,尤其是在醫療保健應用領域,該領域對連續、精確的電子資料收集的需求不斷成長。數位醫療實踐的廣泛應用以及監管機構和公共衛生機構的支持,預計將推動對用於生物訊號採集的低功耗、高精度解決方案的需求。同時,電動車和儲能技術的日益普及也推動了對精確監控和控制電子設備的需求。電池管理系統需要精確測量和處理電參數,是高精度 AFE IC 的關鍵應用領域。因此,電動交通和儲能基礎設施的持續發展預計將為 AFE IC 市場提供穩定的成長機會。
到2025年,通用AFE IC的市佔率將達到25.4%。其廣泛的功能和通用性正推動其在各種電子應用中廣泛應用。製造商和系統開發人員在需要滿足多種類比訊號處理需求,而又不想依賴高度專業化的架構時,會選擇使用這些元件。通用AFE IC能夠以經濟高效的方式提供訊號調理、訊號放大和類比數位轉換等功能。它們滿足多樣化系統需求的能力正推動其在包括工業設備、電子產品、汽車系統、健康監測設備和通訊基礎設施在內的眾多領域得到應用。憑藉其功能柔軟性和相對經濟的實現成本,通用AFE IC仍然是那些需要可靠類比訊號處理且系統複雜度不高的應用的理想選擇。
預計到2025年,整合AFE IC市場規模將達到14億美元,這主要得益於將多種類比功能整合到單一半導體裝置的優勢。根據系統結構的不同,整合AFE解決方案可以整合訊號調理、放大、濾波、類比數位轉換、電源管理和其他輔助功能。整合這些功能不僅可以減少所需的電路基板空間,還可以降低系統總成本、能耗和設計複雜性。這些優勢促使設計人員採用整合AFE架構來建構緊湊型先進電子系統。市場需求仍然強勁,尤其是在工業自動化、汽車電子、醫療設備和電信設備等領域,製造商越來越傾向於尋求能夠在保持高效系統佈局和低功耗的同時提供多種功能的解決方案。
預計到2025年,北美類比前端(AFE)積體電路市佔率將達到31.8%。該地區市場受益於完善的半導體生態系統以及公共和私人部門對先進技術的持續投資。政府對工業自動化、電動車和人工智慧(AI)驅動技術的支持,促進了電子製造業的擴張,並增加了對相關組件的需求。半導體製造商也正在開發日益精密的智慧感測解決方案,以支援互聯和自動化設備的部署。工業4.0技術在包括製造業在內的各個領域的日益普及,進一步推動了對高精度感測和訊號處理組件的需求。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 工業自動化和智慧感測器應用的擴展
- 電動車(EV)產量和電池管理系統(BMS)的成長
- 穿戴式醫療設備和醫療保健電子產品的普及。
- 擴大人工智慧邊緣運算和物聯網設備的應用。
- 持續投資於最先進的半導體製造和通訊基礎設施。
- 產業潛在風險與挑戰
- 高精度AFE IC的設計複雜性和高昂的開發成本。
- 供應鏈限制和對半導體製造的依賴
- 市場機遇
- 人工智慧邊緣設備和智慧感測應用的廣泛應用。
- 電動車、可再生能源和先進電池管理系統的擴展
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 通用AFE積體電路
- 用於醫療和生物訊號應用的AFE IC
- 用於工業測量和數據採集的AFE IC
- 電池管理 AFE IC
- 通訊/射頻AFE積體電路
- 用於成像和光學的AFE積體電路
- 用於感測器介面的 AFE IC
第6章 市場估價與預測:依建築類型分類,2022-2035年
- 獨立式AFE積體電路
- 整合AFE IC
- AFE系統晶片(SoC)
第7章 市場估計與預測:依最終用途分類,2022-2035年
- 產業
- 流程自動化與控制系統
- 機器人與運動系統
- 能源和電力監測系統
- 工業數據採集和測量設備
- 其他
- 汽車和運輸業
- ADAS
- 電動車電池管理系統
- 車載資訊娛樂和遠端資訊處理
- 馬達控制和動力傳動系統
- 其他
- 醫療保健
- 病患監測設備
- 醫學影像系統
- 植入式和穿戴式醫療設備
- 檢測和臨床設備
- 其他
- 電訊和通訊
- 無線基礎設施
- 光纖通訊模組
- 有線通訊設備
- 網路測試與測量
- 其他
- 家用電子電器和穿戴式裝置
- 音訊和語音處理
- 成像和相機模組
- 用於健康和健身的穿戴式設備
- 智慧家庭和物聯網設備
- 其他
- 航太/國防
- 雷達和電子戰系統
- 航空電子設備和飛行控制系統
- 安全通訊系統
- 導航和定位系統
- 其他
- 其他
第8章 市場估算與預測:依通路組成分類,2022-2035年
- 單通道AFE積體電路
- 雙通道AFE積體電路
- 4通道AFE積體電路
- 8通道AFE積體電路
- 具有 16 個或更多通道的 AFE IC
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Analog Devices Inc.
- Texas Instruments Incorporated
- STMicroelectronics
- Infineon Technologies AG
- NXP Semiconductors
- 該地區的主要公司
- 北美洲
- Cirrus Logic, Inc.
- Microchip Technology Inc.
- Onsemi
- 亞太地區
- Hycon Technology Corp
- Nisshinbo Micro Devices Inc.
- Renesas Electronics Corp.
- ROHM Co., Ltd.
- SINOWEALTH Electronic Ltd.
- 歐洲
- ams-OSRAM AG
- 北美洲
- 小眾玩家/顛覆者
- Asahi Kasei Microdevices Corp.
The Global Analog Front-End IC Market was valued at USD 3.1 billion in 2025 and is estimated to grow at a CAGR of 9.2% to reach USD 7.4 billion by 2035.
Rising semiconductor demand across connected and automated technologies is creating new growth opportunities for analog front-end IC manufacturers. Increasing adoption of intelligent industrial systems, electric mobility, advanced healthcare electronics, edge computing devices, and emerging wireless technologies is supporting market expansion. Analog front-end ICs play an important role in electronic systems by receiving raw analog signals and preparing them for further digital processing. These chips can perform functions such as signal conditioning, amplification, filtering, and analog-to-digital conversion, helping electronic systems process sensor-generated information accurately. As manufacturers develop smaller, smarter, and more energy-efficient devices, demand is increasing for AFE solutions that can provide reliable signal acquisition while supporting compact system designs. Continued investments in automation, electrification, connected devices, and advanced electronics are expected to strengthen the adoption of analog front-end ICs across multiple applications.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.1 Billion |
| Forecast Value | $7.4 Billion |
| CAGR | 9.2% |
The analog front-end IC market is gaining momentum from the expansion of industrial automation, connected industrial environments, and digital manufacturing systems that require accurate sensing and real-time signal acquisition. The growing use of portable and wearable electronic equipment is also creating additional opportunities for AFE technology, particularly as healthcare applications increasingly depend on continuous and accurate electronic data collection. Wider acceptance of digital healthcare practices and supportive initiatives from healthcare regulators and public health organizations are expected to encourage demand for low-power and high-precision solutions used for biological signal acquisition. At the same time, increasing deployment of electric vehicles and energy storage technologies is expanding the requirement for accurate monitoring and control electronics. Battery management systems represent an important application area for high-accuracy AFE ICs because they require precise measurement and processing of electrical parameters. The continued development of electrified transportation and energy storage infrastructure is therefore expected to provide steady growth opportunities for the AFE IC market.
The general-purpose AFE ICs held a 25.4% share in 2025. Their broad functionality and versatility have supported adoption across a diverse range of electronic applications. Manufacturers and system developers use these components where multiple analog signal processing requirements must be addressed without relying on highly specialized architectures. General-purpose AFE ICs provide functions such as signal conditioning, signal amplification, and analog-to-digital conversion within cost-effective solutions. Their ability to support different system requirements has encouraged their use across industrial equipment, electronic products, vehicle systems, health-related monitoring equipment, and communications infrastructure. The combination of functional flexibility and relatively economical implementation continues to make general-purpose AFE ICs an attractive option for applications that require reliable analog signal processing without excessive system complexity.
The integrated AFE ICs segment generated USD 1.4 billion in 2025 supported by the ability to combine several analog functions within a single semiconductor device. Depending on the system architecture, integrated AFE solutions can incorporate signal conditioning, amplification, filtering, analog-to-digital conversion, power management, and other supporting functions. Combining these capabilities helps reduce the amount of circuit board space required while also lowering overall system costs, energy consumption, and design complexity. These benefits are encouraging designers to select integrated AFE architectures for compact and sophisticated electronic systems. Demand remains particularly strong across industrial automation, vehicle electronics, medical equipment, and telecommunications hardware, where manufacturers increasingly seek solutions that deliver multiple functions while maintaining efficient system layouts and power consumption.
North America Analog Front-End IC Market accounted for a 31.8% share in 2025. The regional market is benefiting from the presence of a well-established semiconductor ecosystem and continued public and private investment in advanced technologies. Government support for industrial automation, electric mobility, and artificial intelligence-enabled technologies is contributing to the expansion of electronics manufacturing and related component demand. Semiconductor manufacturers are also developing increasingly intelligent sensing solutions that support the deployment of connected and automated equipment. The growing adoption of Industry 4.0 technologies across manufacturing and other sectors is creating additional demand for precision sensing and signal-processing components.
Prominent companies operating in the global analog front-end IC market include Renesas Electronics Corp., Analog Devices Inc., ROHM Co., Ltd., Infineon Technologies AG, Cirrus Logic, Inc., Texas Instruments, ams-OSRAM AG, STMicroelectronics, NXP Semiconductors, Microchip Technology Inc., Onsemi, Asahi Kasei Microdevices Corp., Nisshinbo Micro Devices Inc., Hycon Technology Corp., and SINOWEALTH Electronic Ltd. Companies in the analog front-end IC market are strengthening their competitive positions through continuous product innovation, portfolio expansion, strategic partnerships, and investments in advanced semiconductor technologies. Manufacturers are developing AFE solutions with improved accuracy, lower power requirements, greater integration, and enhanced signal-processing capabilities to address evolving application requirements. Expanding product portfolios across industrial, automotive, healthcare, communications, and consumer electronics applications allows companies to reach broader customer groups. Businesses are also focusing on advanced manufacturing capabilities and semiconductor research to improve performance and maintain technological differentiation. Strategic collaborations with equipment manufacturers and technology developers help companies expand application opportunities and establish stronger customer relationships.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Product type trends
- 2.2.2 Architecture trends
- 2.2.3 End-use trends
- 2.2.4 Channel configuration trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growing adoption of industrial automation and smart sensors
- 3.2.1.2 Rising electric vehicle (EV) production and battery management systems (BMS)
- 3.2.1.3 Expansion of wearable medical devices and healthcare electronics
- 3.2.1.4 Increasing deployment of AI edge computing and IoT devices
- 3.2.1.5 Continuous investment in advanced semiconductor manufacturing and communication infrastructure
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High design complexity and development costs for precision AFE ICs
- 3.2.2.2 Supply chain constraints and semiconductor manufacturing dependencies
- 3.2.3 Market opportunities
- 3.2.3.1 Growing adoption of AI edge devices and intelligent sensing applications
- 3.2.3.2 Expansion of electric vehicles, renewable energy, and advanced battery management systems
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 General-purpose AFE ICs
- 5.3 Medical & biosignal AFE ICs
- 5.4 Industrial measurement & data acquisition AFE ICs
- 5.5 Battery management AFE ICs
- 5.6 Communication & RF AFE ICs
- 5.7 Imaging & optical AFE ICs
- 5.8 Sensor interface AFE ICs
Chapter 6 Market Estimates and Forecast, By Architecture, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Standalone AFE ICs
- 6.3 Integrated AFE ICs
- 6.4 AFE system-on-chip (SoC)
Chapter 7 Market Estimates and Forecast, By End-use, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Industrial
- 7.2.1 Process automation & control systems
- 7.2.2 Robotics & motion systems
- 7.2.3 Energy & power monitoring systems
- 7.2.4 Industrial data acquisition & instrumentation
- 7.2.5 Others
- 7.3 Automotive & Transportation
- 7.3.1 ADAS
- 7.3.2 Ev battery management systems
- 7.3.3 In-vehicle infotainment & telematics
- 7.3.4 Motor control & powertrain
- 7.3.5 Others
- 7.4 Medical & Healthcare
- 7.4.1 Patient monitoring equipment
- 7.4.2 Diagnostic imaging systems
- 7.4.3 Implantable & wearable medical devices
- 7.4.4 Laboratory & clinical instrumentation
- 7.4.5 Others
- 7.5 Telecom & Communication
- 7.5.1 Wireless infrastructure
- 7.5.2 Optical communication modules
- 7.5.3 Wired communication equipment
- 7.5.4 Network test & measurement
- 7.5.5 Others
- 7.6 Consumer Electronics & Wearables
- 7.6.1 Audio & voice processing
- 7.6.2 Imaging & camera modules
- 7.6.3 Health & fitness wearables
- 7.6.4 Smart home & iot devices
- 7.6.5 Others
- 7.7 Aerospace & Defense
- 7.7.1 Radar & electronic warfare systems
- 7.7.2 Avionics & flight control systems
- 7.7.3 Secure communication systems
- 7.7.4 Navigation & positioning systems
- 7.7.5 Others
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Channel Configuration, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Single-channel AFE ICs
- 8.3 Dual-channel AFE ICs
- 8.4 Quad-channel AFE ICs
- 8.5 Octal-channel AFE ICs
- 8.6 16-channel & above AFE ICs
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Analog Devices Inc.
- 10.1.2 Texas Instruments Incorporated
- 10.1.3 STMicroelectronics
- 10.1.4 Infineon Technologies AG
- 10.1.5 NXP Semiconductors
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Cirrus Logic, Inc.
- 10.2.1.2 Microchip Technology Inc.
- 10.2.1.3 Onsemi
- 10.2.2 Asia Pacific
- 10.2.2.1 Hycon Technology Corp
- 10.2.2.2 Nisshinbo Micro Devices Inc.
- 10.2.2.3 Renesas Electronics Corp.
- 10.2.2.4 ROHM Co., Ltd.
- 10.2.2.5 SINOWEALTH Electronic Ltd.
- 10.2.3 Europe
- 10.2.3.1 ams-OSRAM AG
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Asahi Kasei Microdevices Corp.

 電晶體振盪器市場規模、佔有率和成長分析:按振盪器類型、頻段、應用、最終用戶、安裝類型和地區分類 - 產業預測,2026-2033 年
 專用通訊類比IC:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)
 類比IC市場預測至2034年-全球分析(依產品類型、技術、訊號類型、晶圓尺寸、應用、最終用戶、通路及地區分類)
 2026年全球金屬氧化物半導體(MOS)通用邏輯市場報告類比IC體電路用矽晶圓:市場佔有率分析、產業趨勢與統計數據以及成長預測(2026-2031 年)2026年全球消費積體電路市場報告
 應用特定標準產品(ASSP)市場:按類型、應用和地區分類 2026-2034 年電壓監測IC市場:按類型、應用和地區分類(2026-2034年)
 類比IC市場:按產品類型、應用和地區分類
 奈米功率比較器市場報告:趨勢、預測和競爭分析(至2035年)