


 |
市場調查報告書
商品編碼
2109262
施工機械診斷市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Construction Equipment Diagnostics Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球施工機械診斷市場預計到 2025 年將達到 28 億美元,年複合成長率為 9.4%,到 2035 年將達到 69 億美元。
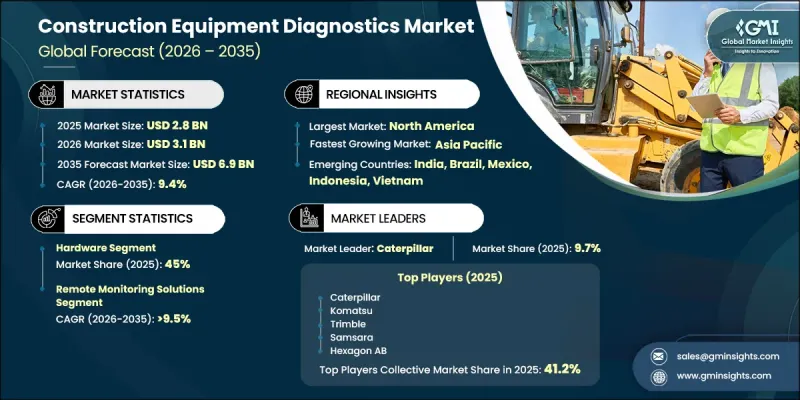
在基礎設施建設投資增加和設備性能標準日益嚴格的推動下,建設公司正在加速在其所有設備中採用先進的診斷和遠端資訊處理解決方案。對合規性、營運效率和設備可靠性的日益重視,促使原始設備製造商 (OEM) 將診斷硬體、基於雲端的車隊管理平台和智慧監控技術整合到建築公司的產品中。同時,更嚴格的環境法規和對設備效率不斷提高的期望,加速了從被動維護到即時監控支援的預測性維護的轉變。物聯網感測器和雲端連接的日益普及,提高了整個施工現場施工機械的可見性,從而實現了主動維護策略。意外的施工機械故障、專案延誤以及緊急維修成本的增加,也促使擁有者投資於能夠提高資產利用率並最大限度減少營運中斷的診斷技術。隨著建設公司越來越重視預測性維護和數據驅動的車隊管理,預計施工機械診斷市場將在預測期內保持持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 28億美元 |
| 預測金額 | 69億美元 |
| 複合年成長率 | 9.4% |
預計到2025年,硬體部分將佔據45%的市場佔有率,並在2035年之前保持8.3%的複合年成長率。由於感測器、控制模組、通訊設備和診斷組件在重型施工機械中的整合度不斷提高,該部分將繼續推動市場成長。這些硬體元件為監控機器性能、收集運行數據和支援進階診斷功能提供了必要的基礎,因此對於新機械的生產和現有機械的現代化改造都至關重要。
預計到2025年,遠端監控解決方案市佔率將達到35.1%,並在2026年至2035年間以9.5%的複合年成長率成長。該細分市場在現代設備維護中仍然扮演著至關重要的角色,它能夠持續監控機器狀態、及早發現故障並制定高效的維護計劃。直接連接到設備控制模組的診斷系統可提供可靠的性能數據,同時支援現有和新部署的施工機械設備進行經濟高效的維護作業。
預計到2025年,美國施工機械診斷市場將佔據92.5%的市場佔有率,市場規模將達8億美元。市場成長的驅動力包括對先進施工機械的強勁需求、互聯機械的普及以及對數位化車隊管理技術的持續投資。完善的遠端資訊處理生態系統、先進的維護基礎設施以及數據驅動型設備管理解決方案的日益普及,都有助於美國繼續保持在區域市場的主導地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 為了減少設備停機時間和專案成本超支,對預測性維護的需求日益成長。
- 嚴格的排放氣體法規要求整合診斷功能(第五階段,第四階段最終版)。
- 新興國家建設活動活性化和車輛數量成長
- 原始設備製造商正在從工廠開始推廣整合式遠端資訊處理和售後診斷生態系統。
- 市場限制因素
- 中小承包商擔心初始投資和總擁有成本過高。
- 物聯網連接診斷系統中的網路安全和資料隱私風險
- 市場機遇
- 快速採用人工智慧和邊緣運算技術進行現場即時故障預測。
- 擴展設備即服務 (EaaS) 和基於訂閱的診斷模式
- 發展中市場老舊現有車隊中蘊藏尚未開發的維修機會。
- 將診斷技術與BIM和智慧施工現場管理平台整合
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國:EPA第四階段最終非道路排放氣體標準與OSHA設備安全與檢驗標準
- 加拿大:加拿大運輸部非道路設備排放氣體法規和省級職場設備安全指南。
- 歐洲
- 德國:歐盟第五階段排放氣體標準與德國聯邦排放氣體法規(BImSchG)
- 英國:非道路移動機械 (NRMM) 的法規與健康與安全執法 (HSE) 設備標準
- 法國:歐盟機械法規 2023/1230 和法國環境法典規定的設備排放氣體要求
- 義大利:符合歐盟第五階段標準以及基於「Codice della Strada」的設備和操作法規。
- 亞太地區
- 中國:中國第四階段非道路車輛排放氣體標準與中國強制車輛認證(CCC)
- 印度:Bharat CEV 第四/五階段非道路排放氣體標準和 FAME III/PM E-DRIVE獎勵計劃
- 日本:日本非道路車輛排放氣體法規和JCMA遠端資訊處理資料標準(ISO/TS 15143-4)
- 韓國:韓國非道路車輛排放氣體標準及施工機械電子設備KCs認證
- 澳洲:澳洲非道路柴油排放氣體標準與各州/領地設備安全法規
- 拉丁美洲
- 巴西:CONAMA關於柴油排放法規和INMETRO設備認證的決議
- 墨西哥:工業機械的NOM安全與排放氣體標準
- 阿根廷:國家公路安全局 (ANSV) 發布的重型設備操作指南
- 中東和非洲
- 阿拉伯聯合大公國:阿拉伯聯合大公國市政施工機械標準及衛生與公共工程部職業安全健康框架
- 沙烏地阿拉伯:SASO設備認證標準及「2030願景」合規要求
- 南非:國家強制性標準和法規 (NRCS) 機械安全標準和設備認證(由 SABS 頒發)
- 北美洲
- 波特的分析
- PESTLE分析
- 專利趨勢
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 電氣化和替代推進系統的影響
- 電池電動和混合動力設備的診斷要求
- 電池健康監測作為一個新的診斷細分領域
- OEM廠商針對電動車隊診斷的藍圖
- 永續性和ESG的影響分析
- 診斷在減排和合規報告中的作用
- 透過預測性維護最佳化燃油效率和碳足跡。
- ESG報告要求正在推動診斷工具的普及。
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 硬體
- 感應器
- 車載資訊設備
- 控制單元
- 顯示和介面單元
- 其他
- 軟體
- 服務
- 專業服務
- 託管服務
第6章 市場估計與預測:依診斷分類,2022-2035年
- 車載診斷系統(OBD)
- 遠端監控解決方案
- 預測性診斷
- 即時效能追蹤
第7章 市場估計與預測:依設備類型分類,2022-2035年
- 土木工程施工機械
- 車載診斷系統(OBD)
- 遠端監控解決方案
- 預測性診斷
- 即時運作狀態追蹤
- 物料輸送設備
- 車載診斷系統(OBD)
- 遠端監控解決方案
- 預測性保護
- 即時效能追蹤
- 道路施工設備
- 車載診斷系統(OBD)
- 遠端監控解決方案
- 預測性保護
- 即時運作狀態追蹤
- 混凝土設備
- 車載診斷系統(OBD)
- 遠端監控解決方案
- 預測性保護
- 即時效能追蹤
第8章 市場估算與預測:以連結方式分類,2022-2035年
- 有線
- 無線的
第9章 市場估計與預測:依最終用途分類,2022-2035年
- 建築承包商
- 設備租賃公司
- OEMs
- 車隊管理服務提供者
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 比利時
- 荷蘭
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- ANZ
- 韓國
- 印尼
- 泰國
- 越南
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 世界公司
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment
- Deere & Company
- CNH Industrial
- Hitachi Construction Machinery
- Trimble Inc.
- Hexagon AB
- TEXA SpA
- Jaltest
- 本地公司
- JCB
- HD Hyundai Construction Equipment
- Doosan Bobcat
- SANY Heavy Industry
- XCMG Group
- ACTIA Group
- Proemion
- Samsara
- CalAmp
- ORBCOMM
The Global Construction Equipment Diagnostics Market was valued at USD 2.8 billion in 2025 and is estimated to grow at a CAGR of 9.4% to reach USD 6.9 billion by 2035.
Growing investments in infrastructure development and increasingly stringent equipment performance standards are encouraging construction companies to adopt advanced diagnostic and telematics solutions across their equipment fleets. Greater emphasis on regulatory compliance, operational efficiency, and equipment reliability is driving the integration of OEM-installed diagnostic hardware, cloud-based fleet management platforms, and intelligent monitoring technologies. At the same time, stricter environmental regulations and higher expectations for equipment efficiency are accelerating the transition from reactive maintenance to predictive diagnostics supported by real-time monitoring. Expanding deployment of IoT-enabled sensors and cloud connectivity is improving equipment visibility across construction sites while enabling proactive maintenance strategies. Rising costs associated with unexpected equipment failures, project delays, and emergency repairs are also motivating fleet owners to invest in diagnostic technologies that improve asset utilization and minimize operational disruptions. As construction companies increasingly prioritize preventive maintenance and data-driven fleet management, the construction equipment diagnostics market is expected to experience sustained growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.8 Billion |
| Forecast Value | $6.9 Billion |
| CAGR | 9.4% |
The hardware segment accounted for a 45% share in 2025 and is expected to register a CAGR of 8.3% through 2035. The segment continues to lead the market due to increasing integration of sensors, control modules, communication devices, and diagnostic components into heavy construction equipment. These hardware elements provide the essential infrastructure required for monitoring machine performance, collecting operational data, and supporting advanced diagnostic capabilities, making them indispensable across both new equipment production and fleet modernization initiatives.
The remote monitoring solutions segment held a 35.1% share in 2025 and is projected to grow at a CAGR of 9.5% from 2026 to 2035. The segment remains a key component of modern equipment maintenance by enabling continuous monitoring of machine health, early fault detection, and efficient maintenance planning. Diagnostic systems connected directly to equipment control modules provide reliable performance data while supporting cost-effective maintenance practices across both existing and newly deployed construction fleets.
United States Construction Equipment Diagnostics Market held a 92.5% share, generating USD 800 million in 2025. Market growth is supported by strong demand for advanced construction equipment, widespread adoption of connected machinery, and continued investment in digital fleet management technologies. A well-developed telematics ecosystem, advanced maintenance infrastructure, and increasing implementation of data-driven equipment management solutions continue to reinforce the country's leading position in the regional market.
Key players operating in the global construction equipment diagnostics market include Caterpillar Inc., CNH Industrial, Deere & Company, Hexagon AB, Hitachi Construction Machinery, Jaltest, Komatsu Ltd., TEXA S.p.A., Trimble Inc., and Volvo Construction Equipment. Companies operating in the construction equipment diagnostics market are strengthening their market position by investing in advanced telematics technologies, predictive maintenance platforms, and intelligent diagnostic solutions that improve equipment performance and fleet efficiency. Manufacturers are expanding research and development efforts to integrate artificial intelligence, IoT connectivity, cloud-based analytics, and real-time monitoring capabilities into their diagnostic systems. Strategic collaborations with construction companies, equipment manufacturers, and technology providers are helping businesses broaden their customer reach and accelerate solution adoption. Companies are also enhancing software functionality, expanding aftermarket support services, and developing scalable diagnostic platforms that support both new equipment and existing fleets.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast Model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Diagnostic
- 2.2.4 Equipment
- 2.2.5 Connectivity
- 2.2.6 End Use
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising demand for predictive maintenance to reduce equipment downtime & project cost overruns
- 3.2.1.2 Stringent emission compliance regulations (Stage V, Tier 4 final) mandating diagnostic integration
- 3.2.1.3 Growing construction activity & fleet expansion in emerging economies
- 3.2.1.4 OEM push for factory-integrated telematics & aftermarket diagnostics ecosystems
- 3.2.2 Market Restraints
- 3.2.2.1 High initial investment & total cost of ownership concerns among SME contractors
- 3.2.2.2 Cybersecurity & data privacy risks in IoT-connected diagnostic systems
- 3.2.3 Market Opportunities
- 3.2.3.1 Rapid adoption of AI & edge computing for on-site real-time fault prediction
- 3.2.3.2 Expansion of equipment-as-a-service (EaaS) & subscription-based diagnostic models
- 3.2.3.3 Untapped retrofitting opportunity in aging legacy fleet base across developing markets
- 3.2.3.4 Integration of diagnostics with bim & smart construction site management platforms
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 U.S.: EPA Tier 4 Final Non-Road Emission Standards & OSHA Equipment Safety and Inspection Standards
- 3.6.1.2 Canada: Transport Canada Off-Road Equipment Emission Regulations & Provincial Workplace Equipment Safety Guidelines
- 3.6.2 Europe
- 3.6.2.1 Germany: EU Stage V Emission Standards & German Federal Emission Control Act (BImSchG)
- 3.6.2.2 UK: Non-Road Mobile Machinery (NRMM) Regulations & Health and Safety Executive (HSE) Equipment Standards
- 3.6.2.3 France: EU Machinery Regulation 2023/1230 & French Environmental Code Equipment Emission Requirements
- 3.6.2.4 Italy: EU Stage V Compliance & Codice della Strada Equipment Operational Regulations
- 3.6.3 Asia Pacific
- 3.6.3.1 China: China Stage IV Non-Road Emission Standards & China Compulsory Certification (CCC)
- 3.6.3.2 India: Bharat CEV Stage IV/V Non-Road Emission Standards & FAME III/PM E-DRIVE Incentive Scheme
- 3.6.3.3 Japan: Japan Off-Road Emission Regulations & JCMA Telematics Data Standard (ISO/TS 15143-4)
- 3.6.3.4 South Korea: Korea Off-Road Emission Standards & KCs Certification for Construction Machinery Electronics
- 3.6.3.5 Australia: Australian Non-Road Diesel Emission Standards & State/Territory Equipment Safety Regulations
- 3.6.4 Latin America
- 3.6.4.1 Brazil: CONAMA Diesel Emission Resolutions & INMETRO Equipment Certification
- 3.6.4.2 Mexico: NOM Safety and Emission Standards for Industrial Machinery
- 3.6.4.3 Argentina: National Road Safety Agency (ANSV) Heavy Equipment Operating Guidelines
- 3.6.5 MEA
- 3.6.5.1 UAE: UAE Municipal Construction Equipment Standards & MOHAP Occupational Safety Frameworks
- 3.6.5.2 Saudi Arabia: SASO Equipment Certification Standards & Vision 2030 Compliance Requirements
- 3.6.5.3 South Africa: National Regulator for Compulsory Specifications (NRCS) Machinery Safety Standards & SABS Equipment Certification
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Patent Landscape (Driven by Primary Research)
- 3.10 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.10.1 AI-driven disruption of existing business models
- 3.10.2 GenAI use cases & adoption roadmap by segment
- 3.10.3 Risks, limitations & regulatory considerations
- 3.11 Electrification & alternative propulsion impact
- 3.11.1 Diagnostics requirements for battery-electric & hybrid equipment
- 3.11.2 Battery health monitoring as an emerging diagnostics sub-segment
- 3.11.3 OEM roadmap for electrified fleet diagnostics
- 3.12 Sustainability & ESG impact analysis
- 3.12.1 Role of diagnostics in emissions reduction & compliance reporting
- 3.12.2 Fuel efficiency & carbon footprint optimization through predictive maintenance
- 3.12.3 ESG reporting requirements driving diagnostics adoption
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - Key Macro & Industry Variables Driving CAGR
- 3.13.2 Optimistic Scenarios - Favourable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company Tier Benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Bn, Units)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Sensors
- 5.2.2 Telematics devices
- 5.2.3 Control units
- 5.2.4 Display & interface units
- 5.2.5 Others
- 5.3 Software
- 5.4 Services
- 5.4.1 Professional services
- 5.4.2 Managed services
Chapter 6 Market Estimates & Forecast, By Diagnostic, 2022 - 2035 ($Bn)
- 6.1 Key trends
- 6.2 Onboard diagnostics (OBD)
- 6.3 Remote monitoring solutions
- 6.4 Predictive diagnostics
- 6.5 Real-time performance tracking
Chapter 7 Market Estimates & Forecast, By Equipment, 2022 - 2035 ($Bn)
- 7.1 Key trends
- 7.2 Earthmoving equipment
- 7.2.1 Onboard diagnostics (OBD)
- 7.2.2 Remote monitoring solutions
- 7.2.3 Predictive diagnostics
- 7.2.4 Real-time performance tracking
- 7.3 Material handling equipment
- 7.3.1 Onboard diagnostics (OBD)
- 7.3.2 Remote monitoring solutions
- 7.3.3 Predictive diagnostics
- 7.3.4 Real-time performance tracking
- 7.4 Road construction equipment
- 7.4.1 Onboard diagnostics (OBD)
- 7.4.2 Remote monitoring solutions
- 7.4.3 Predictive diagnostics
- 7.4.4 Real-time performance tracking
- 7.5 Concrete equipment
- 7.5.1 Onboard diagnostics (OBD)
- 7.5.2 Remote monitoring solutions
- 7.5.3 Predictive diagnostics
- 7.5.4 Real-time performance tracking
Chapter 8 Market Estimates & Forecast, By Connectivity, 2022 – 2035 ($Bn)
- 8.1 Key trends
- 8.2 Wired
- 8.3 Wireless
Chapter 9 Market Estimates & Forecast, By End Use, 2022 – 2035 ($Bn)
- 9.1 Key trends
- 9.2 Construction contractors
- 9.3 Equipment rental companies
- 9.4 OEMs
- 9.5 Fleet management providers
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Bn, Units)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Belgium
- 10.3.8 Netherlands
- 10.3.9 Sweden
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 ANZ
- 10.4.5 South Korea
- 10.4.6 Indonesia
- 10.4.7 Thailand
- 10.4.8 Vietnam
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Caterpillar Inc.
- 11.1.2 Komatsu Ltd.
- 11.1.3 Volvo Construction Equipment
- 11.1.4 Deere & Company
- 11.1.5 CNH Industrial
- 11.1.6 Hitachi Construction Machinery
- 11.1.7 Trimble Inc.
- 11.1.8 Hexagon AB
- 11.1.9 TEXA S.p.A.
- 11.1.10 Jaltest
- 11.2 Regional Players
- 11.2.1 JCB
- 11.2.2 HD Hyundai Construction Equipment
- 11.2.3 Doosan Bobcat
- 11.2.4 SANY Heavy Industry
- 11.2.5 XCMG Group
- 11.2.6 ACTIA Group
- 11.2.7 Proemion
- 11.2.8 Samsara
- 11.2.9 CalAmp
- 11.2.10 ORBCOMM


