


 |
市場調查報告書
商品編碼
2109199
拉力運動騎乘裝備市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Rally Sport Riding Gear Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球拉力賽和運動騎乘裝備市場預計到 2025 年將達到 16 億美元,並以 7.8% 的複合年成長率成長,到 2035 年將達到 33 億美元。
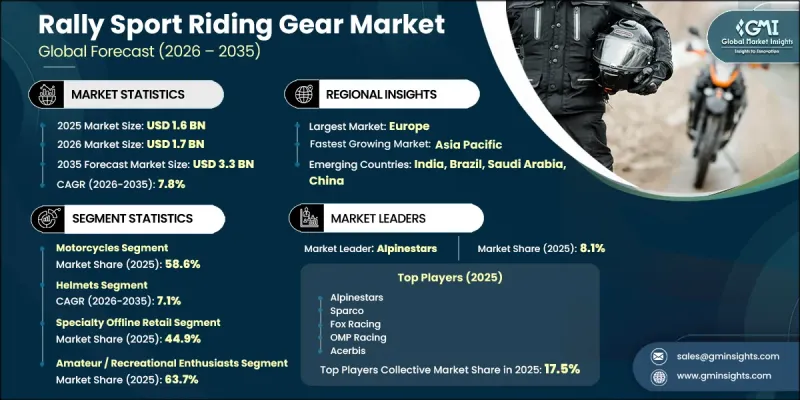
由於全球範圍內有組織的拉力賽和休閒越野騎行活動的持續擴張,拉力運動騎行裝備行業正經歷著穩步成長。日益嚴格的安全法規要求騎士穿戴經認證的防護裝備,從而持續推高了對高品質騎乘裝備的需求。所有參賽者都必須穿著一系列防護裝備,包括頭盔、騎行服、手套、靴子和衝擊防護裝備,這導致產品在其整個生命週期內都需要不斷更換。此外,業餘拉力賽和探險騎行項目的日益普及,也使客戶群從專業選手擴展到了專業選手之外。同時,防護裝備技術的進步提高了騎士的安全性、舒適性、耐用性和整體性能,促使消費者更頻繁地升級裝備。人們對預防傷害意識的提高、更嚴格的安全標準以及對高性能防護產品的投入增加,進一步推動了市場擴張。這些因素,加上人們對賽車運動和戶外騎乘體驗日益成長的興趣,共同促成了全球拉力運動騎乘裝備市場強勁的長期前景。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 16億美元 |
| 預計金額 | 33億美元 |
| 複合年成長率 | 7.8% |
拉力賽車裝備產業持續受益於統籌機構制定的日益嚴格的安全法規,這些法規定義了賽車運動比賽的標準。最新的裝備要求涵蓋頭盔、防護衣、約束系統和騎士保護裝置,進一步推動了整體競技和休閒拉力賽活動中認證安全裝備的普及。除了騎士安全意識的提高,先進的吸震材料、電子安全技術和高性能防護裝備的不斷改進,也使得消費者的購買標準從單純的法規遵從轉向了對防護性能、舒適性和騎行性能的更高追求。隨著防護服技術的不斷創新,製造商們正在推出旨在滿足不斷變化的認證要求,同時兼顧更高靈活性、更輕重量和更強吸震性能的產品。
預計到2025年,摩托車細分市場將佔據58.6%的市場佔有率,並在2026年至2035年間保持9%的複合年成長率。由於摩托車比賽對防護裝備有著全面的要求,摩托車細分市場仍然是拉力賽騎行裝備市場中最大的車輛類別。騎士通常需要一整套經過認證的防護產品,包括頭盔、騎行服、夾克、褲子、手套、靴子、護甲、護膝和高級安全氣囊系統。所需的裝備種類繁多,導致每位參賽者的平均支出很高,這也是全球市場銷售的主要驅動力。
2025年,專業線下零售通路佔據44.9%的市場佔有率,持續維持其作為拉力運動騎乘裝備主要分銷管道的地位。專業零售商透過提供專業的產品諮詢、個人化的試穿服務、認證驗證以及購買競技級防護裝備的管道,持續吸引消費者。由於許多騎乘產品在購買前需要精確的尺寸選擇、相容性評估和安全認證驗證,消費者在購買高階防護裝備時仍然更傾向於線下購物體驗。這些優勢使得專業零售商能夠維持強大的顧客信任度,同時也能讓高階產品的價格與線上銷售管道相比更具競爭力。
中國拉力賽車裝備市場佔25%的市場佔有率,預計到2025年市場規模將達到7,430萬美元。在拉力賽日益普及、賽車愛好者可支配收入不斷成長以及國內賽車運動生態系統持續發展的推動下,中國正進一步鞏固其作為亞太地區成長最快市場之一的地位。競技騎行活動的持續擴展、賽事基礎設施的完善以及拉力賽參與人數的增加,都為亞太地區拉力賽車裝備行業的製造商和經銷商創造了機會。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 擴大全球參與拉力賽和越野賽車運動的規模。
- 加強FIM/FIA強制安全設備規定
- 消費者對騎乘安全和預防傷害的意識日益增強。
- 防護材料的技術進步
- 產業潛在風險與挑戰
- 小眾市場的規模限制了大規模生產所帶來的經濟效益。
- 該產品價格高昂,阻礙了其在業餘愛好者中的廣泛普及。
- 市場機遇
- 新興市場(亞太、中東和非洲)拉力賽旅遊的擴張和業餘愛好者參與度的提高
- 將智慧技術(物聯網感測器、內建安全氣囊系統)整合到裝備中
- 女性勞動參與率的提高正在推動包容性產品線的擴張。
- SSV(並排式車輛)拉力賽的興起對裝備提出了新的要求。
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 多重衝擊能量吸收材料(MIPS、Koroyd、D3O 等)
- 輕質複合材料外殼和符合 FIA 標準的阻燃布料。
- 新興技術
- 內建衝擊感測器和生物識別感測器的智慧防護工具。
- 人工智慧驅動的碰撞偵測和緊急應變系統
- 最新科技趨勢
- 價格分析
- 對過去價格趨勢的分析
- 定價策略:按業務類型分類
- 監理情勢
- 北美洲
- 美國運輸部(US DOT)FMVSS第218號摩托車頭盔標準
- Snell頭盔安全標準適用於賽車運動和摩托車頭盔
- 國際汽聯拉力賽配備安全標準
- SCORE/越野賽事安全配備要求
- 歐洲
- 聯合國歐洲經濟委員會第22/ECE 22.06號條例
- 關於個人防護設備(PPE)的法規(歐盟)2016/425
- FIA 8859-2024 標準適用於高級頭盔,FIA 8856-2018 標準適用於防護衣。
- FIM安全帽認證課程 - FRHPhe-02
- 亞太地區
- 中國 GB 811-2022
- 印度 BIS IS 4151:2015
- 日本JIS T 8133
- 新加坡標準SS 9:2014和聯合國歐洲經濟委員會R22.06框架
- 拉丁美洲
- 巴西國家計量局(INMETRO)第231/2021號條例
- 國際汽聯和國際摩聯對拉力賽和拉力越野賽的認證要求
- 全國賽車運動聯合會安全設備相關規定
- 馬術防護裝備的進口認證和產品標籤要求
- 中東和非洲
- 阿拉伯聯合大公國受監管目標產品合格評定體系 (ECAS)
- 海灣合作理事會標準化組織(GSO)摩托車及相關安全產品合格評定框架
- 沙烏地阿拉伯機車及安全相關產品SASO技術法規
- 南非自然資源保護局製定的摩托車防護頭盔和麵罩強制性標準
- FIA/FIM 區域拉力賽安全設備標準
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 成本細分分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 生產能力和生產情況
- 按地區和主要製造商分類的產能
- 運轉率和擴張計劃
- 來自世界各地的集會參與統計數據
- 集會事故和傷亡統計數據
- 頭部受傷
- 胸部受傷
- 死亡人數趨勢
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 前十強企業的生產與銷售分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依產品分類,2022-2035年
- 頭盔
- 騎行服
- 夾克
- 褲子
- 手套
- 鞋類
- 防彈衣及個人防護裝備
- 不含保護功能的配件
第6章 市場估價與預測:依拉力賽車類型分類,2022-2035年
- 摩托車
- 搭乘用車
- 卡車和並排式車輛(SSV)
第7章 市場估價與預測:依通路分類,2022-2035年
- 專業實體零售店
- 線上電子商務
- OEM/團隊直接供貨
- 租賃和活動相關
第8章 市場估算與預測:依最終用戶分類,2022-2035年
- 專業/競技團隊
- 業餘/休閒愛好者
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 挪威
- 荷蘭
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 新加坡
- 泰國
- 印尼
- 越南
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
- 土耳其
第10章:公司簡介
- 世界公司
- Alpinestars
- OMP Racing
- Sparco
- Leatt
- Fox Racing
- KLIM Technical Riding Gear
- Acerbis
- Dainese
- Arai Helmet
- Shoei
- HJC Helmets
- Rev'It!Sport International
- Schuberth
- Bell Racing Europe
- Stilo
- Sabelt
- 當地公司
- Gaerne
- Sidi Sport
- Helite
- In& Motion
The Global Rally Sport Riding Gear Market was valued at USD 1.6 billion in 2025 and is estimated to grow at a CAGR of 7.8% to reach USD 3.3 billion by 2035.
The rally sport riding gear industry is experiencing steady growth as participation in organized rally competitions and recreational off-road riding activities continues to expand worldwide. Increasing compliance with mandatory safety regulations requiring riders to wear certified protective equipment is creating sustained demand for premium riding gear. Every participant is required to use a complete range of protective equipment, including helmets, riding apparel, gloves, boots, and impact protection, generating recurring replacement demand throughout the product lifecycle. The growing popularity of amateur rally events and adventure riding programs is also broadening the customer base beyond professional competitors. At the same time, advancements in protective equipment technology are improving rider safety, comfort, durability, and overall performance, encouraging consumers to upgrade their gear more frequently. Rising awareness of injury prevention, stronger enforcement of safety standards, and increasing investment in high-performance protective products are further supporting market expansion. These factors, combined with growing interest in motorsports and outdoor riding experiences, continue to strengthen the long-term outlook for the global rally sport riding gear market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $1.6 Billion |
| Forecast Value | $3.3 Billion |
| CAGR | 7.8% |
The rally sport riding gear industry continues to benefit from increasingly stringent safety regulations established by governing organizations responsible for motorsport competition standards. Updated equipment requirements covering helmets, protective clothing, restraint systems, and rider protection are encouraging broader adoption of certified safety gear across competitive and recreational rally events. Greater awareness of rider safety, combined with ongoing improvements in advanced impact protection materials, electronic safety technologies, and high-performance protective equipment, has shifted purchasing decisions beyond regulatory compliance toward enhanced protection, comfort, and riding performance. As innovation continues across protective apparel, manufacturers are introducing products designed to deliver improved mobility, lightweight construction, and higher levels of impact absorption while meeting evolving certification requirements.
The motorcycles segment accounted for a 58.6% share in 2025 and is expected to register a CAGR of 9% between 2026 and 2035. This segment remains the largest vehicle category within the rally sport riding gear market due to the comprehensive protective equipment requirements associated with motorcycle competition. Riders typically require a complete collection of certified protective products, including helmets, riding suits, jackets, pants, gloves, boots, body protection, knee protection, and advanced airbag systems. The extensive range of required equipment contributes to higher average spending per participant, supporting the segment's leading revenue contribution within the global market.
The specialty offline retail segment held a 44.9% share in 2025, maintaining its position as the leading distribution channel for rally sport riding gear. Specialized retail stores continue to attract consumers by offering expert product guidance, personalized fitting services, certification verification, and access to competition-grade protective equipment. Because many riding products require precise sizing, compatibility assessment, and verification of safety certifications before purchase, customers continue to prefer in-person shopping experiences for premium protective gear. These advantages allow specialty retailers to maintain strong customer confidence while supporting premium product pricing compared with online sales channels.
China Rally Sport Riding Gear Market accounted for a 25% share, generating USD 74.3 million in 2025. The country continues to strengthen its position as one of the fastest-growing markets in the region, supported by increasing interest in organized rally competitions, rising disposable income among motorsport enthusiasts, and ongoing development of the domestic motorsports ecosystem. Continued expansion of competitive riding activities, improved event infrastructure, and growing participation in rally sports are creating favorable opportunities for manufacturers and distributors operating across the Asia Pacific rally sport riding gear industry.
Leading companies operating in the global rally sport riding gear market include Alpinestars, Sparco, Fox Racing, OMP Racing, Acerbis, Leatt, KLIM Technical Riding Gear, Arai Helmet, Shoei, and Dainese. Companies participating in the rally sport riding gear industry are strengthening their market position by investing in product innovation, advanced protective materials, and ergonomic design improvements that enhance rider safety and comfort. Many manufacturers are expanding research and development activities to introduce lighter, more durable, and higher-performance protective equipment that meets evolving certification requirements. Strategic partnerships with distributors, motorsport organizations, and retail networks are helping companies improve brand visibility and expand customer reach. Businesses are also focusing on premium product portfolios, digital marketing initiatives, and global distribution expansion to increase market penetration.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product
- 2.2.3 Rally Vehicle Type
- 2.2.4 Distribution Channel
- 2.2.5 End User
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growing Global Participation in Rally & Off-Road Motorsport Events
- 3.2.1.2 Strengthening FIM/FIA Mandatory Safety Equipment Regulations
- 3.2.1.3 Rising Consumer Awareness Regarding Rider Safety & Injury Prevention
- 3.2.1.4 Technological Advancements in Protective Materials
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Niche Market Size Limiting Mass-Scale Manufacturing Economies
- 3.2.2.2 High Product Cost Constraining Amateur Segment Adoption
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of Rally Tourism & Amateur Participation in Emerging Markets (Asia Pacific, MEA)
- 3.2.3.2 Integration of Smart Technology (IoT Sensors, Embedded Airbag Systems) in Gear
- 3.2.3.3 Rising Women's Participation Driving Inclusive Product Line Expansion
- 3.2.3.4 Growth of SSV (Side-by-Side Vehicle) Rally Discipline Creating New Gear Demand
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.1.1 Multi-Impact Energy Absorption Materials (MIPS, Koroyd, D3O, etc.)
- 3.4.1.2 Lightweight Composite Shells & Fire-Resistant FIA-Compliant Fabrics
- 3.4.2 Emerging technologies
- 3.4.2.1 Smart Protective Gear with Embedded Impact & Biometric Sensors
- 3.4.2.2 AI-Enabled Crash Detection & Emergency Response Systems
- 3.4.1 Current technological trends
- 3.5 Pricing Analysis (Driven by primary research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 U.S. DOT FMVSS No. 218 Motorcycle Helmet Standard
- 3.6.1.2 Snell Helmet Safety Standards for Motorsport and Motorcycle Helmets
- 3.6.1.3 FIA Safety Equipment Standards for Rally Competition Gear
- 3.6.1.4 SCORE / Off-Road Event Safety Equipment Requirements
- 3.6.2 Europe
- 3.6.2.1 UNECE Regulation No. 22 / ECE 22.06
- 3.6.2.2 Regulation (EU) 2016/425 on Personal Protective Equipment (PPE)
- 3.6.2.3 FIA Standard 8859-2024 for Premium Helmets and FIA Standard 8856-2018 for Protective Clothing
- 3.6.2.4 FIM Racing Homologation Programme for Helmets - FRHPhe-02
- 3.6.3 Asia Pacific
- 3.6.3.1 China GB 811-2022
- 3.6.3.2 India BIS IS 4151:2015
- 3.6.3.3 Japan JIS T 8133
- 3.6.3.4 Singapore SS 9:2014 and UNECE R22.06 Framework
- 3.6.4 Latin America
- 3.6.4.1 Brazil INMETRO Ordinance No. 231/2021
- 3.6.4.2 FIA and FIM Homologation Requirements for Rally and Rally-Raid Events
- 3.6.4.3 National Motorsport Federation Safety Equipment Rules
- 3.6.4.4 Import Certification and Product Labelling Requirements for Protective Riding Gear
- 3.6.5 Middle East & Africa
- 3.6.5.1 UAE Emirates Conformity Assessment Scheme (ECAS) for Regulated Products
- 3.6.5.2 GCC Standardization Organization (GSO) Conformity Framework for Motorcycles and Related Safety Products
- 3.6.5.3 Saudi SASO Technical Regulations for Motorcycles and Safety-Related Products
- 3.6.5.4 South Africa NRCS Compulsory Specification for Protective Motorcycle Helmets and Visors
- 3.6.5.5 FIA/FIM Safety Equipment Standards for Regional Rally-Raid Events
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by primary research)
- 3.10 Cost breakdown analysis
- 3.11 Trade Data Analysis (Based on Paid Database)
- 3.11.1 Import/Export Volume & Value Trends
- 3.11.2 Key Trade Corridors & Tariff Impact
- 3.12 Capacity & production landscape (driven by primary research)
- 3.12.1 Production capacity by region & key manufacturer
- 3.12.2 Capacity utilization rates & expansion pipelines
- 3.13 Global Rally Participation Statistics
- 3.14 Rally Accident & Injury Statistics
- 3.14.1 Head injuries
- 3.14.2 Chest injuries
- 3.14.3 Fatality trends
- 3.15 Impact of AI and Generative AI on the Market
- 3.15.1 AI Driven Disruption of Existing Business Models
- 3.15.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.15.3 Risks Limitations and Regulatory Considerations
- 3.16 Sustainability and environmental aspects
- 3.16.1 Sustainable practices
- 3.16.2 Waste reduction strategies
- 3.16.3 Energy efficiency in production
- 3.16.4 Eco-friendly Initiatives
- 3.16.5 Carbon footprint considerations
- 3.17 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.17.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.17.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.17.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company Market share analysis (value and volume), 2022-2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Top 10 Company production & sales analysis, 2022-2035
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Product, 2022 - 2035 (USD Bn, Units)
- 5.1 Key trends
- 5.2 Helmets
- 5.3 Riding Suits
- 5.4 Jackets
- 5.5 Pants
- 5.6 Gloves
- 5.7 Footwear & Boots
- 5.8 Body Armor & Standalone Protection
- 5.9 Non-Protection Accessories
Chapter 6 Market Estimates & Forecast, By Rally Vehicle Type, 2022 - 2035 (USD Bn, Units)
- 6.1 Key trends
- 6.2 Motorcycle
- 6.3 Car
- 6.4 Truck & SSV (Side-by-Side Vehicle)
Chapter 7 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035 (USD Bn, Units)
- 7.1 Key trends
- 7.2 Specialty Offline Retail
- 7.3 Online / E-Commerce
- 7.4 OEM / Team Direct Supply
- 7.5 Rental & Event-Based
Chapter 8 Market Estimates & Forecast, By End User, 2022 - 2035 (USD Bn, Units)
- 8.1 Key trends
- 8.2 Professional / Competitive Teams
- 8.3 Amateur / Recreational Enthusiasts
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 (USD Bn, Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Russia
- 9.3.7 Norway
- 9.3.8 Netherlands
- 9.3.9 Sweden
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Singapore
- 9.4.7 Thailand
- 9.4.8 Indonesia
- 9.4.9 Vietnam
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
- 9.6.4 Turkey
Chapter 10 Company Profiles
- 10.1 Global Players
- 10.1.1 Alpinestars
- 10.1.2 OMP Racing
- 10.1.3 Sparco
- 10.1.4 Leatt
- 10.1.5 Fox Racing
- 10.1.6 KLIM Technical Riding Gear
- 10.1.7 Acerbis
- 10.1.8 Dainese
- 10.1.9 Arai Helmet
- 10.1.10 Shoei
- 10.1.11 HJC Helmets
- 10.1.12 Rev'It! Sport International
- 10.1.13 Schuberth
- 10.1.14 Bell Racing Europe
- 10.1.15 Stilo
- 10.1.16 Sabelt
- 10.2 Regional Players
- 10.2.1 Gaerne
- 10.2.2 Sidi Sport
- 10.2.3 Helite
- 10.2.4 In&Motion

 摩托車防護騎行裝備市場-2026-2032年全球市場預測
 騎乘裝備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 摩托車騎乘裝備市場-全球產業規模、佔有率、趨勢、機會與預測:按產品類型、通路、地區和競爭格局分類,2021-2031年
 固定齒輪自行車市場:按應用、車架材料和地區分類
 摩托車騎行裝備市場規模、佔有率及成長分析(按產品、應用和地區分類)-2026-2033年產業預測
 全球拉力賽騎乘裝備市場
 摩托車防護騎乘裝備市場:全球2025-2029
 摩托車騎乘裝備市場規模、佔有率、趨勢分析報告:按產品、通路、地區、細分市場預測,2025-2030 年
 摩托車騎行裝備市場,按產品、按材料、按配銷通路、按國家和地區 - 2024-2032 年行業分析、市場規模、市場佔有率和預測