


 |
市場調查報告書
商品編碼
2101680
2026 年至 2035 年燃燒後溶劑市場的商業機會、成長要素、產業趨勢與預測。Post Combustion Solvents Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球燃燒後溶劑市場預計到 2025 年將達到 4 億美元,年複合成長率為 9.1%,到 2035 年將達到 9.51 億美元。
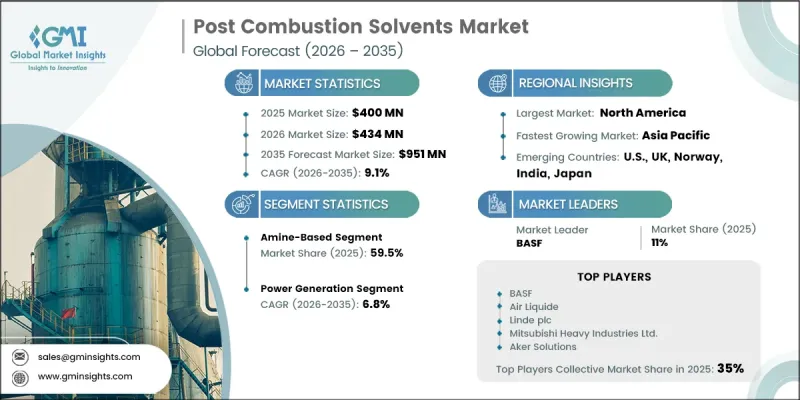
推動市場成長的因素包括:對碳捕獲技術的投資增加、全球脫碳進程的活性化,以及電氣化潛力有限的工業領域對減排解決方案日益成長的需求。燃燒後溶劑在碳捕獲系統中發揮至關重要的作用,因為它們能夠透過化學吸收過程,在燃料燃燒後從工業廢氣中分離出二氧化碳。隨著各行各業的公司尋求切實可行的解決方案,以在保持營運連續性的同時減少現有設施的排放,這項技術的重要性日益凸顯。碳定價機制的擴展、政府氣候目標的發展以及捕碳封存(CCS)基礎設施的日益普及,都為市場發展創造了有利條件。發電、重工業和製造業等產業正擴大將基於溶劑的碳捕獲系統視為實現減排目標的途徑。隨著碳管理策略日趨完善,對兼具高性能、低營運成本和永續性的高效溶劑技術的需求預計將顯著成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 4億美元 |
| 預計金額 | 9.51億美元 |
| 複合年成長率 | 9.1% |
燃燒後溶劑市場正受到發電、石油天然氣和工業領域日益成長的需求影響,這些領域採用傳統能源轉換方法仍難以有效減少排放。儘管電力和石油天然氣產業的需求依然顯著,但隨著碳減排要求日益嚴格,鋼鐵和水泥等產業預計將成為主要的成長要素。市場也在不斷演變,傳統胺基溶劑供應商與提供先進專有溶劑技術的供應商之間的界限日益清晰。通用溶劑製造商主要在供給能力和成本效益方面競爭,而專業技術開發公司則透過智慧財產權、製程最佳化、性能保證和長期營運支援來創造價值。預計這種不斷變化的競爭格局將在整個預測期內影響投資策略和供應商定位。
胺基溶劑憑藉其廣泛的商業性應用、成熟的生產網路和可靠的化學性能,預計到2025年將佔據59.5%的市場佔有率。傳統的胺基溶液仍然是碳捕集應用中廣泛接受的選擇,尤其是在營運商優先考慮可靠性、易於部署和與現有工業系統相容性的情況下。其良好的運作記錄和廣泛的可用性繼續鞏固了該領域在溶劑型碳捕集技術領域的主導地位。
預計到2025年,發電業將佔據39%的市場佔有率,並在2035年之前以6.8%的複合年成長率成長。位於主要工業區的現有火力發電廠仍然為碳捕集技術的部署提供了巨大的機遇,因為基於溶劑的燃燒後處理系統可以與現有的燃燒和廢氣排放基礎設施整合。這些解決方案與運作中的發電資產高度相容,使其成為減少現有電廠排放的首選方法。
預計2025年,北美燃燒後溶劑市佔率將達到35.5%,年複合成長率(CAGR)為7.5%。該地區強勁的市場地位得益於有利的碳管理政策、完善的工業基礎設施以及對碳捕獲項目不斷成長的投資。支持碳儲存和減排的財政獎勵提高了工業和能源領域碳捕獲專案的經濟可行性,從而促進了溶劑型碳捕獲技術的更廣泛應用。
燃燒後溶劑市場集中度適中,主要參與者包括三菱重工、BASF、阿克解決方案、林德集團和液化空氣集團。燃燒後溶劑市場的企業正透過技術研發、策略合作以及拓展碳捕集解決方案組合來鞏固其市場地位。參與企業市場的企業正投資研發先進的溶劑配方,旨在提高二氧化碳吸收效率、降低能耗並提升營運效率。他們也致力於與工業營運商和專案開發商建立合作關係,以擴大技術應用範圍並確保長期發展機會。研發投入的增加正助力製造商開發兼具環境效益和成本優勢的新一代溶劑解決方案。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 原物料供應商
- 溶劑配製商和製造商
- 工程、採購及施工(EPC)承包商
- 終端用戶企業
- 溶劑回收和廢棄物管理業務
- 技術與創新展望
- 新的消化系統配置
- 沼氣氣體純化技術的進步
- 利用智慧消化器和物聯網技術進行監測技術的創新。
- 共消化技術與多原料體系的進步
- 監理情勢
- 全球氣候變遷架構推動強制性碳捕獲與封存(CCS)的實施。
- 歐盟排放交易體系(EU ETS)與碳邊境調節機制(CBAM)
- 溶劑排放標準和環境許可證
- 各國具體的碳捕集與封存政策框架
- 影響產業的因素
- 促進因素
- 嚴格的全球脫碳目標和碳定價機制
- 在難以減少排放的行業中,對二氧化碳捕集技術的工業需求日益成長。
- 政府應提供強力的獎勵和財政支持,以促進碳捕獲與封存技術的引入。
- 產業潛在風險與挑戰
- 高昂的營運成本和溶劑劣化問題
- 促進因素
- 成長潛力分析
- 波特的分析
- PESTLE分析
- 人工智慧和生成式人工智慧對市場的影響
- 人工智慧改變了現有的溶劑配方和篩檢流程。
- 生成式人工智慧的應用案例與實施藍圖
- 人工智慧在碳捕集與封存(CCS)營運中的風險、限制與監管考量
- 技術與創新展望
- 第一代溶劑(MEA/DEA)
- 第二代混合胺和受阻胺溶劑
- 第三代先進溶劑
- 低用水量和非水溶劑的發展現狀
- 流程整合創新及目前生產狀況
第4章 競爭情勢
- 介紹
- 企業市佔率分析:按地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場規模及預測:依溶劑類型分類,2022-2035年
- 胺基
- 氨基
- 胺基酸鹽
- 離子液體
- 碳酸鹽型
- 混合/攪拌
- 其他
第6章 市場規模及預測:依部署方式分類,2022-2035年
- 小規模/模組化規模
- 中號
- 大規模
第7章 市場規模及預測:依最終用途分類,2022-2035年
- 發電
- 鋼
- 水泥製造
- 石油和天然氣
- 化工
- 其他
第8章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 挪威
- 荷蘭
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 拉丁美洲
- 巴西
第9章:公司簡介
- Air Liquide
- Aker Solutions
- Axens
- BASF
- Carbon Clean Solutions Ltd.
- Chevron Phillips Chemical Company
- DOW Inc.
- Evonik Industries
- Fluor Corporation
- Huntsman Corporation
- INEOS Oligomers
- ION Engineering
- Linde PLC
- Mitsubishi Heavy Industries, Ltd.
- Nouryon
- Shell Catalysts & Technologies
- Solvay
- Svante Technologies Inc.
The Global Post Combustion Solvents Market was valued at USD 400 million in 2025 and is estimated to grow at a CAGR of 9.1% to reach USD 951 million by 2035.
The market growth is driven by increasing investments in carbon capture technologies, rising global decarbonization efforts, and the growing requirement for emissions reduction solutions across industries with limited electrification potential. Post combustion solvents play a critical role in carbon capture systems by enabling the separation of CO2 from industrial exhaust streams after fuel combustion through chemical absorption processes. Technology continues to gain importance as industries seek practical solutions for reducing emissions from existing facilities while maintaining operational continuity. Expanding carbon pricing frameworks, government climate targets, and increasing adoption of carbon capture and storage (CCS) infrastructure are creating favorable conditions for market development. Industries including power generation, heavy manufacturing, and processing sectors are increasingly evaluating solvent-based capture systems as a pathway toward achieving emission reduction goals. As carbon management strategies become more advanced, the demand for efficient solvent technologies with improved performance, lower operating costs, and enhanced sustainability characteristics is expected to increase significantly.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $400 Million |
| Forecast Value | $951 Million |
| CAGR | 9.1% |
The post combustion solvents market is shaped by rising adoption across power generation, oil & gas, and industrial sectors where emission reduction remains challenging through conventional energy transition methods. While power and oil & gas industries continue to contribute significant demand, sectors such as steel and cement are expected to become major growth contributors as carbon reduction requirements become increasingly stringent. The market is also evolving through a clear distinction between conventional amine-based solvent suppliers and advanced proprietary solvent technology providers. Commodity solvent producers compete primarily through supply capabilities and cost efficiency, whereas specialized technology developers create value through intellectual property, process optimization, performance guarantees, and long-term operational support. This evolving competitive structure is expected to influence investment strategies and supplier positioning throughout the forecast period.
The amine-based solvents segment accounted for 59.5% share in 2025, supported by their extensive commercial adoption, established production networks, and proven chemical performance. Conventional amine solutions continue to serve as widely accepted options for carbon capture applications, particularly where operators prioritize reliability, lower implementation complexity, and compatibility with existing industrial systems. Their established operational history and broad availability continue to support their leading position within solvent-based carbon capture technologies.
The power generation segment held 39% share in 2025, growing at a CAGR of 6.8% through 2035. Existing thermal power facilities across major industrial regions continue to represent significant opportunities for carbon capture deployment, as solvent-based post combustion systems can be integrated with existing combustion and exhaust infrastructure. The compatibility of these solutions with operating power assets makes them a preferred approach for reducing emissions from established generation facilities.
North America Post Combustion Solvents Market accounted for 35.5% share in 2025 and is expected to grow at a CAGR of 7.5%. The region's strong market position is supported by favorable carbon management policies, established industrial infrastructure, and increasing investment in carbon capture projects. Financial incentives supporting carbon storage and emission reduction initiatives are improving the economic feasibility of carbon capture projects across industrial and energy applications, encouraging greater deployment of solvent-based capture technologies.
The post combustion solvents market is moderately concentrated, with leading companies including Mitsubishi Heavy Industries Ltd., BASF, Aker Solutions, Linde plc, and Air Liquide. Companies operating in the post combustion solvents market are strengthening their market presence through technology development, strategic collaborations, and expansion of carbon capture solution portfolios. Market participants are investing in advanced solvent formulations designed to improve CO2 absorption efficiency, reduce energy consumption, and enhance operational performance. Companies are also focusing on partnerships with industrial operators and project developers to expand technology adoption and secure long-term opportunities. Increasing investments in research and development are helping manufacturers develop next-generation solvent solutions with improved environmental performance and cost advantages.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Business trends
- 2.1.2 Solvent type trends
- 2.1.3 Deployment trends
- 2.1.4 End use trends
- 2.1.5 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material suppliers
- 3.1.2 Solvent formulators & manufacturers
- 3.1.3 Engineering, Procurement & Construction (EPC) contractors
- 3.1.4 End-user operators
- 3.1.5 Solvent reclaiming & waste management providers
- 3.2 Technology & innovation landscape
- 3.2.1 Emerging digester configurations
- 3.2.2 Biogas upgrading technology advances
- 3.2.3 Smart digester & IoT-enabled monitoring innovations
- 3.2.4 Co-digestion technology advances & multi-feedstock systems
- 3.3 Regulatory landscape
- 3.3.1 Global climate frameworks driving CCS mandates
- 3.3.2 EU Emissions Trading System (EU ETS) & Carbon Border Adjustment Mechanism (CBAM)
- 3.3.3 Solvent emission standards & environmental permitting
- 3.3.4 Country-specific CCS policy frameworks
- 3.4 Industry impact forces
- 3.4.1 Growth drivers
- 3.4.1.1 Stringent global decarbonization targets and carbon pricing mechanisms
- 3.4.1.2 Rising industrial demand for CO2 capture in hard-to-abate sectors
- 3.4.1.3 Strong government incentives and funding for CCS deployment
- 3.4.2 Industry pitfalls and challenges
- 3.4.2.1 High operational costs and solvent degradation issues
- 3.4.1 Growth drivers
- 3.5 Growth potential analysis
- 3.6 Porter's analysis
- 3.6.1 Bargaining power of suppliers
- 3.6.2 Bargaining power of buyers
- 3.6.3 Threat of new entrants
- 3.6.4 Threat of substitute
- 3.6.5 Intensity of competitive rivalry
- 3.7 PESTEL analysis
- 3.7.1 Political factors
- 3.7.2 Economic factors
- 3.7.3 Social factors
- 3.7.4 Technological factors
- 3.7.5 Environmental factors
- 3.7.6 Legal factors
- 3.8 Impact of AI and generative AI on the market (Driven by primary research)
- 3.8.1 AI-driven disruption of existing solvent formulation & screening
- 3.8.2 GenAI use cases & adoption roadmap
- 3.8.3 Risks, limitations & regulatory considerations for AI in CCS operations
- 3.9 Technology & innovation landscape
- 3.9.1 First-generation solvents (MEA/DEA)
- 3.9.2 Second-generation blended & hindered amine solvents
- 3.9.3 Third-generation advanced solvents
- 3.9.4 Water-lean & non-aqueous solvent development status
- 3.9.5 Process integration innovations & production landscape
Chapter 4 Competitive Landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East & Africa
- 4.2.5 Latin America
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Size and Forecast, By Solvent type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Amine-based
- 5.3 Ammonia-based
- 5.4 Amino acid salt
- 5.5 Ionic liquid
- 5.6 Carbonate-based
- 5.7 Blended/mixed
- 5.8 Others
Chapter 6 Market Size and Forecast, By Deployment, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Small/modular scale
- 6.3 Medium-scale
- 6.4 Large-scale
Chapter 7 Market Size and Forecast, By End Use, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Power generation
- 7.3 Iron & steel
- 7.4 Cement manufacturing
- 7.5 Oil & gas
- 7.6 Chemical industry
- 7.7 Others
Chapter 8 Market Size and Forecast, By Region, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.2.3 Mexico
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 Norway
- 8.3.4 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 South Korea
- 8.4.5 Australia
- 8.5 Middle East & Africa
- 8.5.1 Saudi Arabia
- 8.5.2 UAE
- 8.6 Latin America
- 8.6.1 Brazil
Chapter 9 Company Profiles
- 9.1 Air Liquide
- 9.2 Aker Solutions
- 9.3 Axens
- 9.4 BASF
- 9.5 Carbon Clean Solutions Ltd.
- 9.6 Chevron Phillips Chemical Company
- 9.7 DOW Inc.
- 9.8 Evonik Industries
- 9.9 Fluor Corporation
- 9.10 Huntsman Corporation
- 9.11 INEOS Oligomers
- 9.12 ION Engineering
- 9.13 Linde PLC
- 9.14 Mitsubishi Heavy Industries, Ltd.
- 9.15 Nouryon
- 9.16 Shell Catalysts & Technologies
- 9.17 Solvay
- 9.18 Svante Technologies Inc.

 全球燃燒後溶劑市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 碳回收溶劑、吸附劑和薄膜:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)二氧化碳捕集溶劑和固體吸附劑:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 直接空氣回收化學品市場預測至2034年-按化學品類型、回收技術、再生製程、純度等級、最終用戶及地區分類的全球分析碳捕集膜市場預測至2034年-全球分析(依膜材料、膜結構、分離製程、回收技術、應用、最終用戶及地區分類)
 碳捕獲市場規模、佔有率和成長分析:按技術、服務、應用、最終用戶產業和地區分類-2026-2033年產業預測2034年點源二氧化碳捕集市場預測-按捕集技術、捕集介質、部署規模、最終用戶和地區分類的全球分析碳捕集發電廠市場預測—全球分析(按捕集技術、發電廠類型、捕集方法、最終用戶和地區分類)—2034年
 碳捕獲化學品市場規模、佔有率和趨勢分析報告:按化學品、應用、地區和細分市場分類(2026-2033 年)
 排放權交易市場:按交易類型、最終用途和地區分類