


 |
市場調查報告書
商品編碼
2083048
汽車數據貨幣化平台市場機會、成長要素、產業趨勢分析及2026-2035年預測In-Vehicle Data Monetization Platforms Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

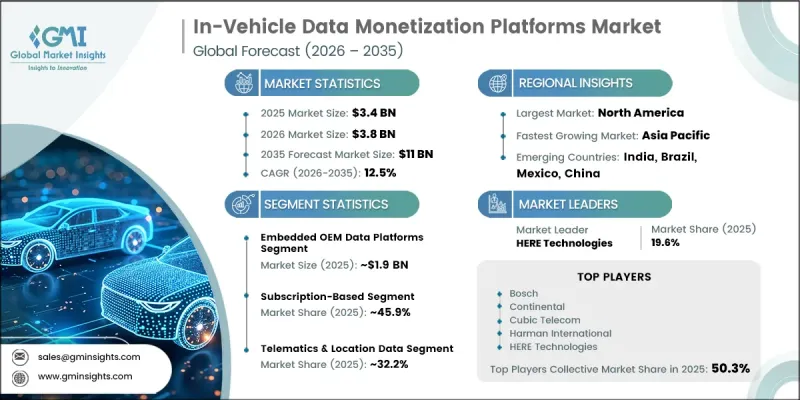
2025 年全球車載數據貨幣化平台市場價值為 34 億美元,預計到 2035 年將以 12.5% 的複合年成長率成長至 110 億美元。
隨著全球汽車產業對聯網汽車的普及加速,車載數據貨幣化平台市場也迅速擴張。汽車製造商正將先進的互聯解決方案、嵌入式感測器和智慧軟體整合到現代汽車中,在車輛的整個生命週期中產生大量的運行和行為數據。這些資訊支援廣泛的應用,包括車輛診斷、零件性能監控、遠端資訊處理、交通最佳化、預測性維護和互聯出行服務。隨著汽車產業向電動車、聯網汽車和軟體定義汽車轉型,製造商越來越意識到車輛產生的數據是一種寶貴的商業資產,可以創造傳統汽車銷售之外的持續商機。對數位生態系統和互聯出行平台的投入不斷增加,促使原始設備製造商 (OEM) 擴展其資料貨幣化能力,同時加強與客戶參與。同時,雲端運算、人工智慧和分析技術的進步正在提升安全、有效率地處理、管理和商業化車輛數據的能力。這些技術進步不斷重塑經營模式,並推動全球車載數據貨幣化平台市場的持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 34億美元 |
| 預計金額 | 110億美元 |
| 複合年成長率 | 12.5% |
預計2025年,嵌入式OEM數據平台市佔率將達57%,市場規模將達19億美元。該細分市場持續保持主導地位,是因為嵌入式平台能夠透過整合連接系統直接存取關鍵的車輛資訊。隨著軟體定義車輛架構的日益普及,製造商越來越依賴嵌入式資料平台來支援分析、遠端服務、預測性維護、駕駛員洞察和車輛性能監控。聯網汽車技術的持續發展預計將在整個預測期內進一步鞏固該細分市場的主導地位。
訂閱模式佔據45.9%的市場佔有率,預計到2025年將創造16億美元的收入。聯網汽車、數位化旅遊服務和軟體驅動型汽車平台的強勁成長正在加速對訂閱經營模式的需求。這些經常性收入模式使用戶能夠持續存取互聯服務、車輛分析、維護資訊、遠端資訊處理解決方案和出行相關應用,同時幫助服務供應商建立長期客戶關係並獲得穩定的經常性收入。
預計到2025年,美國車載數據貨幣化平台市場規模將達到11.4億美元,這主要得益於聯網汽車的日益普及以及消費者對基於使用量的保險計劃接受度的不斷提高。基於遠端資訊處理技術的保險解決方案的不斷擴展,持續推動聯網汽車數據在整個汽車生態系統中的更廣泛應用。美國高度發展的技術環境、強大的數位基礎設施以及汽車技術供應商的積極參與,進一步促進了車輛生成數據的商業化,並持續支持整個車載數據貨幣化平台市場的創新。
全球車載數據貨幣化平台市場的主要參與者包括HERE Technologies、哈曼國際、博世、Cubic Telecom、大陸集團、AWS和TomTom International。這些公司正透過投資先進的數據分析、雲端平台、人工智慧和安全的聯網汽車生態系統來增強其競爭優勢。產業相關人員不斷提升軟體功能,改善聯網汽車平台之間的互通性,並擴大與汽車製造商的合作,以加速平台的普及應用。各公司也優先考慮網路安全、合規性和資料隱私,以建立客戶信任,同時支援互聯出行解決方案的大規模部署。持續的研發投入使各公司能夠實施創新的數位服務和可擴展的貨幣化模式,從而產生持續的收入。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 全球聯網汽車的快速普及
- 對基於使用量的保險和個人化出行服務的需求日益成長
- OEM廠商的收入多元化策略超越了汽車銷售領域
- 擴大法規結構,強制要求資料存取和互通性。
- 產業潛在風險與挑戰
- 資料隱私法規與消費者同意的障礙(GDPR、CCPA)
- 整個OEM生態系統缺乏標準化的資料格式。
- 市場機遇
- ADAS和自動駕駛感測器數據的商業化
- 車載商務和訂閱服務作為新的收入來源
- 將電動車 (EV) 電池和充電行為數據貨幣化
- 促進因素
- 技術與創新展望
- 最新科技趨勢
- 基於雲端的車輛資料平台(OEM後端)
- 嵌入式資訊娛樂操作系統(IVI系統)
- 新興技術
- 邊緣人工智慧車載運算平台
- 面向聯網汽車數據的聯邦學習
- 最新科技趨勢
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國 - 加州消費者隱私法案 (CCPA) / CPRA
- 美國 -德克薩斯州資料隱私和安全法案 (TDPSA)
- 加拿大 - 加拿大消費者隱私法
- 歐洲
- 歐盟資料法
- 歐盟一般資料保護規則(GDPR)
- 亞太地區
- 中國—中國汽車資料安全管理法規
- 日本-日本個人資訊保護法(APPI)
- LATAM
- 巴西 - 巴西資料保護法 (LGPD)
- 阿根廷 - 阿根廷個人資料保護法
- 中東和非洲
- 阿拉伯聯合大公國聯邦法規
- 沙烏地阿拉伯-沙烏地阿拉伯個人資料保護法
- 北美洲
- 波特的分析
- PESTLE分析
- 成本細分分析
- 專利分析
- 網路安全與功能安全分析
- 平台架構的演變
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依平台分類,2022-2035年
- 嵌入式 OEM 資料平台
- 售後市場和遠端資訊處理設備平台
- 獨立數據聚合和市場平台
第6章 市場估計與預測:依資料類型分類,2022-2035年
- 遠端資訊處理和位置數據
- 駕駛員行為與使用數據
- 車輛健康狀況和診斷數據
- 資訊娛樂系統和車載數據
- ADAS和安全數據
- 環境和背景數據
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 里程保險(UBI)
- 預測性保護
- 車隊管理
- 車載商務和廣告
- 智慧城市與交通管理
- 交通行動服務(MaaS)
- 其他
第8章 市場估算與預測:依經營模式,2022-2035年
- 基於訂閱
- 按需計量收費/基於API
- 利潤分享
- 數據市場/交易平台
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 瑞典
- 挪威
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 越南
- 新加坡
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 智利
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 世界公司
- HERE Technologies
- Harman
- TomTom
- INRIX
- Verizon Connect
- Stellantis
- Bosch
- Lear
- Cubic Telecom
- Continental
- Amazon Web Services(AWS)
- 當地公司
- CARUSO
- High Mobility
- Mojio
- Smartcar
- Freeeway
- Telenav
- 新興企業
- Motorq
- Sibros Technologies
- Aeris
The Global In-Vehicle Data Monetization Platforms Market was valued at USD 3.4 billion in 2025 and is estimated to grow at a CAGR of 12.5% to reach USD 11 billion by 2035.
The in-vehicle data monetization platforms market is expanding rapidly as connected vehicle adoption continues to accelerate across the global automotive industry. Automakers are integrating advanced connectivity solutions, embedded sensors, and intelligent software into modern vehicles, generating significant volumes of operational and behavioral data throughout the vehicle lifecycle. This information supports a broad range of applications, including vehicle diagnostics, component performance monitoring, telematics, traffic optimization, predictive maintenance, and connected mobility services. As the automotive sector transitions toward electric, connected, and software-defined vehicles, manufacturers are increasingly recognizing vehicle-generated data as a valuable business asset capable of creating recurring revenue opportunities beyond conventional vehicle sales. Growing investments in digital ecosystems and connected mobility platforms are encouraging original equipment manufacturers to expand their data monetization capabilities while strengthening long-term customer engagement. At the same time, advances in cloud computing, artificial intelligence, and analytics are improving the ability to process, manage, and commercialize vehicle data securely and efficiently. These technological developments continue to reshape business models and support sustained growth across the global in-vehicle data monetization platforms market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.4 Billion |
| Forecast Value | $11 Billion |
| CAGR | 12.5% |
In 2025, the embedded OEM data platforms segment held 57% share, generating USD 1.9 billion. The segment continues to dominate because embedded platforms provide direct access to critical vehicle information through integrated connectivity systems. As software-defined vehicle architectures become more common, manufacturers increasingly rely on embedded data platforms to support analytics, remote services, predictive maintenance, driver insights, and vehicle performance monitoring. Continued expansion of connected vehicle technologies is expected to reinforce the segment's leading position throughout the forecast period.
The subscription-based segment accounted for 45.9% share, generating USD 1.6 billion in 2025. Strong growth in connected vehicles, digital mobility services, and software-enabled automotive platforms has accelerated demand for subscription-based business models. These recurring revenue models provide continuous access to connected services, vehicle analytics, maintenance insights, telematics solutions, and mobility-related applications while enabling service providers to build long-term customer relationships and generate stable recurring income.
U.S. In-Vehicle Data Monetization Platforms Market generated USD 1.14 billion in 2025, supported by increasing adoption of connected vehicles and growing consumer acceptance of usage-based insurance programs. Expanding implementation of telematics-based insurance solutions continues to encourage broader utilization of connected vehicle data across the automotive ecosystem. The country's well-developed technology landscape, strong digital infrastructure, and active participation of automotive technology providers continue to strengthen the commercialization of vehicle-generated data while supporting innovation across the in-vehicle data monetization platforms market.
The leading companies operating in the global in-vehicle data monetization platforms market include HERE Technologies, Harman International, Bosch, Cubic Telecom, Continental, AWS, and TomTom International. Companies operating in the global in-vehicle data monetization platforms market are strengthening their competitive position by investing in advanced data analytics, cloud-based platforms, artificial intelligence, and secure connected vehicle ecosystems. Industry participants continue to enhance software capabilities, improve interoperability across connected vehicle platforms, and expand partnerships with automotive manufacturers to increase platform adoption. Businesses are also prioritizing cybersecurity, regulatory compliance, and data privacy to build customer confidence while supporting large-scale deployment of connected mobility solutions. Continuous investment in research and development enables companies to introduce innovative digital services and scalable monetization models that generate recurring revenue.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Platform
- 2.2.3 Data Type
- 2.2.4 Application
- 2.2.5 Business Model
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid Growth in Connected Vehicle Penetration Globally
- 3.2.1.2 Rising Demand for Usage-Based Insurance & Personalized Mobility Services
- 3.2.1.3 OEM Revenue Diversification Strategies Beyond Vehicle Sales
- 3.2.1.4 Expanding Regulatory Frameworks Mandating Data Access & Interoperability
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Data Privacy Regulations & Consumer Consent Barriers (GDPR, CCPA)
- 3.2.2.2 Lack of Standardized Data Formats Across OEM Ecosystems
- 3.2.3 Market opportunities
- 3.2.3.1 Monetization of ADAS & Autonomous Driving Sensor Data
- 3.2.3.2 In-Vehicle Commerce & Subscription Services as Emerging Revenue Streams
- 3.2.3.3 Electric Vehicle (EV) Battery & Charging Behavior Data Monetization
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 Cloud-based Vehicle Data Platforms (OEM Backends)
- 3.3.1.2 Embedded Infotainment Operating Systems (IVI Systems)
- 3.3.2 Emerging technologies
- 3.3.2.1 Edge AI In-Vehicle Computing Platforms
- 3.3.2.2 Federated Learning for Connected Vehicle Data
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 US - California Consumer Privacy Act (CCPA) / CPRA
- 3.6.1.2 US - Texas Data Privacy and Security Act (TDPSA)
- 3.6.1.3 Canada - Canada's Consumer Privacy Protection Act
- 3.6.2 Europe
- 3.6.2.1 EU - EU Data Act
- 3.6.2.2 EU - General Data Protection Regulation (GDPR)
- 3.6.3 Asia Pacific
- 3.6.3.1 China - China's Provisions on Automotive Data Security Management
- 3.6.3.2 Japan - Japan's Act on the Protection of Personal Information (APPI)
- 3.6.4 LATAM
- 3.6.4.1 Brazil - Brazilian Data Protection Law (LGPD)
- 3.6.4.2 Argentina - Argentina's Personal Data Protection Act
- 3.6.5 MEA
- 3.6.5.1 UAE - Federal Decree Law
- 3.6.5.2 Saudi Arabia - Saudi Arabia's Personal Data Protection Law
- 3.6.1 North America
- 3.7 Porter analysis
- 3.8 PESTEL analysis
- 3.9 Cost breakdown analysis
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Cybersecurity & Functional Safety Analysis
- 3.12 Platform Architecture Evolution
- 3.13 Impact of AI and Generative AI on the Market
- 3.13.1 AI Driven Disruption of Existing Business Models
- 3.13.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.13.3 Risks Limitations and Regulatory Considerations
- 3.14 Sustainability and environmental aspects
- 3.14.1 Sustainable practices
- 3.14.2 Waste reduction strategies
- 3.14.3 Energy efficiency in production
- 3.14.4 Eco-friendly Initiatives
- 3.14.5 Carbon footprint considerations
- 3.15 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.15.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.15.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.15.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Platform, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Embedded OEM Data Platforms
- 5.3 Aftermarket & Telematics Device Platforms
- 5.4 Independent Data Aggregation & Marketplace Platforms
Chapter 6 Market Estimates and Forecast, By Data Type, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Telematics & Location Data
- 6.3 Driver Behavior & Usage Data
- 6.4 Vehicle Health & Diagnostics Data
- 6.5 Infotainment & In-Cabin Data
- 6.6 ADAS & Safety Data
- 6.7 Environmental & Contextual Data
Chapter 7 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Usage-Based Insurance (UBI)
- 7.3 Predictive Maintenance
- 7.4 Fleet Management
- 7.5 In-Vehicle Commerce & Advertising
- 7.6 Smart Cities & Traffic Management
- 7.7 Mobility-as-a-Service (MaaS)
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Business Model, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 Subscription-Based
- 8.3 Pay-Per-Use / API-Based
- 8.4 Revenue Sharing
- 8.5 Data Marketplace / Exchange
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Netherlands
- 9.3.7 Sweden
- 9.3.8 Norway
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Vietnam
- 9.4.7 Singapore
- 9.4.8 Malaysia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Chile
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 HERE Technologies
- 10.1.2 Harman
- 10.1.3 TomTom
- 10.1.4 INRIX
- 10.1.5 Verizon Connect
- 10.1.6 Stellantis
- 10.1.7 Bosch
- 10.1.8 Lear
- 10.1.9 Cubic Telecom
- 10.1.10 Continental
- 10.1.11 Amazon Web Services (AWS)
- 10.2 Regional players
- 10.2.1 CARUSO
- 10.2.2 High Mobility
- 10.2.3 Mojio
- 10.2.4 Smartcar
- 10.2.5 Freeeway
- 10.2.6 Telenav
- 10.3 Emerging players
- 10.3.1 Motorq
- 10.3.2 Sibros Technologies
- 10.3.3 Aeris

 全球車載數據貨幣化平台市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 汽車數據貨幣化:全球市場
 2026年全球汽車數據貨幣化平台市場報告
 汽車資料貨幣化:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)汽車數據貨幣化平台市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測
 汽車資料市場預測至2034年-全球資料分析(按資料類型、資料來源、車輛類型、驅動系統、部署模式、資料所有權、應用程式、最終使用者和地區分類)生成式人工智慧在自動駕駛汽車訓練資料產生中的應用:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 汽車資料管理市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測汽車資料貨幣化市場預測至2034年:按資料類型、貨幣化模式、部署模式、收入來源、應用、最終用戶和地區分類的全球分析全球汽車數據分析市場規模、佔有率、趨勢和成長分析報告(2026-2034)