


 |
市場調查報告書
商品編碼
2071289
重型卡車市場機會、成長要素、產業趨勢分析及2026-2035年預測。Heavy Duty Trucks Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球重型卡車市場預計到 2025 年將達到 3,083 億美元,年複合成長率為 4.8%,到 2035 年將達到 4,755 億美元。
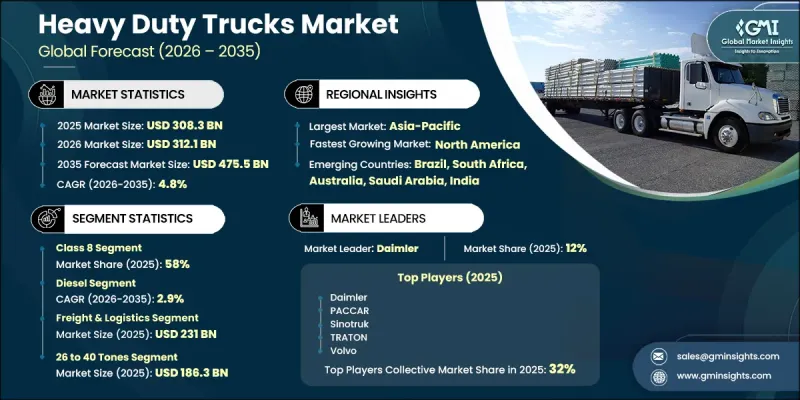
全球貨運量的成長、工業生產的擴張以及國內和跨境物流網路中對更高效長途運輸日益成長的需求,共同推動了這一市場的成長。區域間在貿易便利化和運輸基礎設施建設方面合作的深化,正在加速高容量卡車的普及,尤其是在長途貨運領域。物流連通性的不斷提升和運輸法規的協調統一,也促進了主要貿易走廊車輛運轉率的提高。此外,車輛設計、燃油效率和安全系統的技術進步,提高了營運效率,降低了車輛營運商的總擁有成本。向包括電動和動力來源推進系統在內的替代燃料技術的轉型,正在重塑競爭格局,並加速貨運永續性進程。電子商務的蓬勃發展、工業全球化以及供應鏈的現代化,進一步提升了全球對重型卡車的需求。為了滿足日益嚴格的環保標準和不斷變化的物流需求,車輛營運商越來越重視高性能、耐用性和低排放氣體的車輛。這些因素共同作用,穩步推動已開發市場和新興市場的長期市場擴張。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 3083億美元 |
| 預計金額 | 4755億美元 |
| 複合年成長率 | 4.8% |
新冠疫情徹底改變了產業格局,導致全球汽車市場生產停擺、供應鏈崩壞,汽車製造業急劇放緩。復甦進程並不均衡,隨著物流網路逐步恢復穩定,交付延遲和需求波動依然存在。半導體短缺進一步限制了產能,導致疫情期間車輛供不應求,更換週期創下歷史新低。隨著供應狀況的改善,在貨運和物流業者積壓需求的推動下,市場訂單履行強勁復甦。同時,向電氣化和替代燃料的轉型正在重塑產業結構,製造商加大對更清潔動力系統的投資,以實現永續性目標。這些創新也有助於提升車輛性能、安全標準和營運效率,最終改變長途和跨區域貨運系統。
預計到2025年,8級卡車市佔率將達到58%,並在2026年至2035年間以19%的複合年成長率成長。該級別卡車在長途貨運中扮演著核心角色,高載重能力、長途行駛能力和卓越的運轉率仍然是其關鍵的營運要求。由於全球物流網路的擴張以及工業和商業領域貨運量的成長,該細分市場的需求持續增強。此外,先進動力系統在該細分市場的應用也不斷推進,氫能技術因其加氫週期短、運作里程廣等優勢,在長途運輸應用中備受關注。隨著車主對其車輛進行現代化改造,8級卡車與旨在提高效率和減少排放氣體的下一代行動解決方案的兼容性也日益增強。
到2025年,26-40噸級貨車市場規模將達到1,863億美元。此細分市場主要包括牽引車-拖車組合,廣泛應用於成熟物流走廊的區域間和長途貨運。國際貿易量的成長和工業供應鏈中散貨運輸的擴張是推動該細分市場成長的主要因素。此外,運輸路線沿線基礎設施連接性的提升和貨物密度的增加也促進了對該重量級車輛的持續需求,使其成為全球物流運營的核心要素。
預計到2025年,中國重型卡車市場規模將達到1,072億美元,這主要得益於快速的工業擴張、大規模的基礎設施建設以及貨運網路的持續成長。強大的國內製造業實力、大規模的物流需求以及對交通運輸現代化持續投入,鞏固了中國在該領域的主導地位。此外,中國正大力推動整個交通運輸產業的永續性發展,進一步促進了現代化、節能型重型卡車解決方案的普及應用。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 原物料供應商
- 零件供應商
- 製造商
- 服務供應商
- 分銷管道
- 最終用途
- 成本結構
- 利潤率
- 每個階段增加的價值
- 垂直整合趨勢
- 顛覆者
- 供應商情況
- 影響因素
- 促進因素
- 貨運走廊的擴張和全球貿易的流動
- 對老舊柴油車的更換需求強勁。
- 法規主導的車輛更換
- 合約物流和第三方貨運承運商的成長
- 產業潛在風險與挑戰
- 新一代卡車的高資本密集度
- 缺乏可擴展的零排放基礎設施
- 市場機遇
- 區域間交通的逐步電氣化
- 自動駕駛和半自動駕駛卡車運輸的興起
- 轉向以總擁有成本 (TCO) 為重點的採購方式
- 數位車隊生態系統與運轉率最佳化
- 促進因素
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- ACT法規
- 美國環保署第三階段
- 歐洲
- 二氧化碳排放標準
- 歐6/下一代標準
- 亞太地區
- 排放目標
- 中國六號標準
- 拉丁美洲
- 巴西 Proconve P8
- 墨西哥的EPA合規標準
- 中東和非洲
- 沙烏地阿拉伯2030願景綠色舉措
- 南非電動車退稅計劃
- 北美洲
- 技術與創新展望
- 最新技術
- 新興技術
- 波特的分析
- PESTLE分析
- 專利分析
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 貿易數據分析
- 區域內貿易趨勢—數量與價值趨勢
- 進出口走廊分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 設計最佳化自動化
- 用於需求預測的供應鏈人工智慧
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 競爭定位矩陣
- 戰略展望矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
第5章 市場估算與預測:依卡車分類,2022-2035年
- 七年級
- 八年級
第6章 市場估計與預測:以噸位產能分類,2022-2035年
- 16-26噸
- 26-40噸
- 超過40噸
第7章 市場估價與預測:依車軸分類,2022-2035年
- 4x2
- 6x2
- 6x4
- 6x6
- 其他
第8章 市場估算與預測:依促進因素分類,2022-2035年
- 柴油引擎
- 電池式電動車(BEV)
- 混合動力汽車和插電式混合動力汽車(HEV/PHEV)
- 燃料電池電動車(FCEV)
- 其他
第9章 市場估計與預測:依馬力分類,2022-2035年
- 不足300馬力
- 300HP~400HP
- 400HP~500HP
- 500馬力或以上
第10章 市場估價與預測:依輸電類型分類,2022-2035年
- 手排變速箱
- 自動變速箱
- 自動手排變速箱(AMT)
第11章 市場估價與預測:依應用領域分類,2022-2035年
- 貨運/物流
- 建築和採礦
- 公共產業服務
- 其他
第12章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 比利時
- 荷蘭
- 瑞典
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 新加坡
- 韓國
- 越南
- 印尼
- 泰國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第13章:公司簡介
- 世界公司
- Daimler Truck
- Volvo
- TRATON
- Iveco
- DAF Trucks
- Ford Trucks
- TATRA Trucks
- Hyundai Motor
- Isuzu Motors
- Dongfeng Motor
- Hino Motors
- 當地公司
- GINAF Trucks
- BMC Automotive
- Kamaz
- Sisu Auto
- BYD
- SANY
- Sinotruk
- 新興企業
- Einride
- Windrose
The Global Heavy Duty Trucks Market is valued at USD 308.3 billion in 2025 and is estimated to grow at a CAGR of 4.8% to reach USD 475.5 billion by 2035.
The market growth is driven by rising global freight movement, expanding industrial output, and stronger demand for long-haul transportation efficiency across domestic and cross-border logistics networks. Increasing alignment between regions on trade facilitation and transport infrastructure development is strengthening the deployment of high-capacity trucks, particularly for long-distance cargo movement. Continuous improvements in logistics connectivity and harmonization of transport regulations are also enhancing fleet utilization across key trade corridors. In addition, technological advancements in vehicle design, fuel efficiency, and safety systems are improving operational productivity and lowering total cost of ownership for fleet operators. The shift toward alternative fuel technologies, including electric and hydrogen-based propulsion systems, is reshaping the competitive landscape and accelerating sustainability adoption in freight transportation. Growing e-commerce penetration, industrial globalization, and supply chain modernization are further reinforcing demand for heavy-duty trucks worldwide. Fleet operators are increasingly prioritizing high-performance, durable, and low-emission vehicles to meet tightening environmental standards and evolving logistics requirements. These combined factors are steadily supporting long-term market expansion across developed and emerging economies.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $308.3 Billion |
| Forecast Value | $475.5 Billion |
| CAGR | 4.8% |
The COVID-19 pandemic significantly disrupted the industry landscape, as COVID-19 pandemic triggered production shutdowns, supply chain breakdowns, and a sharp slowdown in vehicle manufacturing activity across global markets. This was followed by a period of uneven recovery, marked by delayed deliveries and fluctuating demand patterns as logistics networks gradually stabilized. Semiconductor shortages further constrained production capacity, resulting in reduced vehicle availability and historically low replacement cycles during the disruption phase. Once supply conditions improved, the market experienced a strong rebound in order fulfillment, driven by accumulated demand across freight and logistics operators. At the same time, the transition toward electrification and alternative fuel adoption is redefining the industry structure, with manufacturers increasingly investing in cleaner propulsion systems to meet sustainability goals. These innovations are also enhancing vehicle performance, safety standards, and operational efficiency, ultimately transforming long-haul and regional freight transportation systems.
The Class 8 segment held a 58% share in 2025, and it is projected to grow at a CAGR of 19% from 2026 to 2035. This category plays a central role in long-distance freight movement, where high payload capacity, extended driving range, and superior uptime performance remain critical operational requirements. Demand within this segment continues to strengthen due to the expansion of global logistics networks and rising freight volumes across industrial and commercial sectors. The segment is also witnessing increasing integration of advanced propulsion systems, as hydrogen-based technologies gain traction for long-haul applications due to faster refueling cycles and extended operational range compared to other emerging alternatives. As fleet operators modernize their assets, Class 8 trucks are becoming increasingly aligned with next-generation mobility solutions designed to improve efficiency and reduce emissions.
The 26 to 40 tonnes category accounted for USD 186.3 billion in 2025. This segment primarily includes tractor-trailer configurations widely used for both regional and long-distance freight transportation across established logistics corridors. Growth in this category is supported by rising international trade volumes and increasing movement of bulk goods across industrial supply chains. Expanding infrastructure connectivity and higher freight density across transport routes are also contributing to sustained demand for vehicles in this weight range, making it a core component of global logistics operations.
China Heavy Duty Trucks Market generated USD 107.2 billion in 2025, owing to rapid industrial expansion, extensive infrastructure development, and continuous growth in freight transportation networks. Strong domestic manufacturing capabilities, large-scale logistics demand, and ongoing investments in transport modernization are reinforcing China's leadership position. The country is also advancing sustainability initiatives across its transportation sector, further supporting the adoption of modern and fuel-efficient heavy duty truck solutions.
Key players in the Global Heavy Duty Trucks Market include Daimler Truck, Volvo, TRATON, Iveco, DAF Trucks, Ford Trucks, TATRA Trucks, BYD, SANY, and Sinotruk. Companies operating in the heavy-duty trucks market are strengthening their position through electrification strategies, with strong investment in battery-electric and hydrogen fuel cell platforms to meet tightening emission regulations and decarbonization targets. They are also expanding global manufacturing footprints and regional assembly networks to reduce supply chain risk and improve delivery timelines. Another key approach involves integrating advanced telematics, predictive maintenance, and connected fleet management systems to enhance uptime and operational efficiency. Manufacturers are increasingly focusing on modular vehicle platforms that allow flexible customization for different freight applications. Strategic collaborations with logistics providers and energy companies are also accelerating infrastructure readiness, particularly for alternative fuel adoption. In addition, continuous R&D investment is supporting improvements in aerodynamics, lightweight materials, and powertrain efficiency.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Truck
- 2.2.2 Tonnage Capacity
- 2.2.3 Axle
- 2.2.4 Propulsion
- 2.2.5 Horsepower
- 2.2.6 Transmission
- 2.2.7 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.1.1 Raw material suppliers
- 3.1.1.2 Component suppliers
- 3.1.1.3 Manufacturers
- 3.1.1.4 Service providers
- 3.1.1.5 Distribution channel
- 3.1.1.6 End Use
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.1.1 Supplier landscape
- 3.2 Impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Expansion of freight corridors & global trade flows
- 3.2.1.2 Strong replacement demand from aging diesel fleets
- 3.2.1.3 Regulatory-driven fleet modernization
- 3.2.1.4 Growth of contract logistics & third-party freight operators
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High capital intensity of new-generation trucks
- 3.2.2.2 Lack of scalable zero-emission infrastructure
- 3.2.3 Market opportunities
- 3.2.3.1 Gradual electrification of regional haul operations
- 3.2.3.2 Rise of autonomous and semi-autonomous trucking
- 3.2.3.3 Shift toward total cost of ownership (TCO)-driven purchasing
- 3.2.3.4 Digital fleet ecosystems & uptime optimization
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.1.1 ACT Regulation
- 3.5.1.2 EPA Phase 3
- 3.5.2 Europe
- 3.5.2.1 CO2 Emission Standards
- 3.5.2.2 Euro 6/Next Generation Standards
- 3.5.3 Asia-Pacific
- 3.5.3.1 Emission Reduction Targets
- 3.5.3.2 China-6 Standard
- 3.5.4 Latin America
- 3.5.4.1 Brazil Proconve P8
- 3.5.4.2 Mexico EPA-Aligned Standards
- 3.5.5 MEA
- 3.5.5.1 Saudi Vision 2030 Green Initiatives
- 3.5.5.2 South Africa EV Tax Rebates
- 3.5.1 North America
- 3.6 Technology and Innovation landscape
- 3.6.1 Current technologies
- 3.6.2 Emerging technologies
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by Primary Research)
- 3.10 Capacity & production landscape (Driven by Primary Research)
- 3.10.1 Installed capacity by region & key producer
- 3.10.2 Capacity utilization rates & expansion pipelines
- 3.11 Trade data analysis (Driven by Paid Research)
- 3.11.1 Intra Trade Flows - Volume & Value Trends
- 3.11.2 Import/Export Corridor Analysis
- 3.12 Impact of AI & generative AI on the market
- 3.12.1 AI-Driven Disruption of Existing Business Models
- 3.12.2 Automated design optimization
- 3.12.3 Supply chain AI for demand forecasting
- 3.12.4 GenAI use cases & adoption roadmap by segment
- 3.12.5 Risks, Limitations & Regulatory Considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios - Favorable Macro and Industry Tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
- 3.14 Sustainability and environmental aspects
- 3.14.1 Sustainable practices
- 3.14.2 Waste reduction strategies
- 3.14.3 Energy efficiency in production
- 3.14.4 Eco-friendly Initiatives
- 3.14.5 Carbon footprint considerations
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia-Pacific
- 4.2.4 Latin America
- 4.2.5 Middle East & Africa
- 4.3 Competitive positioning matrix
- 4.4 Strategic outlook matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
Chapter 5 Market Estimates & Forecast, By Truck, 2022 - 2035 ($Mn, Units)
- 5.1 Key trends
- 5.2 Class 7
- 5.3 Class 8
Chapter 6 Market Estimates & Forecast, By Tonnage Capacity, 2022 - 2035 ($Mn, units)
- 6.1 Key trends
- 6.2 16 to 26 tonnes
- 6.3 26 to 40 tonnes
- 6.4 Above 40 tonnes
Chapter 7 Market Estimates & Forecast, By Axle, 2022 - 2035 ($Mn, Units)
- 7.1 Key trends
- 7.2 4x2
- 7.3 6x2
- 7.4 6x4
- 7.5 6x6
- 7.6 Others
Chapter 8 Market Estimates & Forecast, By Propulsion, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 Diesel
- 8.3 Battery Electric Vehicles (BEV)
- 8.4 Hybrid & Plug-in Hybrid Electric Vehicles (HEV/PHEV)
- 8.5 Fuel Cell Electric Vehicles (FCEV)
- 8.6 Others
Chapter 9 Market Estimates & Forecast, By Horsepower, 2022 - 2035 ($Mn, Units)
- 9.1 Key trends
- 9.2 Below 300HP
- 9.3 300HP - 400HP
- 9.4 400HP - 500HP
- 9.5 500HP & Above
Chapter 10 Market Estimates & Forecast, By Transmission, 2022 - 2035 ($Mn, Units)
- 10.1 Key trends
- 10.2 Manual transmission
- 10.3 Automatic transmission
- 10.4 Automated Manual Transmission (AMT)
Chapter 11 Market Estimates & Forecast, By Application, 2022 - 2035 ($Mn, Units)
- 11.1 Key trends
- 11.2 Freight & Logistics
- 11.3 Construction & Mining
- 11.4 Utility Services
- 11.5 Others
Chapter 12 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 12.1 North America
- 12.1.1 US
- 12.1.2 Canada
- 12.2 Europe
- 12.2.1 UK
- 12.2.2 Germany
- 12.2.3 France
- 12.2.4 Italy
- 12.2.5 Spain
- 12.2.6 Belgium
- 12.2.7 Netherlands
- 12.2.8 Sweden
- 12.2.9 Russia
- 12.3 Asia Pacific
- 12.3.1 China
- 12.3.2 India
- 12.3.3 Japan
- 12.3.4 Australia
- 12.3.5 Singapore
- 12.3.6 South Korea
- 12.3.7 Vietnam
- 12.3.8 Indonesia
- 12.3.9 Thailand
- 12.4 Latin America
- 12.4.1 Brazil
- 12.4.2 Mexico
- 12.4.3 Argentina
- 12.5 MEA
- 12.5.1 South Africa
- 12.5.2 Saudi Arabia
- 12.5.3 UAE
Chapter 13 Company Profiles
- 13.1 Global players
- 13.1.1 Daimler Truck
- 13.1.2 Volvo
- 13.1.3 TRATON
- 13.1.4 Iveco
- 13.1.5 DAF Trucks
- 13.1.6 Ford Trucks
- 13.1.7 TATRA Trucks
- 13.1.8 Hyundai Motor
- 13.1.9 Isuzu Motors
- 13.1.10 Dongfeng Motor
- 13.1.11 Hino Motors
- 13.2 Regional players
- 13.2.1 GINAF Trucks
- 13.2.2 BMC Automotive
- 13.2.3 Kamaz
- 13.2.4 Sisu Auto
- 13.2.5 BYD
- 13.2.6 SANY
- 13.2.7 Sinotruk
- 13.3 Emerging players
- 13.3.1 Einride
- 13.3.2 Windrose

 美國重型卡車:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)重型卡車:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 重型卡車市場預測至 2034 年:按車輛類型、等級、燃料類型、動力系統、應用、最終用戶和地區進行全球分析。
 大型車輛市場:2026-2032年全球市場預測(依車輛類型、動力傳動系統、重量等級、應用及銷售管道)
 全球中型卡車轉向系統市場分析及預測(至2035年):按類型、產品、技術、組件、應用、材料類型、最終用戶、功能和安裝類型分類
 2026年全球重型工業機械市場報告2026年中型卡車轉向系統全球市場報告2026年全球重型卡車市場報告2026年全球重型卡車轉向系統市場報告
 全球重型卡車市場規模、佔有率、趨勢和成長分析報告(2026-2034)