

 |
市場調查報告書
商品編碼
2071223
工業相機市場機會、成長要素、產業趨勢分析及2026-2035年預測Industrial Camera Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

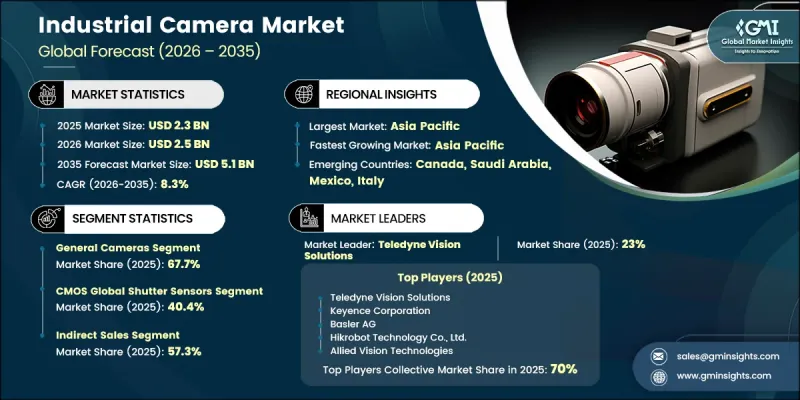
全球工業相機市場預計到 2025 年將達到 23 億美元,年複合成長率為 8.3%,到 2035 年將達到 51 億美元。
工業相機市場的成長主要得益於製造業整體機器視覺技術的日益普及、人工智慧(AI)成像系統的快速發展,以及傳統感測器技術向更先進、更具成本效益的成像架構的持續轉變。對自動化、生產效率和產品品質的日益重視促使製造商將先進的視覺系統整合到其營運中。與產品檢測、製程監控和品質保證相關的監管要求進一步推動了市場擴張。此外, 3D成像技術在工業自動化、物流和機器人系統中的日益普及,也為傳統檢測應用以外的領域創造了新的成長機會。影像解析度、影格速率、動態範圍效能和嵌入式處理技術的不斷進步,在提升系統整體效率的同時,也拓展了工業相機的應用範圍。隨著製造商越來越重視自動化和數據驅動的決策,工業相機正成為各行各業現代化生產基礎設施的關鍵組成部分。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 23億美元 |
| 預測金額 | 51億美元 |
| 複合年成長率 | 8.3% |
預計到2025年,工業相機市場規模將達到15.6億美元,市佔率高達67.7%,並有望在2026年至2035年間以8.1%的複合年成長率成長。這些相機系統是機器視覺環境中不可或缺的影像處理組件,廣泛應用於需要外部處理能力的各種應用中。其柔軟性、擴充性以及與各種工業影像處理系統的兼容性,持續支撐著製造業和自動化領域的強勁需求。
預計到2025年,間接銷售通路將佔據57.3%的市場佔有率,並在2035年之前以7.8%的複合年成長率成長。此銷售管道的重要性體現了系統整合商、專業經銷商和增值轉售商(VAR)在為終端用戶提供全面的機器視覺解決方案方面發揮的關鍵作用。工業相機採購決策通常包括技術諮詢、系統設計協助、光學配置、照明最佳化和軟體整合服務。因此,間接銷售網路仍然是重要的市場准入途徑,尤其對於那些尋求客製化機器視覺解決方案和專家實施支援的企業而言更是如此。
預計到2025年,北美工業相機市場將佔據29.3%的市場佔有率(價值約6.7億美元),並將在2035年之前維持8.1%的複合年成長率。該地區持續受益於對先進製造、工業自動化和高科技生產設施的大力投資。各行各業對精密檢測系統、自動化品管技術和先進成像解決方案日益成長的需求,正在推動全部區域的市場擴張。此外,對下一代製造基礎設施的持續投資以及機器視覺技術的日益普及,預計將為工業相機供應商提供長期的成長機會。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 機器視覺應用範圍擴大
- 工業4.0和智慧製造
- 影像技術的進步
- 產業潛在風險與挑戰
- 高初始投資
- 系統整合的複雜性
- 機會
- 人工智慧視覺系統
- 3D視覺和先進成像
- 促進因素
- 成長潛力分析
- 監理框架
- 機械安全標準(ISO 13849、IEC 62061)
- 出口管制和有關視覺組件的ITAR法規
- 區域 CE、FCC 和區域合規性要求
- 價格分析
- 2022-2025年歷史價格趨勢分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 貿易數據分析
- 依HS編碼分類的進出口量和進口額趨勢(852589)
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依相機類型分類,2022-2035年
- 通用相機
- 2D相機(臉部掃描)
- 3D相機(結構光和雷射三角測量)
- 影像擷取卡
- 智慧型相機
- 人工智慧智慧相機
- 3D智慧相機
- 其他(嵌入式視覺模組,基於FPGA的)
第6章 市場估算與預測:依介面類型分類,2022-2035年
- GigE Vision
- 5GigE/10GigE Vision
- USB 3.0(USB3 Vision)
- CoaXPress
- Camera Link 和 Camera Link HS
- 其他(火線、MIPI、Thunderbolt)
第7章 市場估計與預測:依感測器技術分類,2022-2035年
- CMOS全域百葉窗
- CMOS捲簾百葉窗
- CCD(電荷耦合元件)
- 短波紅外線/中波紅外線(紅外線感測器)
- 飛行時間(ToF)- 3D深度感測器
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 品質保證與檢驗
- 測量與計量
- 定位與導引
- 識別/OCR和可追溯性
- 預測性維護和狀態監測
- 其他(交通監控等)
第9章 市場估計與預測:依最終用途產業分類,2022-2035年
- 電子和半導體
- 車
- 食品/飲料
- 醫療保健和生命科學
- 物流/倉儲
- 石油和天然氣
- 金屬和採礦
- 航太/國防
- 其他(紡織品、包裝、智慧交通系統、研究)
第10章 市場估價與預測:依通路分類,2022-2035年
- 直銷
- 間接銷售
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第12章:公司簡介
- 世界公司
- Basler AG
- Teledyne Vision Solutions
- Cognex Corporation
- Keyence Corporation
- Allied Vision Technologies
- Baumer Group
- OMRON Corporation
- 當地公司
- IDS Imaging Development Systems GmbH
- JAI A/S
- SICK AG
- Hikrobot Technology Co., Ltd.
- Daheng Imaging Co., Ltd.
- Vieworks Co., Ltd.
- Toshiba Teli Corporation
- 新興企業
- XIMEA GmbH
- Photonfocus AG
- LUCID Vision Labs Inc.
- Emergent Vision Technologies Inc.
- Imperx Inc.
- Heliotis AG
- Tattile Srl
The Global Industrial Camera Market was valued at USD 2.3 billion in 2025 and is estimated to grow at a CAGR of 8.3% to reach USD 5.1 billion by 2035.
Growth in the Industrial Camera Market is driven by the increasing deployment of machine vision technologies across manufacturing industries, the growing adoption of artificial intelligence-enabled imaging systems, and the continued transition from traditional sensor technologies to more advanced imaging architectures that offer enhanced performance at competitive costs. Rising emphasis on automation, production efficiency, and product quality is encouraging manufacturers to integrate advanced vision systems into their operations. Regulatory requirements related to product inspection, process monitoring, and quality assurance are further supporting market expansion. In addition, the increasing adoption of three-dimensional imaging technologies in industrial automation, logistics, and robotic systems is creating new growth opportunities beyond conventional inspection applications. Continuous advancements in image resolution, frame rates, dynamic range capabilities, and embedded processing technologies are broadening the scope of industrial camera applications while improving overall system efficiency. As manufacturers increasingly prioritize automation and data-driven decision-making, industrial cameras are becoming a critical component of modern production infrastructure across multiple industries.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.3 Billion |
| Forecast Value | $5.1 Billion |
| CAGR | 8.3% |
The Industrial Camera Market is segmented accounted for 67.7% share in 2025, representing USD 1.56 billion, and is projected to grow at a CAGR of 8.1% during 2026-2035. These camera systems serve as essential imaging components within machine vision environments and are widely utilized in applications that require external processing capabilities. Their flexibility, scalability, and compatibility with a broad range of industrial imaging systems continue to support strong demand across manufacturing and automation sectors.
The indirect sales segment held a 57.3% share in 2025 and expected to grow at a CAGR of 7.8% through 2035. The prominence of this channel reflects the important role played by system integrators, specialized distributors, and value-added resellers in delivering complete machine vision solutions to end users. Industrial camera purchasing decisions often involve technical consultation, system design assistance, optical configuration, lighting optimization, and software integration services. As a result, indirect distribution networks remain a critical route to market, particularly for organizations seeking customized machine vision solutions and specialized deployment support.
North America Industrial Camera Market captured 29.3% share in 2025, equivalent to approximately USD 0.67 billion, and is anticipated to register a CAGR of 8.1% through 2035. The region continues to benefit from strong investments in advanced manufacturing, industrial automation, and high-technology production facilities. Growing demand for precision inspection systems, automated quality control technologies, and advanced imaging solutions across multiple industries is supporting market expansion throughout the region. In addition, ongoing investments in next-generation manufacturing infrastructure and increased adoption of machine vision technologies are expected to sustain long-term growth opportunities for industrial camera providers.
Leading companies operating in the Global Industrial Camera Market include Teledyne Vision Solutions, Keyence Corporation, Hikrobot, TKH / Allied Vision, Basler AG, IDS Imaging Development Systems, LUCID Vision Labs, Baumer Group, Sony Industrial Solutions, JAI A/S, Cognex Corporation, Omron Corporation, Vieworks, Imperx, and FLIR Systems (Industrial Division). Companies operating in the Industrial Camera Market are focusing on technological innovation, product portfolio expansion, and strategic partnerships to strengthen their market position. Leading manufacturers are investing heavily in research and development to enhance imaging performance, improve sensor capabilities, and integrate artificial intelligence and edge-processing technologies into industrial camera systems. Businesses are also expanding their presence through collaborations with automation providers, machine vision specialists, and industrial software companies to deliver comprehensive solutions for end users.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Camera type
- 2.2.3 Interface
- 2.2.4 Sensor technology
- 2.2.5 Application
- 2.2.6 End use industry
- 2.2.7 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing adoption of machine vision
- 3.2.1.2 Industry 4.0 & smart manufacturing
- 3.2.1.3 Advancements in imaging technology
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High initial investment
- 3.2.2.2 System integration complexity
- 3.2.3 Opportunities
- 3.2.3.1 AI-powered vision systems
- 3.2.3.2 3D vision & advanced imaging
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory framework
- 3.4.1 Machine safety standards (ISO 13849, IEC 62061)
- 3.4.2 Export control & ITAR regulations for vision components
- 3.4.3 CE, FCC & regional compliance requirements by geography
- 3.5 Pricing analysis (driven by primary research)
- 3.5.1 Historical price trend analysis (2022-2025)
- 3.5.2 Pricing strategy by player type (premium / value / cost-plus)
- 3.6 Trade data analysis (driven by paid database)
- 3.6.1 Import/export volume & value trends by HS Code (852589)
- 3.6.2 Key trade corridors & tariff impact
- 3.7 Impact of AI & generative AI on the market
- 3.7.1 AI-driven disruption of existing business models
- 3.7.2 GenAI use cases & adoption roadmap by segment
- 3.7.3 Risks, limitations & regulatory considerations
- 3.8 Capacity & production landscape (driven by primary research)
- 3.8.1 Installed capacity by region & key producer
- 3.8.2 Capacity utilization rates & expansion pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Camera Type, 2022 - 2035 (USD Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 General camera
- 5.2.1 2D camera (area scan)
- 5.2.2 3D camera (structured light & laser triangulation)
- 5.2.3 Frame grabber
- 5.3 Smart Camera
- 5.3.1 AI-based smart camera
- 5.3.2 3D smart camera
- 5.3.3 Others (embedded vision modules, FGPA-based)
Chapter 6 Market Estimates and Forecast, By Interface, 2022 - 2035 (USD Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 GigE Vision
- 6.3 5GigE / 10GigE Vision
- 6.4 USB 3.0 (USB3 Vision)
- 6.5 CoaXPress
- 6.6 Camera Link & Camera Link HS
- 6.7 Others (FireWire, MIPI, Thunderbolt)
Chapter 7 Market Estimates and Forecast, By Sensor Technology, 2022 - 2035 (USD Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 CMOS - global shutter
- 7.3 CMOS - rolling shutter
- 7.4 CCD (charge-coupled device)
- 7.5 SWIR / MWIR (infrared sensor)
- 7.6 Time-of-Flight (ToF) - 3D depth sensor
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 Quality assurance & inspection
- 8.3 Measurement & metrology
- 8.4 Positioning & guidance
- 8.5 Identification / OCR & traceability
- 8.6 Predictive & condition monitoring
- 8.7 Others (traffic monitoring, etc.)
Chapter 9 Market Estimates and Forecast, By End Use Industry, 2022 - 2035 (USD Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 Electronics & semiconductor
- 9.3 Automotive
- 9.4 Food & beverage
- 9.5 Healthcare & life sciences
- 9.6 Logistics & warehousing
- 9.7 Oil & gas
- 9.8 Metal & mining
- 9.9 Aerospace & defence
- 9.10 Others (textiles, packaging, ITS, research)
Chapter 10 Market Estimates and Forecast, By Distribution Channel, 2022 - 2035 (USD Billion) (Thousand Units)
- 10.1 Key trends
- 10.2 Direct sales
- 10.3 Indirect sales
Chapter 11 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion) (Thousand Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 Japan
- 11.4.3 India
- 11.4.4 Australia
- 11.4.5 South Korea
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 Middle East and Africa
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Global players
- 12.1.1 Basler AG
- 12.1.2 Teledyne Vision Solutions
- 12.1.3 Cognex Corporation
- 12.1.4 Keyence Corporation
- 12.1.5 Allied Vision Technologies
- 12.1.6 Baumer Group
- 12.1.7 OMRON Corporation
- 12.2 Regional players
- 12.2.1 IDS Imaging Development Systems GmbH
- 12.2.2 JAI A/S
- 12.2.3 SICK AG
- 12.2.4 Hikrobot Technology Co., Ltd.
- 12.2.5 Daheng Imaging Co., Ltd.
- 12.2.6 Vieworks Co., Ltd.
- 12.2.7 Toshiba Teli Corporation
- 12.3 Emerging players
- 12.3.1 XIMEA GmbH
- 12.3.2 Photonfocus AG
- 12.3.3 LUCID Vision Labs Inc.
- 12.3.4 Emergent Vision Technologies Inc.
- 12.3.5 Imperx Inc.
- 12.3.6 Heliotis AG
- 12.3.7 Tattile Srl

 工業相機市場規模:按類型、感測器類型、應用、地區和預測分類
 無人機系統用相機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)建築攝影機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 機器人相機支架市場預測—按類型、應用、最終用戶和地區分類的全球分析—2034年滑軌機器人相機市場預測至2034年—按類型、分銷管道、運動範圍、應用和地區分類的全球分析
 攝影系統市場:依產品類型、技術和地區分類
 2026年全球建築攝影解決方案市場報告
 凸輪端面加工系統市場規模、佔有率和成長分析:按操作技術、系統整合、葉片配置、車輛類型、銷售管道和地區分類 - 產業預測,2026-2033 年
 建築攝影解決方案市場:全球市場按產品類型、連接方式、應用和部署模式分類的預測 - 2026-2032 年全球建築攝影機市場規模、佔有率、趨勢和成長分析報告(2026-2034)