


 |
市場調查報告書
商品編碼
2071189
全履帶公路市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Full Truckload Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球全軌道公路市場預計到 2025 年將達到 1.46 兆美元,年複合成長率為 5.1%,到 2035 年將達到 2.39 兆美元。
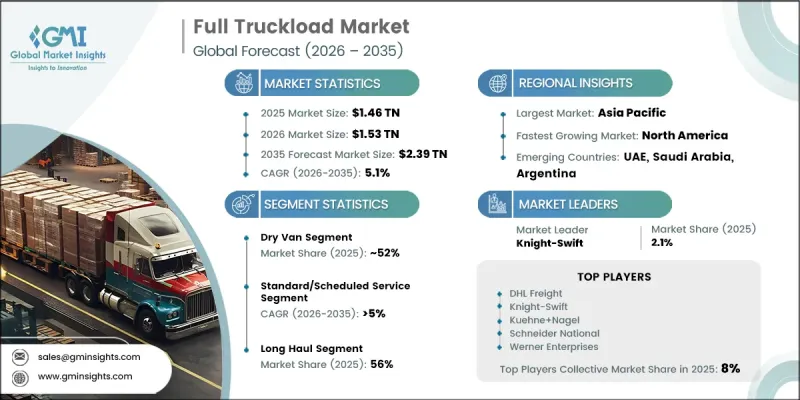
全卡車運輸市場的成長主要受不斷變化的貨運需求、日益複雜的供應鏈以及對可靠、專屬運輸解決方案日益成長的需求所驅動。電子商務的快速發展顯著改變了貨運模式,導致物流設施和配送網路之間對定期卡車運輸的需求不斷增加。隨著交付期望的不斷提高,托運人越來越依賴能夠提供更高效率、可預測性和速度的專屬運輸服務。這一趨勢正在減少對整合運輸模式的依賴,並為承運商和物流運營商創造更大的商機。此外,持續的供應鏈重組正在重塑貨運路線,從而增強對國內和區域間卡車運輸服務的需求。企業越來越重視供應鏈的韌性、營運的柔軟性以及與終端市場的接近性,這促進了卡車運輸需求的持續成長。這些因素,加上對物流基礎設施和貨運最佳化策略的持續投資,預計將支持全球全卡車運輸產業的長期成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 1.46兆美元 |
| 預測金額 | 2.39兆美元 |
| 複合年成長率 | 5.1% |
全球供應鏈的重組持續為全卡車公路運輸市場創造有利條件。企業正日益採用強調地域多元化和提升供應鏈應對力的採購和生產策略。這種轉變進一步增加了對國內和跨境運輸路線專用貨運能力的需求。隨著企業尋求更好地控制庫存流動和提高配送效率,全卡車公路運輸服務正成為現代物流營運中日益重要的組成部分。預計在預測期內,對本地化供應鏈網路的日益青睞將進一步擴大貨運量和運輸活動。
預計到2025年,乾貨車(乾貨拖車)市佔率將達到52%,並在2035年之前以4.5%的複合年成長率成長。該細分市場的主導地位得益於其多功能性和運輸各種貨物的能力。封閉式拖車仍廣泛用於運輸包裝商品、工業產品、消費品以及各種需要在運輸過程中保護的普通貨物。乾貨車運輸的柔軟性和營運效率使其成為眾多行業和應用領域首選的運輸方式。
預計到2025年,長途運輸市場佔有率將達到56%。長途運輸的成長主要得益於關鍵生產基地、物流樞紐和終端用戶市場之間貨運量的持續成長。製造商、零售商和物流服務供應商高度依賴長途卡車運輸解決方案來連接廣闊地域的供應鏈。貿易活動的活性化、物流網路的擴展以及貨運需求的成長預計將在整個預測期內推動長途運輸服務的強勁發展。
預計到2025年,北美整車運輸(FTL)市場規模將達到4,756億美元,並在2035年之前以6.3%的複合年成長率成長。由於先進的交通基礎設施、活躍的貨運活動以及不斷成長的物流投資,北美在全球市場擴張中繼續發揮核心作用。貨運需求的持續成長、履約配送能力的提升以及大規模的基礎設施投資,正在推動美國各地卡車運輸活動的增加。這些因素預計將確保北美繼續保持其在全球整車運輸市場成長中的主要驅動力地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 電子商務和最後一公里物流網路的成長
- 近岸外包和供應鏈本地化正在促進國內貨運發展。
- 對專用和合約容量解決方案的需求不斷成長
- 基礎設施投資計畫將推動建築貨運
- 產業潛在風險與挑戰
- 結構性司機短缺和高離職率
- 現貨票價供應過剩和長期停滯
- 保險費、燃油成本和維護成本的增加加重了負擔。
- 監理合規成本
- 市場機遇
- 推出數位化貨運代理商和貨物匹配平台
- 藥品和生鮮食品低溫運輸的擴展
- 自動駕駛卡車的商業化將減少對駕駛人的依賴。
- 新興市場物流基礎建設發展
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 聯邦汽車運輸業者安全法規(FMCSRs)
- 聯邦汽車運輸安全管理局(FMCSA)
- 美國運輸部(DOT)
- 強制使用電子記錄設備(ELD)
- 加拿大汽車運輸業者國家安全標準 (NSC)
- 歐洲
- 歐盟流動性方案
- 關於駕駛員工作時間和行車記錄器的規定
- 多式聯運指令
- 歐盟公路貨運運輸法規
- 關於危險貨物運輸的ADR規則
- 亞太地區
- 中國道路運輸法規
- 印度機動車輛法和中央機動車輛條例(CMVR)
- 澳洲國家重型車輛法 (NHVL)
- 日本道路運輸車輛法
- 東協過境便利架構協議(AFAFGIT)
- 拉丁美洲
- 巴西國家陸路運輸管理局 (ANTT) 貨運法規
- 巴西公路貨運登記系統(RNTRC)
- 墨西哥聯邦機動車運輸經營者法規
- 南方共同市場道路運輸協議
- 區域海關和跨境貨運法規
- 中東和非洲
- 海灣合作理事會統一海關法
- 沙烏地阿拉伯交通總局(TGA)制定的公路貨運法規
- 阿拉伯聯合大公國聯邦運輸管理局貨運法規
- 南非道路交通法(NRTA)
- 非洲自由貿易區(AfCFTA)貿易與運輸協定
- 北美洲
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 成本細分分析
- 專利分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 層級分類標準與選擇標準
- 層級定位矩陣:依收入、地區和創新能力分類
第5章 市場估價與預測:依車輛類型分類,2022-2035年
- 乾燒
- 冷藏
- 平板
- 油船
- 其他
第6章 市場估計與預測:依服務業分類,2022-2035年
- 標準/常規服務
- 遠徵服務
- 專屬合約服務
- 現貨市場服務
第7章 市場估計與預測:依運輸距離分類,2022-2035年
- 長途
- 當地交通
- 短程交通
第8章 市場估算與預測:依最終用途分類,2022-2035年
- 製造業
- 零售與電子商務
- 食品/飲料
- 建造
- 化工/石油
- 農業
- 其他
第9章 市場估算與預測:依燃料類型分類,2022-2035年
- 柴油引擎
- 天然氣
- BEV
- HEV
- FCEV
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐的
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 印尼
- 馬來西亞
- 新加坡
- 泰國
- 越南
- ANZ
- 拉丁美洲
- 巴西
- 阿根廷
- 墨西哥
- 中東和非洲
- UAE
- 沙烏地阿拉伯
- 南非
第11章:公司簡介
- 世界公司
- CEVA Logistics
- Dachser
- Delhivery
- DHL Freight
- DSV
- GEODIS
- Kuehne+Nagel
- Maersk Logistics
- Nippon Express
- Rhenus
- Sinotrans
- 當地公司
- Girteka
- Knight-Swift
- Schneider
- SF Express
- STEF
- TFI International
- Waberer's
- Werner
- 新興企業
- CJ Darcl
The Global Full Truckload Market was valued at USD 1.46 trillion in 2025 and is estimated to grow at a CAGR of 5.1% to reach USD 2.39 trillion by 2035.
Growth in the full truckload market is driven by evolving freight transportation requirements, increasing supply chain complexity, and the rising need for reliable, dedicated shipping solutions. The rapid expansion of e-commerce activities has significantly transformed freight movement patterns, leading to greater demand for scheduled truckload transportation between logistics facilities and distribution networks. As delivery expectations continue to accelerate, shippers are increasingly relying on dedicated transportation services that provide greater efficiency, predictability, and transit speed. This trend is reducing dependence on consolidated freight models and creating stronger revenue opportunities for carriers and logistics providers. In addition, ongoing supply chain realignment initiatives are reshaping freight corridors and strengthening demand for domestic and regional trucking services. Businesses are increasingly prioritizing supply chain resilience, operational flexibility, and proximity to end markets, contributing to sustained truckload transportation demand. These factors, combined with continued investment in logistics infrastructure and freight optimization strategies, are expected to support long-term expansion across the global full truckload industry.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $1.46 Trillion |
| Forecast Value | $2.39 Trillion |
| CAGR | 5.1% |
The restructuring of global supply chains continues to create favorable conditions for the full truckload market. Companies are increasingly adopting sourcing and manufacturing strategies that emphasize geographic diversification and improved supply chain responsiveness. This shift is generating additional demand for dedicated freight capacity across domestic and cross-border transportation routes. As organizations seek greater control over inventory movement and distribution efficiency, full truckload services are becoming an increasingly important component of modern logistics operations. The growing preference for regionalized supply networks is expected to further strengthen freight volumes and transportation activity throughout the forecast period.
The dry van segment accounted for 52% share in 2025 and is anticipated to grow at a CAGR of 4.5% through 2035. The segment's leading position is supported by its versatility and ability to transport a broad range of freight categories. Enclosed trailers remain widely utilized for the movement of packaged goods, industrial products, consumer merchandise, and various types of general cargo that require protection during transit. The flexibility and operational efficiency offered by dry van transportation continue to make it the preferred equipment type across numerous industries and shipping applications.
The long-haul segment represented 56% share in 2025. Growth in long-haul transportation continues to be supported by increasing freight movement between major production centers, distribution hubs, and end-user markets. Manufacturers, retailers, and logistics service providers rely heavily on long-distance trucking solutions to connect supply chains across broad geographic areas. Rising trade activity, expanding logistics networks, and increasing freight demand are expected to sustain strong utilization of long-haul transportation services throughout the forecast period.
North America Full Truckload Market generated USD 475.6 billion in 2025 and is projected to grow at a CAGR of 6.3% through 2035. The region continues to play a central role in global market expansion, supported by advanced transportation infrastructure, strong freight activity, and growing logistics investments. Continued growth in freight transportation demand, expanding fulfillment and distribution capabilities, and large-scale infrastructure investments are strengthening trucking activity throughout the country. These factors are expected to maintain North America's position as a major contributor to the growth of the global full truckload market.
Leading companies operating in the global full truckload market include DHL Freight, Kuehne+Nagel, CEVA, GEODIS, Knight-Swift, Schneider National, and Werner Enterprises. Companies operating in the full truckload market are adopting a variety of strategies to strengthen their market presence and enhance competitive positioning. Major industry participants are investing in fleet modernization, transportation management technologies, and digital freight platforms to improve operational efficiency and service quality. Many carriers are expanding their geographic coverage and strengthening logistics networks to better serve evolving customer requirements. Strategic acquisitions, partnerships, and capacity expansion initiatives enable companies to increase market share and improve service capabilities. Organizations are also leveraging advanced analytics, route optimization software, and real-time visibility tools to enhance fleet utilization and reduce operating costs.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.2 Sources, by region
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Vehicle
- 2.2.3 Service
- 2.2.4 Haul Distance
- 2.2.5 End Use
- 2.2.6 Fuel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growth of e-commerce & last-mile distribution networks
- 3.2.1.2 Near-shoring & supply chain regionalization boosting domestic freight
- 3.2.1.3 Rising demand for dedicated & contracted capacity solutions
- 3.2.1.4 Infrastructure investment programs driving construction freight
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Structural driver shortage & high turnover rates
- 3.2.2.2 Overcapacity & prolonged spot rate depression
- 3.2.2.3 Rising insurance, fuel & maintenance cost burden
- 3.2.2.4 Regulatory compliance costs
- 3.2.3 Market opportunities
- 3.2.3.1 Digital Freight Brokerage & Load Matching Platform Adoption
- 3.2.3.2 Cold Chain Expansion for Pharma & Perishable Goods
- 3.2.3.3 Autonomous Trucking Commercialization Reducing Driver Dependency
- 3.2.3.4 Emerging Market Logistics Infrastructure Build-Out
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.1.1 Federal Motor Carrier Safety Regulations (FMCSRs)
- 3.4.1.2 Federal Motor Carrier Safety Administration (FMCSA)
- 3.4.1.3 U.S. Department of Transportation (DOT)
- 3.4.1.4 Electronic Logging Device (ELD) Mandate
- 3.4.1.5 National Safety Code (NSC) for Motor Carriers - Canada
- 3.4.2 Europe
- 3.4.2.1 EU Mobility Package
- 3.4.2.2 Drivers' Hours and Tachograph Regulation
- 3.4.2.3 Combined Transport Directive
- 3.4.2.4 EU Road Freight Transport Regulations
- 3.4.2.5 ADR Regulations for Dangerous Goods Transport
- 3.4.3 Asia Pacific
- 3.4.3.1 China Road Transport Regulations
- 3.4.3.2 Indian Motor Vehicles Act & Central Motor Vehicle Rules (CMVR)
- 3.4.3.3 National Heavy Vehicle Law (NHVL) - Australia
- 3.4.3.4 Japanese Road Transport Vehicle Act
- 3.4.3.5 ASEAN Framework Agreement on the Facilitation of Goods in Transit (AFAFGIT)
- 3.4.4 Latin America
- 3.4.4.1 Brazilian National Land Transport Agency (ANTT) Freight Regulations
- 3.4.4.2 Brazilian Road Cargo Transport Registry (RNTRC)
- 3.4.4.3 Mexican Federal Motor Carrier Regulations
- 3.4.4.4 Mercosur Road Transport Agreement
- 3.4.4.5 Regional Customs and Cross-Border Freight Transport Regulations
- 3.4.5 Middle East & Africa
- 3.4.5.1 GCC Unified Customs Law
- 3.4.5.2 Saudi Transport General Authority (TGA) Road Freight Regulations
- 3.4.5.3 UAE Federal Transport Authority Freight Transport Regulations
- 3.4.5.4 South African National Road Traffic Act (NRTA)
- 3.4.5.5 African Continental Free Trade Area (AfCFTA) Trade & Transport Protocols
- 3.4.1 North America
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price analysis (Driven by Primary Research)
- 3.8.1 Historical Price Trend Analysis
- 3.8.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.9 Cost breakdown analysis
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Impact of AI & generative AI on the market
- 3.11.1 AI-driven disruption of existing business models
- 3.11.2 GenAI use cases & adoption roadmap by segment
- 3.11.3 Risks, limitations & regulatory considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly Initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios - Favorable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Vehicle, 2022 - 2035 ($Mn, Fleet Size)
- 5.1 Key trends
- 5.2 Dry Van
- 5.3 Refrigerated
- 5.4 Flatbed
- 5.5 Tanker
- 5.6 Others
Chapter 6 Market Estimates & Forecast, By Service, 2022 - 2035 ($Mn)
- 6.1 Key trends
- 6.2 Standard/Scheduled Service
- 6.3 Expedited Service
- 6.4 Dedicated Contract Service
- 6.5 Spot Market Service
Chapter 7 Market Estimates & Forecast, By Haul Distance, 2022 - 2035 ($Mn, Fleet Size)
- 7.1 Key trends
- 7.2 Long Haul
- 7.3 Regional Haul
- 7.4 Short Haul
Chapter 8 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn, Fleet Size)
- 8.1 Key trends
- 8.2 Manufacturing
- 8.3 Retail & E-Commerce
- 8.4 Food & Beverage
- 8.5 Construction
- 8.6 Chemicals & Petroleum
- 8.7 Agriculture
- 8.8 Others
Chapter 9 Market Estimates & Forecast, By Fuel, 2022 - 2035 ($Mn, Fleet Size)
- 9.1 Key trends
- 9.2 Diesel
- 9.3 Natural gas
- 9.4 BEV
- 9.5 HEV
- 9.6 FCEV
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Fleet Size)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 UK
- 10.3.2 Germany
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Nordics
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 South Korea
- 10.4.5 Southeast Asia
- 10.4.5.1 Indonesia
- 10.4.5.2 Malaysia
- 10.4.5.3 Singapore
- 10.4.5.4 Thailand
- 10.4.5.5 Vietnam
- 10.4.6 ANZ
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Argentina
- 10.5.3 Mexico
- 10.6 MEA
- 10.6.1 UAE
- 10.6.2 Saudi Arabia
- 10.6.3 South Africa
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.2 CEVA Logistics
- 11.3 Dachser
- 11.4 Delhivery
- 11.5 DHL Freight
- 11.6 DSV
- 11.7 GEODIS
- 11.8 Kuehne+Nagel
- 11.9 Maersk Logistics
- 11.10 Nippon Express
- 11.11 Rhenus
- 11.12 Sinotrans
- 11.13 Regional Players
- 11.14 Girteka
- 11.15 Knight-Swift
- 11.16 Schneider
- 11.17 SF Express
- 11.18 STEF
- 11.19 TFI International
- 11.20 Waberer's
- 11.21 Werner
- 11.22 Emerging Players
- 11.23 CJ Darcl

 馬來西亞廂型車:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 2026-2030年全球零擔運輸市場
 整車公路運輸市場規模、佔有率和趨勢分析報告:按卡車類型、服務、運輸方式、最終用途、地區和細分市場預測(2026-2033 年)
 高空作業車市場規模、佔有率和成長分析:按車輛類型、驅動方式、工作高度、裝載方式、應用、最終用戶和地區分類-2026-2033年產業預測
 2026-2030年全球卡車運輸市場
 商用卡車市場機會、成長要素、產業趨勢分析及2026-2035年預測高空作業車市場機會、成長要素、產業趨勢分析及2026-2035年預測
 卡車運輸市場:按規模、應用和區域分類小包裹運輸市場:依運輸重量、最終用途產業和地區分類。
 2026年全球林業產品卡車運輸市場報告