


 |
市場調查報告書
商品編碼
2154955
生質乙醇酵母:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Bioethanol Yeast - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
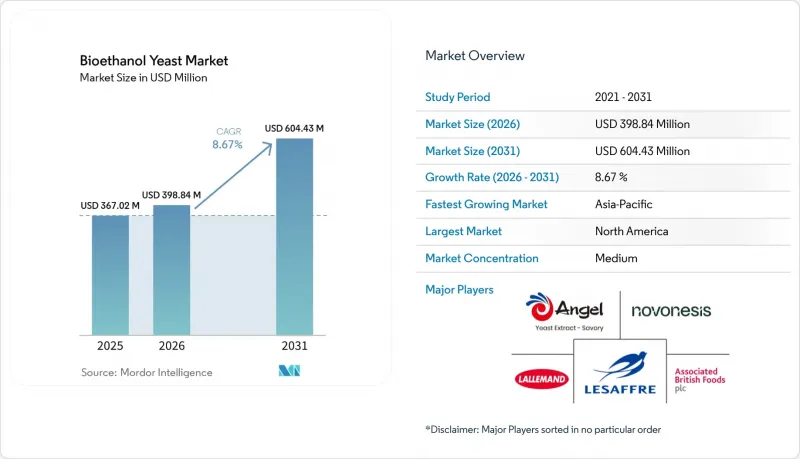
根據 Mordor Intelligence 預測,生質乙醇酵母市場將從 2025 年的 3.6702 億美元成長到 2026 年的 3.9884 億美元,到 2031 年達到 6.0443 億美元,2026 年至 2031 年的複合年成長率為 8.67%。
全球生質乙醇酵母市場趨勢與洞察
全球生質乙醇產量增加
各國生質乙醇生產和貿易的擴張推動了對專用發酵酵母的需求成長。隨著乙醇工廠產量的增加和運轉率的提高,對能夠加快發酵速度、提高乙醇產量並維持產品品質穩定的可靠酵母的需求日益成長。根據經濟合作暨發展組織(OECD)預測,全球乙醇貿易量將從2024年的110億升至2034年的119億升。然而,同期貿易量佔乙醇總產量的比例預計將從8.8%下降至8.2%,這表明主要市場的國內消費和生產將持續成長。乙醇產量和跨境貿易的擴張預計將為生質乙醇酵母,特別是高產量、高效率的菌株創造穩定的需求,這些菌株能夠幫助生產商縮短生產時間、最佳化工廠運作並提高整體經濟效益。
擴大與乙醇混合的義務
政府法規要求燃料供應商提高汽油中乙醇的摻混比例,從而為生質乙醇及其生產所使用的專用酵母創造了穩定且長期的需求。在美國,美國環保署 (EPA) 設定了到 2026 年可再生識別碼 (RIN) 的需求量為 258.2 億個,維持了先前設定的 2026 年和 2027 年生質燃料目標,即 150 億加侖。在印度,計劃於 2026 年推出含 20% 乙醇的“E20 汽油”,這將進一步提升該國對乙醇的需求。同樣,歐盟的《可再生能源指令 III》(RED III) 也設定了 2030 年可再生能源滿足交通運輸部門 29% 能源消耗的目標。這些政策為乙醇生產商提供了更清晰的需求前景,鼓勵他們投資研發高效、高性能的酵母菌株,用於玉米、甘蔗等傳統原料以及包括農業廢棄物在內的先進原料。
對發酵條件高度敏感
酵母對發酵條件高度敏感,這些因素會影響發酵穩定性、乙醇產量和植物生產力,進而阻礙全球生質乙醇酵母市場的成長。工業酵母會受到乙醇毒性、滲透壓、溫度波動、pH值變化、營養限制和污染物的影響,所有這些都會降低酵母的活力和發酵效率。發表在《真菌生物學》(Fungal Biology)上的一項研究指出,這些壓力因素會對乙醇產量和整體生產效率產生負面影響。同時,《FEMS酵母研究》(FEMS Yeast Research)強調了高密度發酵和木質纖維素衍生的抑制劑帶來的其他挑戰。因此,乙醇生產商可能需要針對特定菌株進行最佳化、製程控制和技術支持,這增加了操作的複雜性,並可能限制其在發酵條件難以控制的地區的應用。
細分市場分析
2025年,乾酵母佔據生質乙醇酵母市場67.73%的佔有率,繼續保持在該細分市場的領先地位。其較長的保存期限使生產商能夠長期儲存酵母,而不會影響生產的連續性。易於儲存、運輸和處理也進一步促進了其在乙醇生產設施中的廣泛應用。這種形式的酵母尤其適用於需要穩定且充足供應的大規模生產。其在商業發酵製程的成熟應用也持續支撐著整個生質乙醇產業的需求。
預計到2031年,液態酵母的複合年成長率將達到9.21%,成為成長最快的產品形態。其即用特性縮短了製備時間,並能更快啟動發酵。生產商擴大採用液態酵母來提高發酵效率、保持酵母性能穩定並最佳化乙醇產量。這種產品形態還能實現更可控的發酵過程,尤其適用於那些對營運效率要求極高的生產設施。預計對先進發酵技術的投資增加將進一步推動液態酵母市場的成長。
區域分析
2026年,北美佔據了生質乙醇酵母市場38.67%的佔有率。這主要得益於玉米乙醇生產的完善基礎設施,尤其是在美國。成熟的發酵設施、一體化的供應鏈以及基於可再生燃料標準(RFS)的支持性政策,持續為乙醇生產提供穩定的基礎。美國生產商越來越注重選擇能夠提高乙醇產量、縮短發酵週期並減少不良產品成分的酵母技術。對最佳化生產效率和營運成本的日益重視,進一步推動了先進酵母菌株的應用。加拿大和墨西哥也透過擴大乙醇生產和實施混合政策,為該地區的需求做出了貢獻。
亞太地區預計將成為成長最快的區域市場,到2031年將以9.75%的複合年成長率成長,這主要得益於乙醇摻混比例的擴大和國內產能投資的增加。將於2026年在印度全國實施的E20標準預計將顯著提升乙醇需求,並增加對高性能發酵解決方案的需求。 2025年11月,Novonesys在印度推出了「Innova Delta」系統,旨在支援在當地熱力和滲透條件下的發酵。由於乙醇摻混比例相對較低,中國市場的成長機會相對溫和,但政策發展可望改善長期需求。日本、澳洲和東南亞國家正在推動可再生燃料計畫並實現能源來源多元化,這些國家也為市場提供了進一步的成長空間。
歐洲、南美洲以及中東和非洲為生質乙醇酵母的應用提供了多樣化的機遇,這些機會受到原料供應、脫碳政策以及乙醇生產基礎設施成熟度的影響。歐洲的《可再生能源指令III》(RED III)日益關注溫室氣體排放績效和先進原料,從而推動了對能夠提高低碳乙醇生產製程效率的酵母解決方案的需求。南美洲仍然是重要的區域市場,這主要得益於巴西成熟的甘蔗乙醇產業和大規模發酵能力。中東和非洲是相對新興的市場,未來的需求將取決於基礎建設、原料供應以及支援性的法律規範。人們對可再生燃料和能源安全的日益關注可能會進一步促進全部區域的乙醇生產。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 全球生質乙醇產量增加
- 擴大與乙醇混合的義務
- 擴大高性能酵母菌株的應用
- 向高效發酵製程過渡
- 第二代生質乙醇的擴張
- 酵母菌株基因工程的進展
- 市場限制因素
- 對發酵條件高度敏感
- 特殊酵母菌株高成本
- 透過替代發酵技術展開競爭
- 生質乙醇產業對經濟狀況的依賴性
- 供應鏈分析
- 技術展望
- 監理展望
- 波特五力模型
第5章 市場規模與成長預測
- 按格式
- 乾酵母
- 液體酵母
- 依原料類型
- 甘蔗
- 小麥
- 玉米
- 其他
- 透過使用
- 工業乙醇
- 燃料乙醇
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 其他北美國家
- 歐洲
- 德國
- 英國
- 義大利
- 法國
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市場排名分析
- 公司簡介
- Novonesis A/S
- LALLEMAND Inc.
- Lesaffre
- AngelYeast Co., Ltd.
- Associated British Foods plc
- AB Mauri
- International Flavors and Fragrances Inc.
- DSM-Firmenich AG
- Leiber GmbH
- Alltech, Inc.
- Oriental Yeast Co., Ltd.
- Biorigin
- Cargill, Incorporated
- Archer Daniels Midland Company
- POET, LLC
- Green Plains Inc.
- Alto Ingredients, Inc.
- MicroBioGen Pty Ltd
- Xylogenics, Inc.
- Ferm Solutions, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the bioethanol yeast market is projected to increase from USD 367.02 million in 2025 to USD 398.84 million in 2026 and reach USD 604.43 million by 2031, registering a CAGR of 8.67% during 2026-2031.
Global Bioethanol Yeast Market Trends and Insights
Rising Global Bioethanol Production
Growing bioethanol production and trade across countries are increasing the need for specialized fermentation yeast. As ethanol plants produce larger volumes and operate at higher capacity, they require reliable yeast that can improve fermentation speed, increase ethanol yield, and support consistent production quality. According to the Organization for Economic Co-operation and Development (OECD), global ethanol trade is projected to rise from 11.0 billion liters in 2024 into 11.9 billion liters by 2034. However, trade's share of total ethanol production is expected to decline from 8.8% to 8.2% over the same period, indicating that domestic consumption and production will continue to grow in major markets. This expansion in ethanol production and cross-border trade is expected to create steady demand for bioethanol yeast, particularly high-yield and high-efficiency strains that help producers reduce production time, optimize plant operations, and improve overall process economics.
Expansion of Ethanol-Blending Mandates
Government mandates requiring fuel suppliers to blend more ethanol into gasoline are creating steady, long-term demand for bioethanol and the specialized yeast used to produce it. In the United States, the Environmental Protection Agency (EPA) finalized a requirement of 25.82 billion Renewable Identification Numbers (RINs) for 2026 and retained a conventional biofuel target of 15 billion gallons for both 2026 and 2027. India's rollout of E20 petrol, which contains 20% ethanol, in 2026 is also increasing the country's ethanol production needs. Similarly, the European Union's Renewable Energy Directive III (RED III) aims for renewable energy to account for 29% of transport energy use by 2030. These policies provide ethanol producers with clearer demand expectations and encourage them to invest in efficient, high-performance yeast strains for both conventional feedstocks, such as corn and sugarcane, and advanced feedstocks, including agricultural residues.
High Sensitivity to Fermentation Conditions
The high sensitivity of yeast to fermentation conditions can restrain the global bioethanol yeast market by affecting fermentation consistency, ethanol yield, and plant productivity. Industrial yeast is exposed to ethanol toxicity, osmotic pressure, temperature fluctuations, pH changes, nutrient limitations, and contaminants, all of which can reduce yeast viability and fermentation efficiency. Research published in Fungal Biology notes that these stresses can negatively affect ethanol yields and overall production efficiency, while FEMS Yeast Research highlights the additional challenges created by high-gravity fermentation and lignocellulosic inhibitors. Consequently, ethanol producers may require strain-specific optimization, process control, and technical support, increasing operational complexity and potentially limiting adoption where fermentation conditions are difficult to manage.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Second-Generation Bioethanol
- Growing Adoption of High-Performance Yeast Strains
- High Cost of Specialized Yeast Strains
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry Yeast accounted for 67.73% of the bioethanol yeast market in 2025, maintaining its leading position in the format segment. Its extended shelf life enables producers to store yeast for longer periods without compromising operational continuity. Ease of storage, transportation, and handling further supports its widespread use across ethanol production facilities. The format is particularly well-suited to large-scale operations that require a stable and readily available yeast supply. Its established application in commercial fermentation processes continues to support demand across the bioethanol industry.
Liquid Yeast is projected to grow at a 9.21% CAGR through 2031, making it the fastest-growing format segment. Its ready-to-use characteristics reduce preparation requirements and enable faster initiation of fermentation. Producers are increasingly adopting liquid yeast to improve fermentation efficiency, maintain consistent yeast performance, and optimize ethanol yields. The format can also support more controlled fermentation processes, particularly in facilities focused on operational efficiency. Growing investment in advanced fermentation technologies is expected to further support the expansion of the Liquid Yeast segment.
Complete Report Scope:
- By Format
- Dry Yeast
- Liquid Yeast
- By Feedstock Type
- Sugarcane
- Wheat
- Corn
- Others
- By Application
- Industrial Ethanol
- Fuel Ethanol
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 38.67% of the bioethanol yeast market in 2026, supported by the region's extensive corn-based ethanol production infrastructure, particularly in the United States. Established fermentation facilities, integrated supply chains, and supportive policies under the Renewable Fuel Standard continue to provide a stable foundation for ethanol production. U.S. producers are increasingly selecting yeast technologies based on their ability to improve ethanol yield, shorten fermentation cycles, and reduce unwanted by-products. The growing focus on production efficiency and operating cost optimization is further supporting the adoption of advanced yeast strains. Canada and Mexico also contribute to regional demand through expanding ethanol production and blending initiatives.
Asia Pacific is projected to be the fastest-growing regional market, expanding at a 9.75% CAGR through 2031, driven by increasing ethanol blending mandates and investments in domestic production capacity. India's nationwide E20 implementation in 2026 is expected to significantly strengthen ethanol demand and increase the need for high-performing fermentation solutions. In November 2025, Novonesis launched Innova Delta in India to support fermentation under local thermal and osmotic conditions. China offers a more moderate growth opportunity because of its relatively low ethanol blending rate, although policy developments could improve long-term demand. Japan, Australia, and Southeast Asian countries provide additional growth avenues as they advance renewable fuel programs and diversify energy sources.
Europe, South America, and the Middle East & Africa offer diverse opportunities for bioethanol yeast adoption, shaped by feedstock availability, decarbonization policies, and the maturity of ethanol production infrastructure. Europe's Renewable Energy Directive III (RED III) is increasing the focus on greenhouse gas performance and advanced feedstocks, supporting demand for yeast solutions that improve the efficiency of lower-carbon ethanol pathways. South America remains a key regional market, led by Brazil's well-established sugarcane ethanol industry and its large-scale fermentation capacity. The Middle East and Africa represent comparatively emerging markets, where future demand will depend on infrastructure development, feedstock availability, and supportive regulatory frameworks. Growing interest in renewable fuels and energy security could further support ethanol production initiatives across these regions.
- Novonesis A/S
- LALLEMAND Inc.
- Lesaffre
- AngelYeast Co., Ltd.
- Associated British Foods plc
- AB Mauri
- International Flavors and Fragrances Inc.
- DSM-Firmenich AG
- Leiber GmbH
- Alltech, Inc.
- Oriental Yeast Co., Ltd.
- Biorigin
- Cargill, Incorporated
- Archer Daniels Midland Company
- POET, LLC
- Green Plains Inc.
- Alto Ingredients, Inc.
- MicroBioGen Pty Ltd
- Xylogenics, Inc.
- Ferm Solutions, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global bioethanol production
- 4.2.2 Expansion of ethanol-blending mandates
- 4.2.3 Growing adoption of high-performance yeast strains
- 4.2.4 Shift toward high-efficiency fermentation processes
- 4.2.5 Expansion of second-generation bioethanol
- 4.2.6 Advancements in yeast strain engineering
- 4.3 Market Restraints
- 4.3.1 High sensitivity to fermentation conditions
- 4.3.2 High cost of specialized yeast strains
- 4.3.3 Competition from alternative fermentation technologies
- 4.3.4 Dependence on bioethanol industry economics
- 4.4 Supply Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Format
- 5.1.1 Dry Yeast
- 5.1.2 Liquid Yeast
- 5.2 By Feedstock Type
- 5.2.1 Sugarcane
- 5.2.2 Wheat
- 5.2.3 Corn
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Industrial Ethanol
- 5.3.2 Fuel Ethanol
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 Italy
- 5.4.2.4 France
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 South Africa
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials (if available), Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Novonesis A/S
- 6.4.2 LALLEMAND Inc.
- 6.4.3 Lesaffre
- 6.4.4 AngelYeast Co., Ltd.
- 6.4.5 Associated British Foods plc
- 6.4.6 AB Mauri
- 6.4.7 International Flavors and Fragrances Inc.
- 6.4.8 DSM-Firmenich AG
- 6.4.9 Leiber GmbH
- 6.4.10 Alltech, Inc.
- 6.4.11 Oriental Yeast Co., Ltd.
- 6.4.12 Biorigin
- 6.4.13 Cargill, Incorporated
- 6.4.14 Archer Daniels Midland Company
- 6.4.15 POET, LLC
- 6.4.16 Green Plains Inc.
- 6.4.17 Alto Ingredients, Inc.
- 6.4.18 MicroBioGen Pty Ltd
- 6.4.19 Xylogenics, Inc.
- 6.4.20 Ferm Solutions, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

 生物丁醇市場:全球市場預測,2026-2032年
 生質乙醇:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)用於熱電聯產的生物液體燃料市場:按燃料類型、轉化技術、原料來源、產能範圍和終端用戶產業分類-2026-2032年全球市場預測
 生質乙醇酵母市場規模、佔有率和成長分析:按產品類型、原料類型、應用、終端用戶產業、形態、發酵製程和地區分類-2026-2033年產業預測
 生物丁醇市場:依原料、應用、終端使用者產業及地區分類
 生物丁醇市場報告:按原料、應用、終端用戶產業和地區分類(2026-2034 年)
 2026年全球生質乙醇酵母市場報告2026年全球生質乙醇市場報告
 生質乙醇產能、產量、市場規模、平均價格及預測(2018-2034 年)
 生物液體熱電聯產市場-全球產業規模、佔有率、趨勢、機會及預測(依燃料類型、技術、地區及競爭格局分類,2021-2031年)