

 |
市場調查報告書
商品編碼
2154846
Fipronil:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Fipronil - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
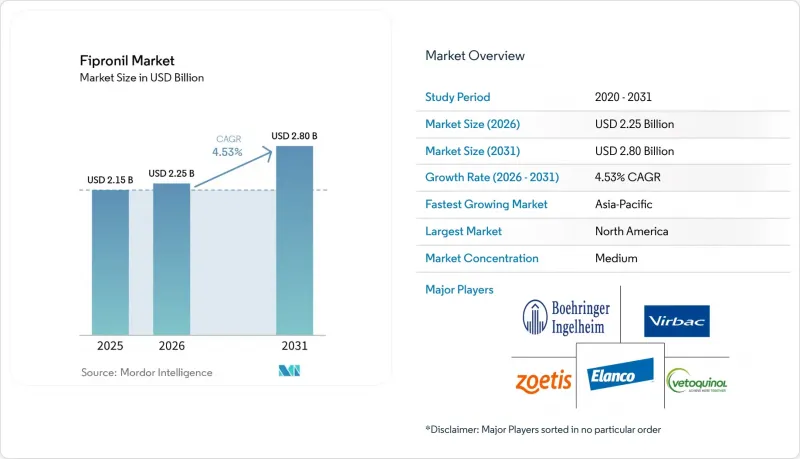
根據 Mordor Intelligence 預測,Fipronil市場規模將從 2025 年的 21.5 億美元成長到 2026 年的 22.5 億美元,然後在 2031 年達到 28 億美元,2026 年至 2031 年的複合年成長率為 4.53%。
全球Fipronil市場趨勢及洞察
寵物數量的增加和預防性醫療保健支出的增加。
寵物飼養仍然是美國家庭的重要支出,這為寄生蟲治療藥物創造了持續的需求基礎。到2025年,美國養狗家庭的比例將達到53%,即7,100萬戶。養貓家庭的比例將以每年5%的速度成長,到2025年將達到39%。 2025年,獸醫照護將佔寵物相關家庭支出的32.4%,其中養狗家庭的平均支出為598美元,養貓家庭的平均支出為529美元。 81.6%的養狗飼主和76.4%的養貓飼主就診的主要原因是預防性照護。這些消費模式支撐了Fipronil市場的發展,尤其是那些既可非處方購買又能獲得獸醫推薦的產品。
人們對跳蚤和蜱蟲傳播疾病的認知有所提高
隨著蜱蟲數量的增加,人們對持續預防跳蚤和蜱蟲的需求也日益成長。 2026年4月,因蜱蟲叮咬而前往急診室就診的人數達到2017年以來的最高水準。美國疾病管制與預防中心(CDC)估計,每年有3,100萬美國人被蜱蟲叮咬,約47.6萬人感染萊姆病。 2025年的一份報告發現,在北卡羅來納州西部接受檢查的成年肩胛硬蜱(Ixodes scapularis)中,39.6%攜帶伯氏疏螺旋體(Borrelia burgdorferi)。美國防蟲藥業協會(CAPC)對2026年的預測表明,蜱傳疾病的風險將持續存在於美國中西部北部、東北部和南部阿巴拉契亞山脈地區。這些因素表明,在Fipronil市場,每月定期使用外用預防產品是有效的。
與口服異噁唑啉類驅蟲藥的競爭
口服異噁唑啉類抗寄生蟲藥物為獸醫診所提供了一系列多寄生蟲治療方案,給藥間隔為1個月、2個月或12個月。根據禮來公司(Elanco)預測,到2025年9月,Credelio Quattro的年淨銷售額預計將達到1億美元。英國小動物獸醫協會(BSAVA)引用的一項針對犬貓的對照試驗表明,異噁唑啉類產品的跳蚤控制有效率高達99.1%至99.9%。給藥方便鞏固了這些產品在處方藥市場的地位,因為給藥方便性是處方藥市場的重要購買標準之一。然而,在非處方藥(OTC)、學名藥和價格敏感型銷售管道,Fipronil市場依然強勁。
細分市場分析
預計到2025年,滴劑和滴管劑型將佔Fipronil市場價值的51.5%。這些劑型在每月進行局部用藥的犬貓飼主中仍然很受歡迎。獸醫的長期推薦和零售店的廣泛供應支撐了它們的市場地位。非專利滴劑產品透過提供價格較低的替代品進一步刺激了需求。 KRKA的「Fyperix」系列產品表明,生物等效的Fipronil產品已在歐洲零售通路廣泛銷售。然而,由於消費者可以輕鬆比較類似產品,品牌溢價正面臨壓力。
預計到2031年,外用噴霧劑的複合年成長率將達到6.8%。柔軟性,適用於各種體重和年齡的動物,因此適合家庭和犬舍環境。一項2025年的研究表明,含有Fipronil的外用複合物在第2天至第14天對貓的跳蚤控制率達到100%,隨後在第3周至第7週的有效率達到92%至97%。洗髮精、浸浴劑、粉劑和噴粉持續滿足價格敏感型消費者和多寵家庭的需求。在已核准的牲畜產品類別中,外用製劑仍只佔很小的市場佔有率。例如,Seva公司的「Fiproline Duo」是一種高濃度含氟Fipronil腈的外用製劑,適用於牛。
預計到2025年,犬類將佔Fipronil市場價值的58.7%。由於犬類平均體重高於貓類,每次治療所需的劑量也較高,導致每個治療週期的收入增加。此外,預計到2025年,犬飼主在獸醫護理方面的支出將達到598美元,而貓飼主則為529美元,這表明犬飼主的支出更高。預計到2025年,美國養狗家庭的數量將達到7,100萬戶。這些因素共同支撐了對犬類外用驅蟲產品的持續需求。
預計到2031年,貓市場將以7.0%的複合年成長率成長。這一成長主要受寵物貓數量增加以及對貓專用驅蟲藥需求的推動。在美國,預計到2025年,貓的擁有率將年增5%,達到39%。某些犬類驅蟲藥的安全隱患也推動了對貓用Fipronil腈產品的需求。伊斯坦堡的一項研究發現,在所研究的貓群跳蚤中未發現Fipronil抗藥性突變,這證實了貓用驅蟲藥在新興的伴侶動物市場中的重要性。在蜱蟲肆虐的熱帶地區,獲準的牲畜驅蟲藥也提供了小規模但穩定的需求來源。
區域分析
預計到2025年,北美將佔全球Fipronil市場的43.5%。該地區受益於龐大的寵物數量和成熟的非處方藥零售網路。預計美國寵物產業的支出將在2025年達到1,580億美元,並在2026年達到1,650億美元。預計到2026年4月,因蜱蟲叮咬而前往急診室就診的人數將達到2017年以來的最高水平,這將推動對易於獲取的蜱蟲防治產品的需求。伴侶動物寄生蟲委員會(CAPC)指出,美國中西部北部、東北部和南部阿巴拉契亞山脈地區的風險增加。
歐洲是Fipronil產品的第二大區域市場佔有率。自從Fipronil專利到期並進入零售通路以來,學名藥生產商對市場競爭格局產生了影響。在法國、德國和英國,來自多家製造商的多種產品系列廣受歡迎。英國的監管變化(可能要求在銷售點提供專家建議)可能會改變Fipronil的分銷模式。 Vilbach 預計到 2025 年,西歐伴侶動物驅蟲藥市場將持續成長,並計劃在德國、荷蘭和斯洛維尼亞逐步推廣一種長效(8 個月)的寄生蟲預防項圈。
預計到2031年,亞太地區將以5.6%的複合年成長率成長,成為成長最快的區域市場。這一成長主要得益於中國、印度、韓國和東南亞寵物數量的不斷成長。中國一線城市和印度大都會圈獸醫中心是高階寵物醫療保健的關鍵樞紐。東南亞市場仍處於發展初期,價格親民可望促進寵物養成定期驅蟲的習慣。 Vilbach預測,以固定外匯計算,2025年第一季中國伴侶動物市場將成長9%,日本將成長6.5%。南美洲、中東和非洲市場仍處於發展初期,大量未經驅蟲的寵物為基礎驅蟲產品提供了巨大的市場機會。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 寵物數量增加和預防性醫療保健支出增加
- 人們對跳蚤和蜱蟲傳播疾病的認知不斷提高
- Fipronil腈的局部用藥的可負擔性
- 拓展獸藥電子商務與訂閱/續訂服務
- 為減少動物和人類之間的寄生蟲感染,人們呼籲採用「同一健康」理念。
- 市場限制因素
- 與口服異噁唑啉類抗寄生蟲藥物的競爭
- 獸用外用體外寄生蟲控制劑的環境檢驗。
- 對跳蚤的抵抗力下降,對治療的信心降低。
- 產品誤用、仿冒偽劣產品以及跨物種安全風險
- 供應鏈分析
- 監理情勢
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 點塗製劑及移液製劑
- 外部噴塗
- 洗髮精和浸泡
- 粉末和粉塵
- 獲準用於畜牧業的塗抹型製劑
- 依動物類型
- 狗
- 貓
- 其他動物類型
- 透過使用
- 寵物跳蚤防治
- 伴侶動物蜱蟲防治
- 跳蚤過敏性皮膚炎的治療
- 其他用途
- 透過分銷管道
- 獸醫醫院和獸醫診所
- 動物用藥品
- 線上藥局和電子商務
- 其他分銷管道
- 地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他亞太國家
- 中東和非洲
- GCC
- 南非
- 其他中東和非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 市佔率分析
- 公司簡介
- Bimeda Animal Health
- Boehringer Ingelheim
- Central Garden & Pet Company
- Ceva Sante Animale
- Dechra Pharmaceuticals Limited
- Elanco Animal Health Incorporated
- Hartz Mountain Corporation
- Huvepharma EOOD
- Laboratoires Francodex
- Merck & Co., Inc.
- Norbrook Laboratories Limited
- PetIQ, Inc.
- Troy Laboratories Pty Ltd.
- Vetoquinol
- Vetoquinol SA
- Wellmark International
- Zoetis Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the fipronil market size is expected to grow from USD 2.15 billion in 2025 to USD 2.25 billion in 2026 and is forecast to reach USD 2.80 billion by 2031 at 4.53% CAGR over 2026-2031.
Global Fipronil Market Trends and Insights
Rising Companion-Animal Ownership and Preventive Care Spending
Pet ownership remains a sustained household priority, creating a recurring demand base for parasite treatments. U.S. dog ownership reached 53% of households, equivalent to 71 million households, in 2025. Cat ownership increased by 5% year over year, reaching 39% of U.S. households in 2025. Veterinary care accounted for 32.4% of pet-related household spending, with average expenditures of USD 598 among dog owners and USD 529 among cat owners in 2025. Preventive care was the primary reason for veterinary visits among 81.6% of dog owners and 76.4% of cat owners. These spending patterns support the fipronil market, particularly for products that combine over-the-counter availability with veterinary recommendations.
Increasing Flea- and Tick-Borne Disease Awareness
The expanding range of tick habitats is increasing demand for consistent flea and tick prevention. Weekly emergency department visits for tick bites reached their highest level since 2017 in April 2026. The CDC estimates that ticks bite 31 million Americans annually and that Lyme disease affects nearly 476,000 people each year. A 2025 report identified Borrelia burgdorferi in 39.6% of adult Ixodes scapularis ticks tested in western North Carolina. The 2026 CAPC forecast identified continued tick-borne disease risks across the Upper Midwest, Northeast, and Southern Appalachians. These factors support the regular monthly use of topical preventive products in the fipronil market.
Competition From Oral Isoxazoline Parasiticides
Oral isoxazolines provide veterinary clinics with a multi-parasite treatment option, offering dosing intervals of one, two, or 12 months. Elanco reported that Credelio Quattro reached USD 100 million in annual net sales by September 2025. Controlled canine and feline trials cited by the BSAVA demonstrated flea-control efficacy of 99.1% to 99.9% for isoxazoline-class products. Their dosing convenience strengthens their position in prescription settings, where ease of administration is a key purchasing consideration. However, the fipronil market maintains resilience across OTC, generic, and price-sensitive channels.
Other drivers and restraints analyzed in the detailed report include:
- Affordability of Fipronil-Based Topical Treatments
- Expansion of Veterinary E-Commerce and Subscription Replenishment
- Environmental Scrutiny of Topical Veterinary Ectoparasiticides
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Spot-on and pipette formulations are estimated to account for 51.5% of fipronil market value in 2025. These formats remain well established among dog and cat owners using monthly topical treatments. Their market position is supported by longstanding veterinary recommendations and broad retail availability. Generic spot-on products further strengthen demand by providing lower-priced alternatives. KRKA's Fyperix range highlights the availability of bioequivalent fipronil options across European retail channels. However, brand premiums face pressure as consumers can easily compare similar products.
Topical sprays are forecast to grow at a CAGR of 6.8% through 2031. Their flexibility across a broad range of animal weights and ages makes them suitable for household and kennel environments. A 2025 study reported 100% flea efficacy in cats from day 2 through day 14 for a topical fipronil combination product, followed by efficacy ranging from 92% to 97% between weeks 3 and 7. Shampoos, dips, powders, and dusts continue to address demand in price-sensitive and multi-animal settings. Pour-on products remain a smaller, livestock-focused category in authorized markets. For instance, Ceva's Fiproline Duo is a concentrated fipronil pour-on product for cattle.
Dogs are estimated to account for 58.7% of the fipronil market value in 2025. Their higher average body weight can increase the dose required per treatment, supporting higher revenue per treatment cycle. Dog owners also reported higher veterinary care expenditure than cat owners in 2025, with average spending of USD 598 and USD 529, respectively. U.S. dog ownership reached 71 million households in 2025. Together, these factors support recurring demand for canine topical parasite prevention products.
The cat segment is forecast to grow at a CAGR of 7.0% through 2031. Growth is supported by rising cat ownership and the need for species-specific treatment options. U.S. cat ownership reached 39% of households following a 5% year-over-year increase in 2025. Safety limitations associated with certain canine parasite treatments also support demand for cat-labeled fipronil products. The Istanbul study did not identify fipronil-resistance mutations in the sampled cat flea population, supporting the continued relevance of feline applications in an emerging companion-animal setting. Authorized livestock applications represent a small but stable source of demand in tropical regions with significant tick pressure.
Complete Report Scope:
- By Product Type
- Spot-On and Pipette Formulations
- Topical Sprays
- Shampoos and Dips
- Powders and Dusts
- Pour-On Formulations for Authorized Livestock Use
- By Animal Type
- Dogs
- Cats
- Other Animal Types
- By Application
- Companion-Animal Flea Control
- Companion-Animal Tick Control
- Flea Allergy Dermatitis Management
- Other Applications
- By Distribution Channel
- Veterinary Clinics and Hospitals
- Veterinary Pharmacies
- Online Pharmacies and E-Commerce
- Other Distribution Channels
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America is projected to account for 43.5% of the global fipronil market value in 2025. The region benefits from a large companion-animal population and a well-established OTC retail network. U.S. pet industry expenditure is projected to reach USD 158 billion in 2025 and USD 165 billion in 2026. Tick-bite emergency department visits are expected to reach their highest level since 2017 in April 2026, supporting demand for accessible tick-control products. The Companion Animal Parasite Council (CAPC) has identified elevated risk across the Upper Midwest, Northeast, and Southern Appalachians.
Europe is the second-largest regional market for fipronil products. Generic suppliers have influenced the competitive landscape since fipronil entered off-patent retail channels. France, Germany, and the United Kingdom support diverse OTC product portfolios offered by multiple manufacturers. The United Kingdom's regulatory review could alter the fipronil market distribution model if professional advice becomes mandatory at the point of sale. Virbac expects continued growth in companion-animal parasiticides in Western Europe during 2025 and plans to progressively introduce its 8-month parasite collar in Germany, the Netherlands, and Slovenia.
Asia-Pacific is forecast to grow at a CAGR of 5.6% through 2031, making it the fastest-growing regional market. Growth is supported by expanding pet populations in China, India, South Korea, and Southeast Asia. China's tier-1 cities and India's metropolitan veterinary corridors are key centers for premium pet healthcare. Southeast Asia remains at an earlier stage of market development, where accessible pricing can support the adoption of routine treatment practices. Virbac projects companion-animal growth of 9% in China and 6.5% in Japan at constant exchange rates during the first quarter of 2025. South America and the Middle East and Africa remain early-stage markets, where large untreated pet populations present significant opportunities for basic parasite-control products.
- Bimeda Animal Health
- Boehringer Ingelheim
- Central Garden & Pet Company
- Ceva Sante Animale
- Dechra Pharmaceuticals Limited
- Elanco
- Hartz Mountain Corporation
- Huvepharma EOOD
- Laboratoires Expanscience
- Merck
- Norbrook Laboratories Limited
- PetIQ, Inc.
- Troy Laboratories Pty Ltd.
- Vetoquinol
- Vetoquinol
- Wellmark International
- Zoetis
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Companion-Animal Ownership and Preventive Care Spending
- 4.2.2 Increasing Flea- and Tick-Borne Disease Awareness
- 4.2.3 Affordability of Fipronil-Based Topical Treatments
- 4.2.4 Expansion of Veterinary E-Commerce and Subscription Replenishment
- 4.2.5 One Health Demand for Reducing Parasite Transmission Between Animals and Humans
- 4.3 Market Restraints
- 4.3.1 Competition From Oral Isoxazoline Parasiticides
- 4.3.2 Environmental Scrutiny of Topical Veterinary Ectoparasiticides
- 4.3.3 Flea Resistance and Declining Treatment Confidence
- 4.3.4 Product Misuse, Counterfeiting and Cross-Species Safety Risks
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat Of New Entrants
- 4.6.2 Bargaining Power Of Buyers
- 4.6.3 Bargaining Power Of Suppliers
- 4.6.4 Threat Of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Spot-On and Pipette Formulations
- 5.1.2 Topical Sprays
- 5.1.3 Shampoos and Dips
- 5.1.4 Powders and Dusts
- 5.1.5 Pour-On Formulations for Authorized Livestock Use
- 5.2 By Animal Type
- 5.2.1 Dogs
- 5.2.2 Cats
- 5.2.3 Other Animal Types
- 5.3 By Application
- 5.3.1 Companion-Animal Flea Control
- 5.3.2 Companion-Animal Tick Control
- 5.3.3 Flea Allergy Dermatitis Management
- 5.3.4 Other Applications
- 5.4 By Distribution Channel
- 5.4.1 Veterinary Clinics and Hospitals
- 5.4.2 Veterinary Pharmacies
- 5.4.3 Online Pharmacies and E-Commerce
- 5.4.4 Other Distribution Channels
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)}
- 6.3.1 Bimeda Animal Health
- 6.3.2 Boehringer Ingelheim
- 6.3.3 Central Garden & Pet Company
- 6.3.4 Ceva Sante Animale
- 6.3.5 Dechra Pharmaceuticals Limited
- 6.3.6 Elanco Animal Health Incorporated
- 6.3.7 Hartz Mountain Corporation
- 6.3.8 Huvepharma EOOD
- 6.3.9 Laboratoires Francodex
- 6.3.10 Merck & Co., Inc.
- 6.3.11 Norbrook Laboratories Limited
- 6.3.12 PetIQ, Inc.
- 6.3.13 Troy Laboratories Pty Ltd.
- 6.3.14 Vetoquinol
- 6.3.15 Vetoquinol S.A.
- 6.3.16 Wellmark International
- 6.3.17 Zoetis Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 Fipronil吡唑市場:全球市場預測,2026-2032年
 壬二酸市場:依產品等級、應用、最終用戶及地區分類
 全球草銨膦市場:機會與策略展望(至2035年)草銨膦市場:2026-2032 年全球市場預測
 壬酸市場規模、佔有率和成長分析:按產品等級、純度、應用、終端用戶產業和地區分類-2026-2033年產業預測
 草銨膦市場規模、佔有率和成長分析:按製劑、作物類型、應用、加工階段、分銷通路和地區分類-2026-2033年產業預測
 草銨膦:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 草銨膦市場報告:按作物類型、製劑類型、應用和地區分類(2026-2034 年)Fipronil市場:2026-2032年全球市場預測(依作物類型、製劑類型、劑型、最終用途、應用方法及通路分類)
 Fipronil市場 - 全球產業規模、佔有率、趨勢、機會、預測:按形態、應用、區域和競爭格局分類,2021-2031年