


 |
市場調查報告書
商品編碼
2154511
南美洲連續油管市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)South America Coiled Tubing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
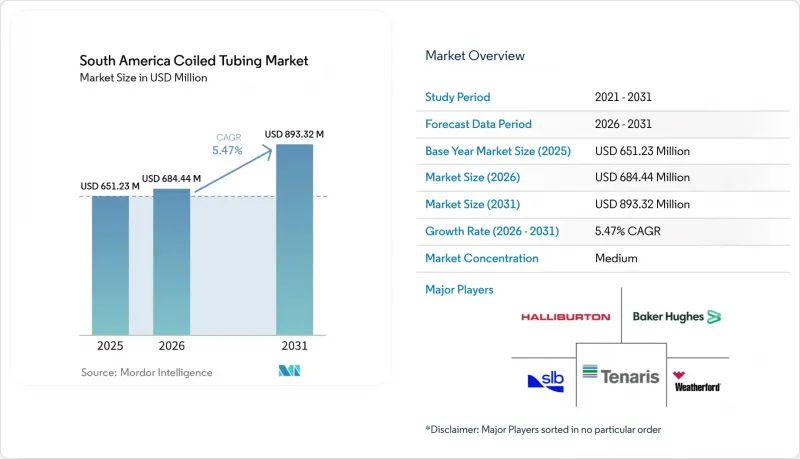
根據 Mordor Intelligence 預測,南美撓曲油管市場預計將從 2025 年的 6.5123 億美元成長到 2026 年的 6.8444 億美元,到 2031 年達到 8.9332 億美元,2026 年至 2031 年的複合年成長率預計為 5.47%。
南美洲撓曲油管市場趨勢與洞察
擴大巴西鹽鹽層下油氣生產和圭亞那深海油氣生產
隨著巴西鹽層下下層油氣產量的增加,需要進行完井、清理和生產支援的油井數量也在增加。巴西2025年的油氣日產量達490萬桶油當量,其中鹽鹽層下產量佔國內生產總值的79.6%。巴西石油公司(Petrobras)計劃在2026年至2030年間向上游領域投資1,200億美元,預計到2030年,鹽鹽層下產量將佔其總產量的82%。每口新的海底油井都需要進行完井作業,隨著生產條件的變化,後續可能還需要介入。在圭亞那,埃克森美孚公司於2025年9月最終決定投資68億美元的「錘頭)計畫。這是該公司在斯塔布布魯克油田的第七個開發項目,預計到 2029 年將運作一座日產能 15 萬桶的生產設施。 FPSO 計畫的增加為能夠在當地調動設備和人員的服務供應商帶來了機會。
瓦卡穆爾塔油井開發與修復工作
在瓦卡穆爾塔(Vaca Muerta),南美陸上撓曲油管市場的需求基礎正隨著多井平台開發和重完井作業的發展而不斷擴大。撓曲油管用於壓裂作業間隙的封堵鑽井,也可用於水平井重入和側鑽作業。隨著作業者從初始評估工作轉向可重複的平台開發,這些作業的頻率也隨之增加。這種需求模式與巴西有所不同,其重點在於大規模宣傳活動,而非深海船舶作業。雖然哈里伯頓公司與YPF公司簽訂的多年獨家合約「宙斯」(Zeus)涵蓋了傳統型完井作業,但平台開發活動的廣泛擴展也帶動了合約範圍之外的干預作業和重完井作業。這為能夠在內烏肯盆地(Neuquén Basin)提供可靠的油管組件、井下工具和現場作業人員的服務供應商創造了市場空間,以支援可重複的作業。
高昂的動員成本和專業人員成本
深水撓曲油管作業需要壓力控制設備、專用船舶、具備高壓作業資格的人員。這些要求增加了將設備運送到巴西鹽層下油田或進口到圭亞那的成本。在本地服務資源有限的地區,這種成本障礙尤為突出。 ANP安全要求要求作業者記錄海上油井作業中壓力屏障的完整性,這增加了乾預計畫中的合規性工作。成熟的供應商具有優勢,因為他們可以將設備、培訓和合規成本分攤到多個合約中。即使海上需求不斷成長,這也可能減緩小規模供應商進入市場的速度。
細分市場分析
2025年,油井干預作業佔南美洲撓曲油管市場佔有率的63.2%。這一領域受益於巴西成熟的海上油氣資產以及坎波斯盆地持續不斷的油井干預作業量。作業者使用撓曲油管進行清井、壓力管理、增產處理和其他生產支援作業。哈里伯頓公司與巴西石油公司簽訂的合約涵蓋海上油井干預和封鎖增產作業,其中包括撓曲油管服務。貝克休斯公司在馬卡埃也設有專門用於海上修井和封鎖增產項目的設施。這些合約為整個專案週期提供了穩定的油井干預收入來源。
鑽井是成長最快的服務類別,預計2026年至2031年南美洲撓曲油管市場規模將以6.7%的複合年成長率成長。撓曲油管支援水平井重入和側鑽作業,尤其是在瓦卡穆埃爾塔油田。此領域與延長井場井生產壽命和開採剩餘儲存段的需求密切相關。隨著巴西和圭亞那連接到FPSO的海底開發井數量的增加,完井作業也在增加。其他服務,包括氮舉和基質增產,規模仍然較小,但有助於提高成熟井的產能。聖卡塔琳娜州立大學2025年的研究考察了使用撓曲油管進行氮氣增產,並證明了該方法在巴西油井中的技術有效性。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大巴西鹽鹽層下油氣生產和圭亞那深海油氣生產
- 瓦卡穆爾塔的油井開發與修復工作
- 透過「老化油井」最佳化生產並延長使用壽命
- 對倒退性干預措施的需求將導致海上作業中非生產性時間的減少。
- 即時地下診斷和自動化盤管
- 綜合維修及即插即用工程
- 市場限制因素
- 高昂的動員成本和專業人員成本
- 有線、液壓和其他替代性競賽
- 疲勞、腐蝕和酸性環境下的認證限值
- 在地採購、授權和跨境物流的摩擦。
- 供應鏈分析
- 波特五力分析
- 科技趨勢
- 監理情勢
- 投資分析
第5章 市場規模與成長預測
- 按服務類型
- 地下工程
- 挖掘
- 完井
- 其他服務
- 按部署位置
- 陸上
- 離岸
- 按地區
- 巴西
- 阿根廷
- 蓋亞那
- 哥倫比亞
- 智利
- 其他南美國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Aker Solutions ASA
- Altus Intervention
- Archer Limited
- Baker Hughes Company
- C&J Well Services
- Calfrac Well Services Ltd.
- Halliburton Company
- Helix Energy Solutions Group, Inc.
- Jereh Group
- Key Energy Services, LLC
- Nabors Industries Ltd.
- National Oilwell Varco(NOV)Inc.
- Oceaneering International, Inc.
- Royal IHC
- SLB(Schlumberger Limited)
- STEP Energy Services Ltd.
- Superior Energy Services, Inc.
- Tenaris SA
- Trican Well Service Ltd.
- Weatherford International plc
第7章 市場機會與未來展望
According to Mordor Intelligence, the South America coiled tubing market size is expected to increase from USD 651.23 million in 2025 to USD 684.44 million in 2026 and reach USD 893.32 million by 2031, at a CAGR of 5.47% over 2026-2031.
South America Coiled Tubing Market Trends and Insights
Expansion of Brazil Pre-Salt and Guyana Deepwater Production
Brazil's pre-salt output expansion increases the number of wells that need completion, cleanout, and production support. Brazil recorded 4.9 million boe/d of oil and gas output in 2025, while pre-salt production represented 79.6% of the country total. Petrobras plans USD 120 billion of upstream investment for 2026 through 2030, with pre-salt production expected to represent up to 82% of its output by 2030. Each new subsea well requires work during completion and may require later intervention as production conditions change. In Guyana, ExxonMobil made a final investment decision in September 2025 on the USD 6.8 billion Hammerhead project, its seventh Stabroek development, with a 150,000 bopd facility expected in 2029. The growing number of FPSO projects creates an opportunity for service providers that can mobilize equipment and personnel locally.
Vaca Muerta Well Development and Recompletion Activity
Vaca Muerta is widening the onshore demand base for the South America coiled tubing market through multi-well pad development and recompletion work. Coiled tubing is used for plug drill-outs between fracturing stages and can support lateral re-entries and sidetracks. These activities become more frequent when operators move from early appraisal work to repeatable pad development. The demand pattern differs from Brazil because it centers on high-volume campaigns rather than deepwater vessel-based work. Halliburton's exclusive multi-year Zeus completions contract with YPF covers unconventional completions, but the broader expansion of pad activity also supports intervention and recompletion work outside the contract scope. This leaves room for providers that can supply reliable strings, downhole tools, and field crews for repeated operations in the Neuquen Basin.
High Mobilization and Specialized Personnel Costs
Deepwater coiled tubing work requires pressure-control equipment, specialized vessels, and personnel qualified for high-pressure operations. These requirements raise the cost of sending equipment to Brazil's pre-salt fields or importing it into Guyana. The cost barrier is particularly relevant where local service bases are limited. ANP safety requirements require operators to document pressure-barrier integrity for offshore well work, which adds compliance work to intervention planning. Established providers have an advantage because they can spread equipment, training, and compliance costs across several contracts. This can slow entry by smaller providers even when offshore demand is expanding.
Other drivers and restraints analyzed in the detailed report include:
- Aging-Well Production Optimization and Life Extension
- Rigless Intervention Demand to Reduce Offshore Nonproductive Time
- Wireline, Hydraulic Workover, and Other Substitute Competition
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Well intervention accounted for 63.2% of the South America coiled tubing market share in 2025. The segment benefits from Brazil's mature offshore assets and the continuing intervention workload in the Campos Basin. Operators use coiled tubing for cleanouts, pressure-management work, stimulation, and other production support tasks. Halliburton's Petrobras contract covers offshore intervention and plug-and-abandonment activity, including coiled tubing services. Baker Hughes has also committed dedicated capacity at Macae for its offshore workover and plug-and-abandonment program. These contracts provide a stable base for well intervention revenue through the active terms of the programs.
Drilling is the fastest-growing service type and the South America coiled tubing market size for this segment is forecast to grow at a 6.7% CAGR from 2026 to 2031. Coiled tubing drilling supports lateral re-entries and sidetrack operations, particularly in Vaca Muerta. The segment is linked to a growing need to extend the productive life of pad wells and access remaining reservoir sections. Well completion activity also rises as Brazil and Guyana add subsea development wells connected to FPSOs. Other services, including nitrogen lifting and matrix stimulation, remain smaller but support production improvement in mature wells. A 2025 study from Universidade do Estado de Santa Catarina examined nitrogen use through coiled tubing for production induction, illustrating the technical relevance of this approach for Brazilian wells.
Complete Report Scope:
- By Service Type
- Well Intervention
- Drilling
- Well Completion
- Other Services
- By Location of Deployment
- Onshore
- Offshore
- By Geography
- Brazil
- Argentina
- Guyana
- Colombia
- Chile
- Rest of South America
List of Companies Covered in this Report:
- Aker Solutions ASA
- Altus Intervention
- Archer Limited
- Baker Hughes Company
- C&J Well Services
- Calfrac Well Services Ltd.
- Halliburton Company
- Helix Energy Solutions Group, Inc.
- Jereh Group
- Key Energy Services, LLC
- Nabors Industries Ltd.
- National Oilwell Varco (NOV) Inc.
- Oceaneering International, Inc.
- Royal IHC
- SLB (Schlumberger Limited)
- STEP Energy Services Ltd.
- Superior Energy Services, Inc.
- Tenaris S.A.
- Trican Well Service Ltd.
- Weatherford International plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Brazil Pre-Salt and Guyana Deepwater Production
- 4.2.2 Vaca Muerta Well Development and Recompletion Activity
- 4.2.3 Aging-Well Production Optimization and Life Extension
- 4.2.4 Rigless Intervention Demand to Reduce Offshore Nonproductive Time
- 4.2.5 Real-Time Downhole Diagnostics and Automated Coiled Tubing
- 4.2.6 Integrated Workover and Plug-and-Abandonment Campaigns
- 4.3 Market Restraints
- 4.3.1 High Mobilization and Specialized Personnel Costs
- 4.3.2 Wireline, Hydraulic Workover, and Other Substitute Competition
- 4.3.3 Fatigue, Corrosion, and Sour-Service Qualification Limits
- 4.3.4 Local-Content, Permitting, and Cross-Border Logistics Friction
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Service Type
- 5.1.1 Well Intervention
- 5.1.2 Drilling
- 5.1.3 Well Completion
- 5.1.4 Other Services
- 5.2 By Location of Deployment
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Geography
- 5.3.1 Brazil
- 5.3.2 Argentina
- 5.3.3 Guyana
- 5.3.4 Colombia
- 5.3.5 Chile
- 5.3.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Aker Solutions ASA
- 6.4.2 Altus Intervention
- 6.4.3 Archer Limited
- 6.4.4 Baker Hughes Company
- 6.4.5 C&J Well Services
- 6.4.6 Calfrac Well Services Ltd.
- 6.4.7 Halliburton Company
- 6.4.8 Helix Energy Solutions Group, Inc.
- 6.4.9 Jereh Group
- 6.4.10 Key Energy Services, LLC
- 6.4.11 Nabors Industries Ltd.
- 6.4.12 National Oilwell Varco (NOV) Inc.
- 6.4.13 Oceaneering International, Inc.
- 6.4.14 Royal IHC
- 6.4.15 SLB (Schlumberger Limited)
- 6.4.16 STEP Energy Services Ltd.
- 6.4.17 Superior Energy Services, Inc.
- 6.4.18 Tenaris S.A.
- 6.4.19 Trican Well Service Ltd.
- 6.4.20 Weatherford International plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 撓曲油管市場:類型、服務類型、材質、應用與最終用途-2026-2032年全球市場預測
 2026年全球盤管市場報告
 撓曲油管市場規模、佔有率和趨勢分析報告:按服務、營運、應用、地區和細分市場預測(2026-2033 年)
 連續油管市場-全球產業規模、佔有率、趨勢、機會、預測:按服務類型、應用、地區和競爭格局分類,2021-2031年
 全球撓曲油管服務市場:市場規模、佔有率、成長率、產業分析、依類型、應用和地區劃分的考察、未來預測(2026-2034)
 連續油管鑽井服務市場機會、成長促進因素、產業趨勢分析及預測(2025-2034年)
 歐洲撓曲油管:市場佔有率分析、產業趨勢、成長預測(2025-2030)連續油管市場機會、成長動力、產業趨勢分析及 2025 - 2034 年預測