


 |
市場調查報告書
商品編碼
2125726
天花板照明及水晶燈:市場佔有率分析、產業趨勢及統計數據、成長預測(2026-2031)Ceiling Lights & Chandeliers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
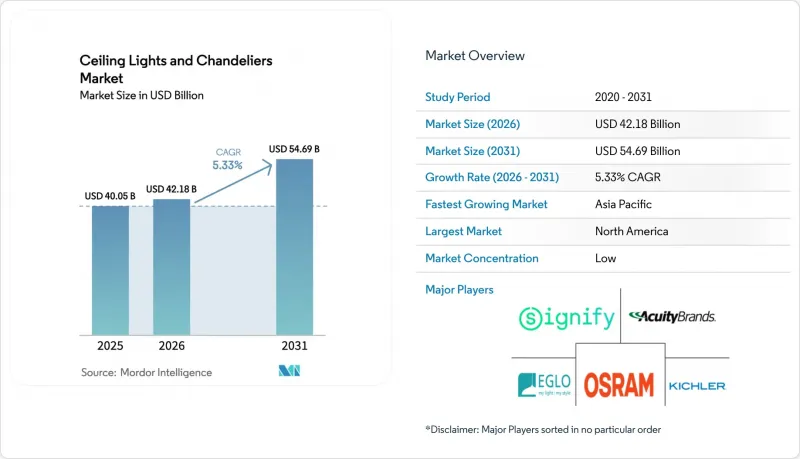
據 Mordor Intelligence 稱,2025 年天花板照明和水晶燈市場價值為 400.5 億美元,預計到 2031 年將達到 546.9 億美元,而 2026 年為 421.8 億美元,預測期(2026-2031 年)的複合年成長率為 5.33%。
本報告按產品類型(吸頂燈、水晶燈)、照明技術(LED、螢光、其他)、材料(金屬、水晶、其他)、最終用戶(住宅、商業)、分銷管道(線下展示室/專賣店、DIY/家居連鎖店、其他)和地區(北美、歐洲、其他)進行細分。市場預測以美元計價。
全球天花板照明和水晶燈市場的趨勢和洞察。
人們對家居美學和室內設計的需求日益成長。
照明正從純粹的功能性產品演變為彰顯空間特色的設計元素,越來越多的住宅選擇用兼具視覺美感和節能效果的高階燈具來取代普通燈具。住宅照明仍約佔家庭電力消耗量的10%,而「能源之星」(ENERGY STAR)認證的燈具型號已超過6萬種,這些燈具兼具設計感和低能耗。由於美國人近90%的時間都待在室內,改善室內視覺環境始終名列住宅維修計畫前五名。到2024年,美國將有約370萬戶家庭升級照明系統,凸顯了市場對照明設備的持續需求。
都市化和住宅建設增加
亞太、中東和拉丁美洲的快速城市化正在推動對新型吸頂燈的需求。聯合國數據顯示,2024年,全球56.2%的人口將居住在都市區,預計2050年將達到68.4%。屆時,全球將需要新建約25億套住宅,每套房屋都需要安裝多個照明設備。在美國,預計2024年私人住宅開工量將達到156萬套,年增7.2%,這將直接促進照明設備的銷售。
高級設計師燈具價格昂貴
豪華水晶燈的價格可能是普通嵌入式照明的數倍,這限制了它們在價格敏感型消費群體中的普及。家庭在耐用品上的支出在超過一定閾值後彈性很大,但自2024年以來,關稅已使進口零件的成本增加了高達25%。美國高所得家庭在住宅上的支出是中等收入家庭的4.7倍,這清楚地表明了收入不平等限制了可覆蓋的銷售量。
細分市場分析
預計到2025年,吸頂燈將佔總銷售額的62.20%,並繼續成為客廳、廚房、走廊和商業空間的標準選擇。美國家庭平均擁有12.3盞燈具,其中三分之二是吸頂燈。雖然嵌入式和表面安裝燈具的出貨量最大,但吊燈的成長速度更快,反映出消費者對獨特美學的需求日益成長。水晶燈雖然市佔率較小,但預計其複合年成長率將達到6.12%,這主要得益於餐廳和飯店大廳安裝量的增加。 2024年,裝飾照明燈具的進口量增加了18.3%,這顯示即使傳統燈具市場日趨成熟,消費者對獨特設計的需求依然強勁。
隨著設計理念與智慧家庭功能的融合,天花板照明和水晶燈市場正受到連鎖反應的影響。領先的水晶燈製造商正嘗試將以往僅限於功能性照明燈具的特性融入其中,例如藍牙網狀網路驅動器和可調光白光LED。預計到2024年,美國新建獨棟住宅中至少安裝一盞水晶燈的比例將達到68%,比2020年增加12個百分點。這些變化預示著未來裝飾形式與智慧互聯將並存,從而拓展消費者的選擇範圍並推高平均售價。
預計2025年,LED燈將佔總銷售量的53.51%,到2030年市場滲透率將超過80%,取代現有的螢光和鹵素燈等照明設備。與白熾燈相比,LED燈的效率提升近90%,對於住宅和物業管理人員而言,這無疑是一項極具吸引力的投資。尤其值得一提的是,智慧LED燈和連網LED燈的中期複合年成長率預計將達到10.95%,這將進一步鞏固吸頂燈和水晶燈市場作為物聯網(IoT)入口網站的地位。聯網驅動器、內建感測器和韌體升級正在將照明設備轉變為用於人員佔用分析和資產管理的資料點。
雖然螢光在某些商業和公共設施中仍然佔有一席之地,但隨著 LED 提供有吸引力的投資回報率 (ROI),其市場佔有率持續下降,投資回收期通常不到兩年。
區域分析
預計到2025年,北美將佔據34.50%的市場佔有率,繼續保持其在吸頂燈和水晶燈銷售領域最大的市場佔有率地位。 2024年,美國家庭在住宅維修上花費了4,570億美元,其中照明昇級是一項主要收益。全美已安裝約21億盞吸頂燈,年更換率約8.3%。加拿大優先考慮能源效率的政策正在推動LED市場佔有率超過美國。在墨西哥,隨著出口商將業務拓展到亞洲以外的地區,預計2024年國內工廠的照明產品產量將成長12.7%。
亞太地區是成長最快的地區,預計到2031年將以8.78%的複合年成長率成長。在中國,2020年至2024年間都市區人口增加了1.06億,擴大了對住宅照明設備的需求。在印度,到2030年需要新建2500萬套住宅,照明成本通常佔建築預算的2.7%。在日本,由於翻新週期加快,國內LED產量預計到2024年將成長15.3%。在韓國,受嚴格的能源法規推動,預計到2024年LED普及率將達到78%。新加坡的「綠色建築標誌」計畫正在東南亞地區推廣高效節能照明設備。
歐洲憑藉其設計傳統和嚴格的法規,仍然保持著舉足輕重的影響力。生態設計指令將於2024年前逐步淘汰大部分鹵素燈,銷售將轉向高效節能的LED燈。根據歐盟統計局的數據,每個家庭每年在照明和電力上的支出為213歐元(約187.21美元),而不同地區日照時間的差異造成了各地支出水準的差異。在英國,照明用電量佔商業用電量的18%,推動了維修工程的成長。在德國,隨著供應商轉向高級產品線,預計2024年照明產品產量將成長3.7%。在法國,嚴格的光污染法規正在推動對光通量控制光學元件的需求。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人們對家居美學和室內設計的需求日益成長。
- 都市化和住宅建設增加
- 科技進步(智慧照明、節能照明)
- 酒店和商業房地產行業的成長
- 電子商務和線上零售通路的擴張
- 市場限制因素
- 高級設計師燈具價格昂貴
- 能源法規和合規標準
- 安裝複雜性和維護挑戰
- 原物料價格波動(玻璃、水晶、金屬)
- 價值供應鏈分析
- 監理展望
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 天花板照明
- 閃光燈/表面貼裝
- 半閃光
- 嵌入式下照燈
- 吊燈/垂吊燈
- 水晶燈
- 傳統的
- 過渡
- 現代當代
- 天花板照明
- 透過照明技術
- LED
- 螢光
- 白熾燈和鹵素燈
- HID 和其他
- 材料
- 金屬
- 水晶
- 玻璃
- 木材/天然材料
- 塑膠和複合材料
- 最終用戶
- 住宅
- 商業的
- 辦公室和共享辦公空間
- 飯店餐飲業(飯店、度假村、餐廳)
- 零售和購物中心
- 醫療機構
- 教育機構
- 產業
- 透過分銷管道
- 線下展示室及專賣店
- DIY居家中心連鎖
- 線上電子商務平台
- 按地區
- 北美洲
- 加拿大
- 美國
- 墨西哥
- 南美洲
- 巴西
- 秘魯
- 智利
- 阿根廷
- 其他南美國家
- 亞太地區
- 印度
- 中國
- 日本
- 澳洲
- 韓國
- 東南亞(新加坡、馬來西亞、泰國、印尼、越南、菲律賓)
- 其他亞太國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 比荷盧經濟聯盟(比利時、荷蘭、盧森堡)
- 北歐國家(丹麥、芬蘭、冰島、挪威、瑞典)
- 其他歐洲國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 奈及利亞
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介{包括全球概覽、市場概覽、關鍵細分市場、現有財務資訊、策略資訊、主要公司市場排名/佔有率、產品和服務以及近期發展動態}
- Signify(Philips Lighting)
- OSRAM GmbH
- Eglo Leuchten GmbH
- Kichler Lighting LLC
- Hubbell Lighting Inc.
- Generation Brands(Visual Comfort & Co.)
- Zumtobel Group
- FLOS SpA
- Hudson Valley Lighting Group
- Artemide SpA
- Feilo Sylvania
- Panasonic Life Solutions
- Cree Lighting
- Lutron Electronics
- Hinkley Lighting
- Savoy House
- Schonbek Worldwide Lighting
- Currey & Company
- Foscarini*
第7章 市場機會與未來展望
According to Mordor Intelligence, the ceiling lights & chandeliers market size was valued at USD 40.05 billion in 2025 and estimated to grow from USD 42.18 billion in 2026 to reach USD 54.69 billion by 2031, at a CAGR of 5.33% during the forecast period (2026-2031).
This report Segments Into Product Type (Ceiling Lights, Chandeliers), Lighting Technology (LED, Fluorescent, and More), Material (Metal, Crystal and More), End-User (Residential, Commercial), Distribution Channel (Offline/Showrooms and Specialty Stores, DIY and Home-Improvement Chains and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Ceiling Lights & Chandeliers Market Trends and Insights
Rising home aesthetics and interior design
Lighting has shifted from a purely functional commodity to a defining design element, encouraging homeowners to replace basic fixtures with statement pieces that deliver both ambience and efficiency. Residential lighting still consumes roughly 10% of household electricity, and ENERGY STAR now lists more than 60,000 certified models that blend design and low wattage . Americans spend close to 90% of their time indoors, so improved visual environments consistently rank among the top five home improvement projects. Around 3.7 million United States households upgraded lighting in 2024, underlining steady replacement demand.
Urbanization and Rising Residential Construction
Rapid city growth across Asia-Pacific, the Middle East, and Latin America fuels new-build demand for ceiling-mounted illumination. United Nations data shows 56.2% of the global population lived in urban areas in 2024, with the share tracking toward 68.4% by 2050. Countries will need roughly 2.5 billion new housing units, each requiring multiple fixtures. In the United States, privately owned housing starts hit an annualized 1.56 million in 2024, a 7.2% rise that directly lifts fixture sales.
High Cost of Premium and Fixtures Designer
Statement chandeliers can cost several multiples of standard flush mounts, limiting penetration in price-sensitive segments. Household spending on durable goods is highly elastic above certain thresholds, and tariffs have lifted landed costs for imported components by up to 25% since 2024. Top-income United States households spend 4.7 times more on home furnishings than middle-income peers, illustrating the income asymmetry that caps addressable volume.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advances in Smart and Energy-Efficient Lighting
- Growth in Hospitality and Commercial Real Estate Sectors
- Energy Regulations and Compliance Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ceiling lights represented 62.20% of 2025 revenue and remain the default choice across living rooms, kitchens, corridors, and commercial settings. Average United States homes host 12.3 fixtures, two-thirds of which are ceiling mounted . Flush and surface mounts ship in the highest volumes, but pendants show faster growth, reflecting consumer interest in bespoke aesthetics. Chandeliers occupy a smaller slice yet are projected to post a 6.12% CAGR, bolstered by rising installations in dining rooms and hotel lobbies. Imports of decorative fixtures climbed 18.3% in 2024, confirming a resilient appetite for standout designs even when traditional categories mature.
Second-order effects ripple through the ceiling lights & chandeliers market as design expectations converge with smart-home functionality. Leading chandelier makers now experiment with embedded Bluetooth-mesh drivers and tunable-white LEDs, features previously reserved for utilitarian luminaires. New United States single-family builds featuring at least one chandelier rose to 68% in 2024, up 12 points from 2020. These shifts foreshadow a future where decorative form and networked intelligence coexist, widening consumer choice and nudging average selling prices higher.
LED captured 53.51% of sales in 2025 and is on track to exceed 80% penetration by 2030, displacing fluorescent and halogen incumbents. Efficacy gains of nearly 90% over incandescent lamps deliver compelling paybacks for both homeowners and facility managers. Crucially, smart or connected LEDs register an 10.95% medium-term CAGR, reinforcing the ceiling lights & chandeliers market as an IoT on-ramp. Network-ready drivers, integrated sensors, and firmware upgrades transform fixtures into data points for occupancy analytics and asset management.
Fluorescent lighting maintains a presence in certain commercial and institutional applications, though its market share continues to decline as LED retrofits offer compelling returns on investment with payback periods typically under two years.
Complete Report Scope:
- By Product Type
- Ceiling Lights
- Flush/Surface Mount
- Semi-Flush
- Recessed Downlights
- Pendant & Drop Lights
- Chandeliers
- Traditional
- Transitional
- Modern / Contemporary
- Ceiling Lights
- By Lighting Technology
- LED
- Fluorescent
- Incandescent & Halogen
- HID & Others
- By Material
- Metal
- Crystal
- Glass
- Wood & Natural Materials
- Plastics & Composites
- By End-user
- Residential
- Commercial
- Offices and Co-Working Spaces
- Hospitality (Hotels, Resorts, Restaurants)
- Retail & Shopping Malls
- Healthcare Facilities
- Educational Institutions
- Industrial
- By Distribution Channel
- Offline/Showrooms & Specialty Stores
- DIY and Home-Improvement Chains
- Online/E-commerce Platforms
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East And Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
North America retains the greatest chunk of the ceiling lights & chandeliers market revenue with 34.50% of market share in 2025. United States households spent USD 457 billion on improvements in 2024, with lighting upgrades a large beneficiary . Around 2.1 billion ceiling fixtures are installed nationally, and replacement rates sit near 8.3% each year. Canadian policy leans heavily on energy performance, advancing LED share beyond United States levels. Mexico's domestic factories saw lighting output rise 12.7% in 2024 as exporters diversified away from Asia.
Asia-Pacific is the fastest-growing territory, set for 8.78% CAGR to 2031. China added 106 million new urban residents between 2020-2024, swelling demand for residential fixtures. India needs 25 million additional homes by 2030, and lighting typically equals 2.7% of construction budgets. Japan's domestic LED output climbed 15.3% in 2024 as renovation cycles accelerated. Korea reached 78% LED penetration in 2024 on the back of stringent energy codes. Singapore's Green Mark program pushes Southeast Asian developers toward efficient luminaires.
Europe remains influential owing to its design heritage and tight regulation. The Ecodesign Directive fully phased out most halogen lamps by 2024, focusing sales on high-efficacy LEDs. Eurostat shows households spend EUR 213 (USD 187.21) yearly on lighting products and power, with daylight variability shaping regional differences. The UK cites lighting as 18% of commercial electricity load, spurring retrofit projects. Germany's fixture manufacturing rose 3.7% in 2024 as suppliers pivoted to premium lines. France's strict light-pollution rules strengthen demand for controlled-beam optics.
- Signify (Philips Lighting)
- OSRAM GmbH
- Eglo Leuchten GmbH
- Kichler Lighting LLC
- Hubbell Lighting Inc.
- Generation Brands (Visual Comfort & Co.)
- Zumtobel Group
- FLOS S.p.A.
- Hudson Valley Lighting Group
- Artemide S.p.A.
- Feilo Sylvania
- Panasonic Life Solutions
- Cree Lighting
- Lutron Electronics
- Hinkley Lighting
- Savoy House
- Schonbek Worldwide Lighting
- Currey & Company
- Foscarini*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for Home Aesthetics & Interior Design
- 4.2.2 Urbanization and Rising Residential Construction
- 4.2.3 Technological Advancements (Smart & Energy-Efficient Lighting)
- 4.2.4 Growth in Hospitality and Commercial Real Estate Sectors
- 4.2.5 Expanding E-Commerce and Online Retail Channels
- 4.3 Market Restraints
- 4.3.1 High Cost of Premium and Designer Fixtures
- 4.3.2 Energy Regulations and Compliance Standards
- 4.3.3 Installation Complexity and Maintenance Issues
- 4.3.4 Volatility in Raw Material Prices (Glass, Crystal, Metal)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power Suppliers
- 4.7.2 Bargaining Power Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Ceiling Lights
- 5.1.1.1 Flush/Surface Mount
- 5.1.1.2 Semi-Flush
- 5.1.1.3 Recessed Downlights
- 5.1.1.4 Pendant & Drop Lights
- 5.1.2 Chandeliers
- 5.1.2.1 Traditional
- 5.1.2.2 Transitional
- 5.1.2.3 Modern / Contemporary
- 5.1.1 Ceiling Lights
- 5.2 By Lighting Technology
- 5.2.1 LED
- 5.2.2 Fluorescent
- 5.2.3 Incandescent & Halogen
- 5.2.4 HID & Others
- 5.3 By Material
- 5.3.1 Metal
- 5.3.2 Crystal
- 5.3.3 Glass
- 5.3.4 Wood & Natural Materials
- 5.3.5 Plastics & Composites
- 5.4 By End-user
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.2.1 Offices and Co-Working Spaces
- 5.4.2.2 Hospitality (Hotels, Resorts, Restaurants)
- 5.4.2.3 Retail & Shopping Malls
- 5.4.2.4 Healthcare Facilities
- 5.4.2.5 Educational Institutions
- 5.4.3 Industrial
- 5.5 By Distribution Channel
- 5.5.1 Offline/Showrooms & Specialty Stores
- 5.5.2 DIY and Home-Improvement Chains
- 5.5.3 Online/E-commerce Platforms
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 Canada
- 5.6.1.2 United States
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Peru
- 5.6.2.3 Chile
- 5.6.2.4 Argentina
- 5.6.2.5 Rest of South America
- 5.6.3 Asia-Pacific
- 5.6.3.1 India
- 5.6.3.2 China
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.6.3.7 Rest of Asia Pacific
- 5.6.4 Europe
- 5.6.4.1 United Kingdom
- 5.6.4.2 Germany
- 5.6.4.3 France
- 5.6.4.4 Spain
- 5.6.4.5 Italy
- 5.6.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.6.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.6.4.8 Rest of Europe
- 5.6.5 Middle East And Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Nigeria
- 5.6.5.5 Rest of Middle East And Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments}
- 6.4.1 Signify (Philips Lighting)
- 6.4.2 OSRAM GmbH
- 6.4.3 Eglo Leuchten GmbH
- 6.4.4 Kichler Lighting LLC
- 6.4.5 Hubbell Lighting Inc.
- 6.4.6 Generation Brands (Visual Comfort & Co.)
- 6.4.7 Zumtobel Group
- 6.4.8 FLOS S.p.A.
- 6.4.9 Hudson Valley Lighting Group
- 6.4.10 Artemide S.p.A.
- 6.4.11 Feilo Sylvania
- 6.4.12 Panasonic Life Solutions
- 6.4.13 Cree Lighting
- 6.4.14 Lutron Electronics
- 6.4.15 Hinkley Lighting
- 6.4.16 Savoy House
- 6.4.17 Schonbek Worldwide Lighting
- 6.4.18 Currey & Company
- 6.4.19 Foscarini*
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 燈具照明:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 障礙指示燈市場:全球市場預測,2026-2032年
 全球燈具照明市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 垂直農業照明系統市場:預測至2034年-按光源、頻譜、安裝、應用和區域分類的全球分析
 2026-2030年全球照明市場印度照明市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)全球通用照明市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 燈具照明市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 垂直農業照明市場規模、佔有率和趨勢分析報告:按組件、照明類型、農場類型、安裝類型、作物類型、最終用途、地區和細分市場預測(2026-2033 年)
 基礎設施照明市場-全球產業規模、佔有率、趨勢、機會和預測:按技術、產品、應用、地區和競爭格局分類,2021-2031年