


 |
市場調查報告書
商品編碼
2125486
印度乾餾液牧場:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)India Dried Distillers Grain With Solubles - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
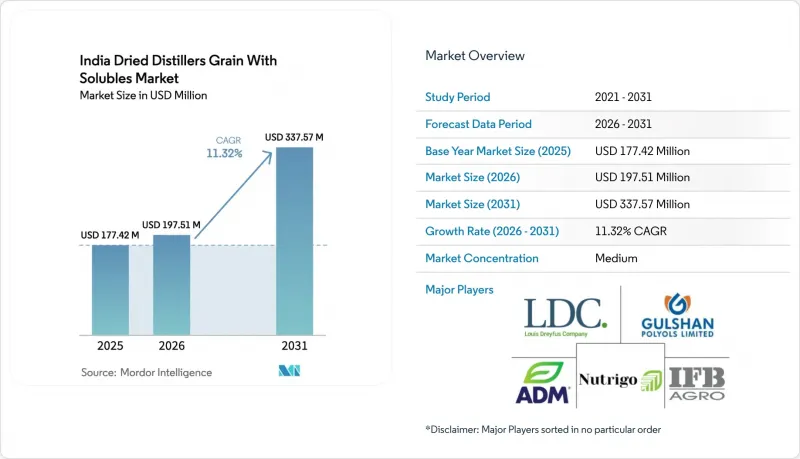
根據 Mordor Intelligence 預測,印度乾餾物殘渣 (DDGS) 市場在 2025 年的價值將達到 1.7742 億美元,從 2026 年的 1.9751 億美元成長到 2031 年的 3.3757 億美元,在預測期(2026-2031 年)為 1.31 年的複合年成長率(2026-2031 年)。
本報告按產品類型(玉米、小麥、米、混合穀物及其他產品類型)和動物類型(反芻動物、家禽、豬、水產養殖及其他動物類型)進行細分。市場預測以美元計價。
印度乾餾物殘渣(DDGS)市場的趨勢與見解。
對永續牲畜飼料原料的需求不斷成長
預計到2024年,印度畜牧業將面臨7,800萬噸濃縮牛飼料的缺口,迫使飼料生產者尋求本地可得且符合循環經濟原則的替代蛋白質來源。 DDGS(乾酒糟)透過將乙醇生產的副產品轉化為飼料,滿足了這些需求,減少了對大豆粕進口的依賴,並節省了外匯。由於DDGS具有穩定的26-30%的蛋白質含量和高消化率(透過適當的品管措施實現),每年生產1700萬噸複合飼料的大型飼料廠都在使用DDGS。隨著肉類加工商擴大採用永續性認證,使用低碳足跡和本地供應鏈的原料正得到推廣。這些因素使得DDGS成為肉類、家禽養殖綜合企業和商業水產養殖設施飼料配方中的重要組成部分。
透過擴大國內乙醇產量來推動DDGS供應。
在印度,每年大約需要101.6億公升乙醇才能達到E20的摻混目標。 2024年中期,以穀物為原料的釀酒廠將供應18.1億公升乙醇,其中11億公升來自玉米,從而帶動了DDGS(乾酒糟)的大量生產。 2025年3月實施的政策允許合作社糖廠在甘蔗榨汁季之外加工玉米和受損穀物,從而實現了DDGS的全年生產。政府提供五年內最高6%的利息補貼以降低資本成本,而印度國家農業合作行銷聯合會(NAMCMF)則確保了穩定的穀物供應。這些措施維持了印度乾酒糟(DDGS)市場的穩定產量。
商品及服務稅(GST)分類及稅負方面的不確定性
印度乾酒糟(DDGS)市場面臨著與商品及服務稅(GST)分類相關的挑戰。這是因為DDGS既可以被歸類為適用5% GST的“動物飼料”,也可以被歸類為適用18% GST的“工業產品”。這種分類的不確定性影響著生產商的定價策略和飼料製造商的採購決策。稅收分類因DDGS的類型而異,例如玉米來源、米來源或混合產品,這導致了市場細分和管理方面的挑戰。印度食品安全標準局(FSSAI)要求用於肉類動物的飼料必須獲得印度標準局(BIS)的認證,這造成了監管成本和延誤,尤其對小規模生產商造成了重大影響。
細分市場分析
預計到2025年,玉米基產品將佔印度乾麥芽渣(DDGS)市場的64.90%。這反映了玉米在穀物釀酒廠的廣泛應用以及其在飼料配製商中的良好認可。印度玉米基DDGS市場受益於馬哈拉斯特拉邦、北方邦和卡納塔克邦乙醇生產基地穩定的品質、可預測的供應以及持續的產能擴張。相關人員青睞玉米基DDGS,是因為其氨基酸組成可靠且波動性低,並且在禽類和乳牛飼料中保持較高的採用率。完善的國內貿易網路促進了玉米基DDGS的分銷,使製糖廠能夠透過期貨合約採購品質穩定的產品。
美國DDGS市場預計到2031年將以11.96%的複合年成長率快速成長。這項成長主要歸功於政府對破損稻米的補貼,酒廠將在2025年以每公擔2,250盧比(約每噸270美元)的補貼價格購買這些稻米。這種原料供應使釀酒廠能夠全年運作,並提供獨特的營養成分,尤其適用於高纖維含量的魚蝦飼料。小麥、大麥和高粱目前仍屬於小眾產品,但在這些穀物是主要輪作作物的地區,它們為飼料配方提供了更大的柔軟性。多樣化的原料組合使飼料生產商能夠嘗試混合DDGS產品,並針對每種飼料最佳化蛋白質、纖維和能量的最佳平衡。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對永續牲畜飼料原料的需求不斷成長
- 透過擴大國內乙醇產量來推動DDGS供應。
- 與傳統飲食相比,這些蛋白質和纖維來源更具成本效益。
- 政府強制推行生質燃料生產,以促進新建釀酒廠。
- 在商業水產養殖飼料混合採用DDGS
- 透過引入高蛋白分級DDGS來提高飼料轉換率
- 市場限制因素
- 商品及服務稅(GST)分類及稅負方面的不確定性
- 動物飼料中過度添加的營養風險
- 國內原料價格波動導致供應中斷
- 從釀酒廠到需求中心的散裝物流有限。
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 玉米
- 小麥
- 米
- 混合穀物
- 其他產品類型(大麥、高粱、bajra)
- 依動物類型
- 反芻動物
- 家禽
- 豬
- 水產養殖
- 其他動物類型(馬、駱駝等)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ADM(Archer Daniels Midland Company)
- Louis Dreyfus Company BV
- IFB Agro Industries Limited
- Globus Spirits Limited
- Grainotch Industries Limited
- Nutrigo Feeds Pvt Ltd(SSL Group)
- Prorich Agro Foods Pvt. Ltd
- Gulshan Polyols Limited(Gulshan Holdings Private Limited)
- Crux BIoTech India Private Limited
- Rainbow BIoTech
- Radha Group of Companies(Rishaan Enterprises)
- Innovative Soch
- CB Agro Food Private Limited
- Prodigy Foods Pvt. Ltd.
- Afzal Industries
第7章 市場機會與未來展望
According to Mordor Intelligence, the India dried distillers grain with solubles market size was valued at USD 177.42 million in 2025 and estimated to grow from USD 197.51 million in 2026 to reach USD 337.57 million by 2031, at a CAGR of 11.32% during the forecast period (2026-2031).
This report is Segmented by Product Type (Corn, Wheat, Rice, Blended Grains, and Other Product Types), and Animal Type (Ruminants, Poultry, Swine, Aquaculture, and Other Animal Types). The Market Forecasts are Provided in Terms of Value (USD).
India Dried Distillers Grain With Solubles Market Trends and Insights
Rising Demand for Sustainable Livestock Feed Ingredients
India's livestock sector faces a cattle concentrate deficit of 78 million metric tons in 2024, compelling feed manufacturers to seek alternative protein sources that are locally available and support circular economy principles. DDGS meets these requirements by converting ethanol byproducts into feed, reducing dependence on soybean meal imports, and conserving foreign exchange. Organized feed mills, which produce 17 million metric tons of compound feed annually, utilize DDGS for its consistent 26-30% protein content and digestibility when managed with appropriate quality control measures. The increasing adoption of sustainability certifications by meat processors encourages the use of ingredients with reduced carbon footprints and localized supply chains. These factors establish DDGS as an essential component in feed formulations for dairy operations, poultry integrators, and commercial aquaculture facilities.
Expansion of Domestic Ethanol Production Drives DDGS Supply
India requires approximately 10.16 billion liters of ethanol annually to achieve E20 blending targets. By mid-2024, grain-based distilleries supplied 1.81 billion liters of ethanol, with maize contributing 1.10 billion liters and generating significant DDGS production. The March 2025 policy allows cooperative sugar mills to process maize and damaged food grains beyond the cane-crushing season, enabling year-round DDGS production. The government provides interest subvention up to 6% for five years to reduce capital costs, while the National Agricultural Cooperative Marketing Federation of India Ltd. ensures stable grain procurement. These measures support consistent DDGS production volumes in the India dried distillers grain with solubles market.
Uncertain GST Classification and Tax Burden
The India dried distillers grain with solubles market faces GST classification challenges, as it can be categorized either as animal feed at 5% GST or as industrial by-products at 18% GST. This classification uncertainty affects pricing strategies for producers and procurement decisions for feed manufacturers. The tax classification varies for different DDGS types, including corn-based, rice-based, and blended products, which creates market fragmentation and administrative challenges. The Food Safety and Standards Authority of India requires Bureau of Indian Standards Certification for animal feeds used in food-producing animals, resulting in regulatory costs and delays that particularly impact small-scale producers.
Other drivers and restraints analyzed in the detailed report include:
- Cost-Effective Protein and Fiber Source Versus Conventional Meals
- Adoption of DDGS in Commercial Aquaculture Feed Blends
- Volatile Domestic Raw Material Prices Disrupt Supply
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Corn accounted for 64.90% of the India dried distillers grain with solubles market share in 2025, reflecting the extensive use of maize within grain-based distilleries and its established acceptance among feed formulators. The India dried distillers grain with solubles market for corn variants benefits from consistent quality, predictable supply, and ongoing capacity additions in ethanol clusters across Maharashtra, Uttar Pradesh, and Karnataka. Industry stakeholders prefer corn DDGS due to its reliable amino acid profiles and lower variability, maintaining high inclusion rates in poultry and dairy diets. Established domestic trading networks strengthen corn DDGS distribution, enabling mills to contract forward volumes with consistent quality.
Rice is experiencing rapid growth with a 11.96% CAGR through 2031. This growth stems from government allocations of damaged and broken rice that distilleries purchase at subsidized rates of Rs 2,250 per quintal (USD 270 per metric ton) in 2025. This raw material supply ensures year-round plant utilization and provides a distinct nutrient profile valuable in fish and shrimp feeds that accommodate higher fiber content. Wheat, barley, and sorghum remain niche products but provide formulation flexibility in regions where these grains dominate crop rotations. The diverse feedstock mix enables feed mills to test blended DDGS products to optimize protein, fiber, and energy balance for species-specific diets.
Complete Report Scope:
- By Product Type
- Corn
- Wheat
- Rice
- Blended Grains
- Other Product Types (Barley, Sorghum, and Bajra)
- By Animal Type
- Ruminants
- Poultry
- Swine
- Aquaculture
- Other Animal Types (Equine, Camel, etc.)
List of Companies Covered in this Report:
- ADM (Archer Daniels Midland Company)
- Louis Dreyfus Company B.V.
- IFB Agro Industries Limited
- Globus Spirits Limited
- Grainotch Industries Limited
- Nutrigo Feeds Pvt Ltd (SSL Group)
- Prorich Agro Foods Pvt. Ltd
- Gulshan Polyols Limited (Gulshan Holdings Private Limited)
- Crux Biotech India Private Limited
- Rainbow Biotech
- Radha Group of Companies (Rishaan Enterprises)
- Innovative Soch
- CB Agro Food Private Limited
- Prodigy Foods Pvt. Ltd.
- Afzal Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Sustainable Livestock Feed Ingredients
- 4.2.2 Expansion of Domestic Ethanol Production Drives DDGS Supply
- 4.2.3 Cost-Effective Protein and Fiber Source Versus Conventional Meals
- 4.2.4 Government Biofuel Mandate Catalyzes New Distilleries
- 4.2.5 Adoption of DDGS in Commercial Aquaculture Feed Blends
- 4.2.6 Introduction of High-Protein Fractionated DDGS Improves Feed Conversion
- 4.3 Market Restraints
- 4.3.1 Uncertain GST Classification and Tax Burden
- 4.3.2 Anti-Nutritional Risks From Excess Inclusion in Animal Rations
- 4.3.3 Volatile Domestic Raw Material Prices Disrupt Supply
- 4.3.4 Limited Bulk Logistics From Distilleries to Demand Centers
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Corn
- 5.1.2 Wheat
- 5.1.3 Rice
- 5.1.4 Blended Grains
- 5.1.5 Other Product Types (Barley, Sorghum, and Bajra)
- 5.2 By Animal Type
- 5.2.1 Ruminants
- 5.2.2 Poultry
- 5.2.3 Swine
- 5.2.4 Aquaculture
- 5.2.5 Other Animal Types (Equine, Camel, etc.)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 ADM (Archer Daniels Midland Company)
- 6.4.2 Louis Dreyfus Company B.V.
- 6.4.3 IFB Agro Industries Limited
- 6.4.4 Globus Spirits Limited
- 6.4.5 Grainotch Industries Limited
- 6.4.6 Nutrigo Feeds Pvt Ltd (SSL Group)
- 6.4.7 Prorich Agro Foods Pvt. Ltd
- 6.4.8 Gulshan Polyols Limited (Gulshan Holdings Private Limited)
- 6.4.9 Crux Biotech India Private Limited
- 6.4.10 Rainbow Biotech
- 6.4.11 Radha Group of Companies (Rishaan Enterprises)
- 6.4.12 Innovative Soch
- 6.4.13 CB Agro Food Private Limited
- 6.4.14 Prodigy Foods Pvt. Ltd.
- 6.4.15 Afzal Industries


