


 |
市場調查報告書
商品編碼
2125388
全球壓力保險閥:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Global Pressure Relief Valves - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,壓力保險閥市場規模將從 2025 年的 51 億美元成長到 2026 年的 53.6 億美元,到 2031 年將達到 68.4 億美元,2026 年至 2031 年的複合年成長率為 5.02%。
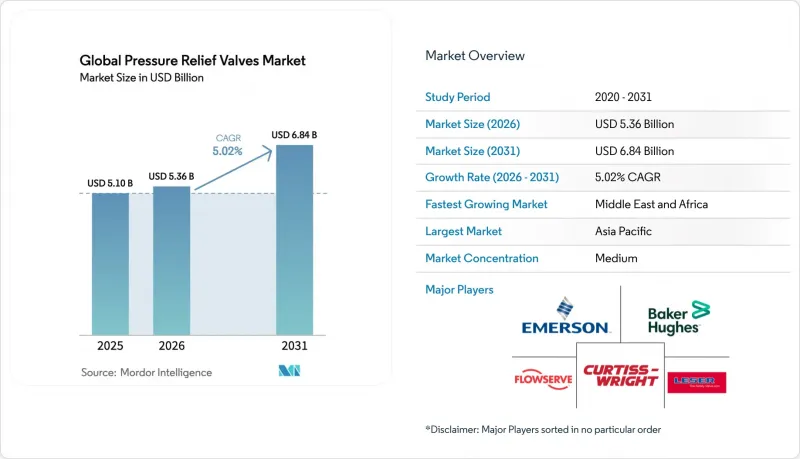
本報告按產品類型(彈簧式、先導式等)、閥門尺寸(2英寸以下、2-6英寸、6英寸以上)、設定壓力(低壓、中壓、高壓)、材質(碳鋼、不銹鋼、合金鋼、特殊材料)、最終用戶(石油天然氣、化學、電力、製藥等)和地區進行細分。市場預測以美元(USD)計價。
全球壓力保險閥市場趨勢及洞察
液化天然氣和氫氣基礎設施的快速擴張需要高度可靠的過壓保護。
對液化天然氣進口終端和綠色氫能專案的巨額投資,推動了對能夠承受低至-162 度C的低溫環境和高達700巴氫氣使用壓力的洩壓裝置的需求。聯合國全球技術法規13號強制要求使用能夠抵禦外部火災並防止儲槽破裂的熱式洩壓裝置,迫使供應商採用耐火合金和快速排氣結構。歐洲工業氣體協會的指南也強調了戶外氫氣堆中精確選擇排氣口尺寸和結構強度的重要性。例如,艾默生公司的TESCOM HV-7000穩壓器器旨在實現700巴車載儲存槽的無污染運行和延長使用壽命。因此,預計這些新興能源產業鏈將帶動洩壓保險閥市場在銷售和價值方面實現顯著成長。
北美和歐盟的流程工業必須遵守 API 526/ASME 標準。
2025版ASME BPVC取消了兩級容器分類,並修訂了附錄47。這導致壓力設備的設計審查更加嚴格,對符合標準的閥門的需求也隨之增加。 API 526規範了孔板尺寸和中心距,簡化了修改流程,但也提高了驗收標準。研究表明,高達85%的閥門性能問題與尺寸、安裝或維護方面的偏差有關,凸顯了OEM廠商主導的培訓和支援的重要性。壓力設備指令2014/68/EU規定,所有壓力超過0.5巴的設備都必須透過認可機構的合格評定,雖然延長了前置作業時間,但有利於擁有內部合規團隊的供應商。
亞洲低成本閥門OEM廠商的崛起給利潤率帶來了壓力。
目前,亞洲供應商正以低成本生產符合API和ASME標準的保險閥,這給現有製造商的利潤空間帶來了壓力。為了保持競爭力,歐美品牌正著力於先進材料、預測性維護和全生命週期支持,而這些對於低價新參與企業來說難以匹敵。雖然價格壓力在通用低壓應用領域最為嚴峻,但在核能、航太和氫能相關應用等嚴苛的運作條件下,先進的工程技術仍然至關重要。
細分市場分析
預計到2025年,彈簧驅動閥將維持其46.55%的市場佔有率,繼續佔據主導地位。這反映了其數十年來在4 psig至6,250 psig壓力範圍和低至-450°F溫度範圍內的廣泛應用。其經濟高效的設計、易於維護和高可用性確保了煉油廠、化工廠和發電鍋爐的穩定需求。隨著營運商優先考慮更嚴格的洩漏控制和在緊湊面積內實現更高容量,預計先導式閥門市場將以7.44%的複合年成長率成長。遙感探測管路和調製閥瓣操作等功能與旨在減少甲烷排放和提高製程效率的數位化壓力控制相契合,推動了這些產品在保險閥市場的應用。
貝克休斯公司的 Consolidated Type 2900 平台體現了混合柔軟性,允許現場切換操作模式以適應不斷變化的製程條件。諸如重錘式、屈曲銷式和平衡波紋管式等專用設備適用於稱重、防篡改校準和背壓降低等應用,但其整體銷售量仍然小規模。因此,供應商正將研發重點放在效能提升能夠支撐溢價的領域,即增強先導操作能力和整合智慧致動器。
到2025年,中口徑(2-6吋)閥門將佔總銷售量的41.02%,滿足石油、化學和發電廠的主流流量需求。然而,隨著LNG接收站、天然氣管道和大型氫氣樞紐對可靠洩壓所需的更大排放面積的需求,預計到2031年,口徑超過6英寸的大口徑閥門市場將以7.74%的複合年成長率成長。艾默生Fischer EZR系列閥門兼具高流量和精確的壓力控制,閥體尺寸最大可達NPS 8,入口壓力最高可達1050 psig。
隨著直徑增大,重量、噴嘴反作用力和噪音等技術挑戰也迅速增加,需要特別考慮。因此,只有具備大規模鑄造和測試能力的供應商才能保持競爭力。直徑小於2英吋的小型閥門仍廣泛應用於實驗室、儀器和製藥撬裝設備等領域,在這些應用中,空間、潔淨度和精確的低流量性能比吞吐量更為重要。
區域分析
預計到2025年,亞太地區將佔全球銷售額的34.18%,繼續成為銷售量成長的基石。中國和印度對氫氣和液化天然氣進口以及大規模藥品生產的投資,推動了當地組裝的規模成長,同時透過許可協議引入了西方原始設備製造商(OEM)的技術。在日本和韓國,先進化工和核能產業對高純度和抗震安全閥的需求,也促進了市場成長。當地的認證體係正與美國石油學會(API)和美國機械工程師協會(ASME)的標準接軌,這有利於亞洲製造的設備出口,並擴大了區域壓力保險閥市場。
預計中東地區將呈現最快成長,到2031年複合年成長率將達到7.22%,這主要得益於現有煉油廠的維修,從而支持全面的閥門更換項目。沙烏地阿拉伯主導的大型煉油廠計畫以及阿拉伯聯合大公國向石化產業的多元化發展,正在擴大對高容量、高溫安全裝置的需求。此外,區域各國政府正在支持綠色氫氣出口中心,進一步增加了對高壓閥門的需求。北美地區持續穩定成長,這主要得益於遵守美國職業安全與健康管理局 (OSHA) 和環境保護署 (EPA) 的嚴格法規,以及頁岩氣中游基礎設施的升級改造。在歐洲,遵守壓力設備指令 (PED) 和脫碳政策正在推動與氫氣和二氧化碳捕集介質相容的閥門的應用。預計拉丁美洲的煉油和採礦業將出現間歇性的項目訂單,而非洲則有望迎來與液化天然氣 (LNG) 出口終端相關的早期商機。在所有地區,數位化監控和預測性維護能力正成為採購決策的關鍵因素,進一步加強了壓力保險閥市場的技術差異化。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 隨著液化天然氣和氫氣基礎設施的快速擴張,需要高度可靠的過壓保護。
- 北美和歐盟的流程工業必須遵守 API 526/ASME 標準。
- 中東地區老舊棕地的維修正在縮短閥門更換週期。
- 智慧製造技術的進步,加上中東地區煉油廠設施老化導致閥門更換需求不斷成長,以及對數位安全閥的需求不斷增加,正在推動市場發展。
- 核能發電廠現代化和安全改進,需要先進的洩壓系統。
- 印度和中國的藥品生產能力擴張正在加速,導致對衛生級防漏劑的需求增加。
- 市場限制因素
- 亞洲低成本閥門OEM製造商的激增給利潤率帶來了壓力。
- 一次性生物處理撬裝設備中爆破磁碟的替代品
- 鎳和不銹鋼價格的波動正在擾亂成本結構。
- 獲得認證(PED、CRN)所需時間延長,導致專案訂單延誤。
- 價值供應鏈分析
- 監管和技術展望
- 全球監管地圖(ASME、API 520/521、PED 2014/68/EU、ISO 4126、KOSHA)
- 智慧互聯的減壓閥感測器、預測性維護和數位孿生技術。
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 彈簧型
- 先導操作
- 死重
- 扣銷
- 平衡風箱
- 閥門尺寸(英吋)
- 2英吋或更小
- 2英寸至6英寸
- 6吋或更大
- 按類型設定壓力
- 低壓(低於 150 psi)
- 中等壓力(15-600 psi)
- 高壓(600 psi 或更高)
- 材料
- 碳鋼
- 不銹鋼
- 合金和特殊材料
- 最終用戶
- 石油和天然氣(上游、中游、下游)
- 化工/石油化工
- 發電(火力發電、核能、可再生能源發電(氫能發電))
- 紙漿和造紙
- 食品/飲料
- 製藥和生物技術
- 供水和污水處理
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞洲國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Emerson Electric Co.
- Baker Hughes Company
- Curtiss-Wright Corp.
- LESER GmbH and Co. KG
- IMI plc
- Flowserve Corporation
- General Electric(Baker Hughes collaboration)
- Alfa Laval AB
- Watts Water Technologies, Inc.
- Weir Group Plc
- Pentair plc
- Spirax-Sarco Engineering plc
- Robertshaw Industrial Products
- Goetze KG Armaturen
- AGF Manufacturing, Inc.
- ValvTechnologies Inc.
- Mercer Valve Co.
- Mack Valves Pty Ltd
- Mercer Industries(PressureGuard)
- Audco India Ltd(LandT Valves)
- Jiangsu Shuangda Pump and Valve Group
第7章 市場機會與未來展望
According to Mordor Intelligence, the pressure relief valves market size is expected to grow from USD 5.1 billion in 2025 to USD 5.36 billion in 2026 and is forecast to reach USD 6.84 billion by 2031 at 5.02% CAGR over 2026-2031.
This report is Segmented by Product Type (Spring-Loaded, Pilot-Operated, and More), Valve Size (Up To 2", 2"-6", Above 6"), Set Pressure (Low, Medium, High), Material (Carbon Steel, Stainless Steel, Alloy and Exotic), End-User (Oil and Gas, Chemical, Power, Pharma, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pressure Relief Valves Market Trends and Insights
Rapid LNG & Hydrogen Infrastructure Expansion Demanding High-Integrity Over-Pressure Protection
Massive investment in LNG import terminals and green hydrogen projects is lifting demand for pressure relief devices engineered for cryogenic temperatures to -162 °C and for hydrogen service pressures up to 700 bar. UN Global Technical Regulation 13 obliges thermal pressure relief devices able to survive external fire while preventing tank rupture, pushing suppliers to adopt fire-resistant alloys and fast-acting discharge geometries. European Industrial Gases Association guidance also stresses accurate vent sizing and structural resilience for outdoor hydrogen stacks. Equipment such as Emerson's TESCOM HV-7000 regulator targets contamination-free operation to extend service life in 700-bar vehicle storage. As a result, the pressure relief valves market gains clear volume and value upside from these emerging energy chains.
Mandatory API 526/ASME Compliance in North America & EU Process Industries
The 2025 ASME BPVC removes the two-class vessel system and revises Appendix 47, raising design scrutiny for pressure equipment and reinforcing demand for code-certified valves. API 526 standardizes orifice sizes and center-to-face dimensions, easing retrofit but tightening acceptance criteria. Studies show that up to 85% of valve performance issues link to deviations from prescribed sizing, installation, or maintenance, placing new emphasis on OEM-led training and support. Pressure Equipment Directive 2014/68/EU requires each device above 0.5 bar to pass conformity assessment by notified bodies, leading to longer lead times yet driving preference for suppliers with in-house compliance teams.
Margin Squeeze from Proliferation of Low-Cost Asian Valve OEMs
Asian suppliers now produce API- and ASME-compliant pressure relief valves at lower cost, compressing margins for incumbents. To stay competitive, Western brands emphasize advanced materials, predictive diagnostics, and full life-cycle support that low-price entrants struggle to match. Price pressure is most acute in commodity low-pressure applications, whereas nuclear, aerospace, and severe-service hydrogen duties still reward premium engineering.
Other drivers and restraints analyzed in the detailed report include:
- Brownfield Revamps of Aging Refining Assets Across Middle East Elevating Valve Replacement Cycles
- Growth of Smart Manufacturing Driving Demand for Digital-Enabled Safety Valves (HART, IIoT)
- Substitution by Rupture Discs in Single-Use Bioprocessing Skids
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Spring-loaded valves retained the largest position with 46.55% share in 2025, reflecting decades of installed equipment across pressure bands from 4 psig to 6,250 psig and temperatures down to -450 °F. Cost-effective construction, simple maintenance, and high availability keep demand stable across refineries, chemical plants, and power boilers. Pilot-operated units are forecast to grow 7.44% CAGR as operators prioritize tighter leakage control and larger capacity within compact footprints. Feature sets such as remote sense lines and modulating disc action align with digital pressures for lower methane emissions and improved process efficiency, reinforcing their uptake in the pressure relief valves market.
Baker Hughes' Consolidated Type 2900 platform exemplifies hybrid flexibility, permitting field conversion between modes to suit changing process conditions. Niche devices-dead-weight, buckling pin, and balanced bellows-address custody transfer, tamper-proof calibration, or back-pressure mitigation, yet their aggregate volume remains modest. Suppliers therefore steer R&D toward pilot-operated enhancements and smart actuator integration where incremental performance justifies premium pricing.
Medium size (2"-6") valves contributed 41.02% revenue in 2025, covering mainstream flow demands in oil, chemical, and power plants. However, the large-bore segment above 6" is projected to rise at 7.74% CAGR to 2031 as LNG terminals, gas pipelines, and mega-scale hydrogen hubs command greater discharge areas for credible relief. Emerson's Fisher EZR series spans bodies up to NPS 8 with 1,050 psig inlet rating, marrying high capacity with fine pressure control.
Engineering challenges scale rapidly with diameter: weight, nozzle reaction forces, and noise require special attention, and only vendors with extensive foundry and test capacity can compete. Small valves under 2" persist in laboratory, instrumentation, and pharmaceutical skids where space, cleanliness, and accurate low-flow performance overrule volume throughput.
Complete Report Scope:
- By Product Type
- Spring-Loaded
- Pilot-Operated
- Dead-Weight
- Buckling Pin
- Balanced Bellows
- By Valve Size (Inch)
- Up to 2 inch
- 2 inch - 6 inch
- Above 6 inch
- By Set Pressure
- Low (less than 150 psi)
- Medium (15 - 600 psi)
- High (greater than 600 psi)
- By Material
- Carbon Steel
- Stainless Steel
- Alloy and Exotic
- By End-User
- Oil and Gas (Upstream, Midstream, Downstream)
- Chemical and Petrochemical
- Power Generation (Thermal, Nuclear, Renewables-Hydrogen)
- Pulp and Paper
- Food and Beverage
- Pharmaceuticals and Biotech
- Water and Waste-Water
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific generated 34.18% of global revenue in 2025 and remains the cornerstone of volume growth. Chinese and Indian investments in hydrogen, LNG import, and bulk pharmaceutical production give local assemblers scale while drawing in Western OEM technology under license. Japan and South Korea add demand from advanced chemical and nuclear sectors that require high purity and seismic-qualified safety valves. Local certification schemes converge with API and ASME, easing export of Asia-fabricated devices and expanding the regional pressure relief valves market.
The Middle East exhibits the quickest 7.22% CAGR through 2031 as brownfield refinery overhauls underpin large, lump-sum valve replacement programs. Saudi-led mega-refining projects and the UAE's diversification into petrochemicals widen the call for high-capacity, high-temperature safety devices. Regional governments also back green hydrogen export hubs, further expanding high-pressure valve demand. North America maintains steady expansion based on stringent OSHA and EPA compliance, plus shale gas midstream infrastructure upgrades. Europe emphasizes PED conformity and decarbonization, encouraging adoption of valves compatible with hydrogen and carbon-capture media. Latin America delivers episodic project awards in refining and mining, while Africa offers early-stage opportunities tied to LNG export terminals. Across all geographies, digital monitoring and predictive maintenance features increasingly factor into procurement decisions, reinforcing technology differentiation in the pressure relief valves market.
- Emerson Electric Co.
- Baker Hughes Company
- Curtiss-Wright Corp.
- LESER GmbH and Co. KG
- IMI plc
- Flowserve Corporation
- General Electric (Baker Hughes collaboration)
- Alfa Laval AB
- Watts Water Technologies, Inc.
- Weir Group Plc
- Pentair plc
- Spirax-Sarco Engineering plc
- Robertshaw Industrial Products
- Goetze KG Armaturen
- AGF Manufacturing, Inc.
- ValvTechnologies Inc.
- Mercer Valve Co.
- Mack Valves Pty Ltd
- Mercer Industries (PressureGuard)
- Audco India Ltd (LandT Valves)
- Jiangsu Shuangda Pump and Valve Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid LNG and Hydrogen Infrastructure Expansion Demanding High-Integrity Over-Pressure Protection
- 4.2.2 Mandatory API 526/ASME Compliance in North America and EU Process Industries
- 4.2.3 Brownfield Revamps of Ageing Refining Assets Across Middle East Elevating Valve Replacement Cycles
- 4.2.4 Growth of Smart Manufacturing Driving Dem of Ageing Refining Assets Across Middle East Elevating Valve Replacement Cyclesand for Digital-Enabled Safety Valves (HART, IIoT)
- 4.2.5 Nuclear Power Plant Modernization and Safety Upgrades Requiring Advanced Pressure Relief Systems
- 4.2.6 Accelerating Pharmaceutical Capacity Adds in India and China Requiring Sanitary PRVs
- 4.3 Market Restraints
- 4.3.1 Margin Squeeze from Proliferation of Low-Cost Asian Valve OEMs
- 4.3.2 Substitution by Rupture Discs in Single-Use Bioprocessing Skids
- 4.3.3 Volatile Nickel and Stainless-Steel Prices Disrupting Cost Structures
- 4.3.4 Extended Certification Lead-Times (PED, CRN) Delaying Project Awards
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.5.1 Global Regulatory Map (ASME, API 520/521, PED 2014/68/EU, ISO 4126, KOSHA)
- 4.5.2 Smart and Connected PRVs - Sensors, Predictive Maintenance and Digital Twins
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Spring-Loaded
- 5.1.2 Pilot-Operated
- 5.1.3 Dead-Weight
- 5.1.4 Buckling Pin
- 5.1.5 Balanced Bellows
- 5.2 By Valve Size (Inch)
- 5.2.1 Up to 2 inch
- 5.2.2 2 inch - 6 inch
- 5.2.3 Above 6 inch
- 5.3 By Set Pressure
- 5.3.1 Low (less than 150 psi)
- 5.3.2 Medium (15 - 600 psi)
- 5.3.3 High (greater than 600 psi)
- 5.4 By Material
- 5.4.1 Carbon Steel
- 5.4.2 Stainless Steel
- 5.4.3 Alloy and Exotic
- 5.5 By End-User
- 5.5.1 Oil and Gas (Upstream, Midstream, Downstream)
- 5.5.2 Chemical and Petrochemical
- 5.5.3 Power Generation (Thermal, Nuclear, Renewables-Hydrogen)
- 5.5.4 Pulp and Paper
- 5.5.5 Food and Beverage
- 5.5.6 Pharmaceuticals and Biotech
- 5.5.7 Water and Waste-Water
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Baker Hughes Company
- 6.4.3 Curtiss-Wright Corp.
- 6.4.4 LESER GmbH and Co. KG
- 6.4.5 IMI plc
- 6.4.6 Flowserve Corporation
- 6.4.7 General Electric (Baker Hughes collaboration)
- 6.4.8 Alfa Laval AB
- 6.4.9 Watts Water Technologies, Inc.
- 6.4.10 Weir Group Plc
- 6.4.11 Pentair plc
- 6.4.12 Spirax-Sarco Engineering plc
- 6.4.13 Robertshaw Industrial Products
- 6.4.14 Goetze KG Armaturen
- 6.4.15 AGF Manufacturing, Inc.
- 6.4.16 ValvTechnologies Inc.
- 6.4.17 Mercer Valve Co.
- 6.4.18 Mack Valves Pty Ltd
- 6.4.19 Mercer Industries (PressureGuard)
- 6.4.20 Audco India Ltd (LandT Valves)
- 6.4.21 Jiangsu Shuangda Pump and Valve Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 小型洩壓閥市場:全球市場預測,2026-2032年線上壓力安全閥市場:全球市場預測(2026-2032年)低雜訊先導式電磁控制保險閥市場:全球市場預測,2026-2032年
 比例式保險閥市場規模、佔有率和成長分析:按閥型、驅動方式、應用、最終用戶、額定壓力和地區分類-2026-2033年產業預測
 真空保險閥(VRV)市場規模、佔有率和成長分析:按閥門類型、材質、應用、最終用戶和地區分類-2026-2033年產業預測
 壓力釋放閥市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 2026年全球壓力保險閥市場報告
 壓力釋放閥市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、分銷管道、地區和競爭格局分類,2021-2031年
 壓力保險閥市場規模、佔有率和成長分析(按產品類型、閥門尺寸、設定壓力、材質、最終用戶和地區分類)-產業預測,2026-2033年
 壓力保險閥市場:2025-2030 年預測