


 |
市場調查報告書
商品編碼
2125331
歐洲商業軟體:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Europe Business Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
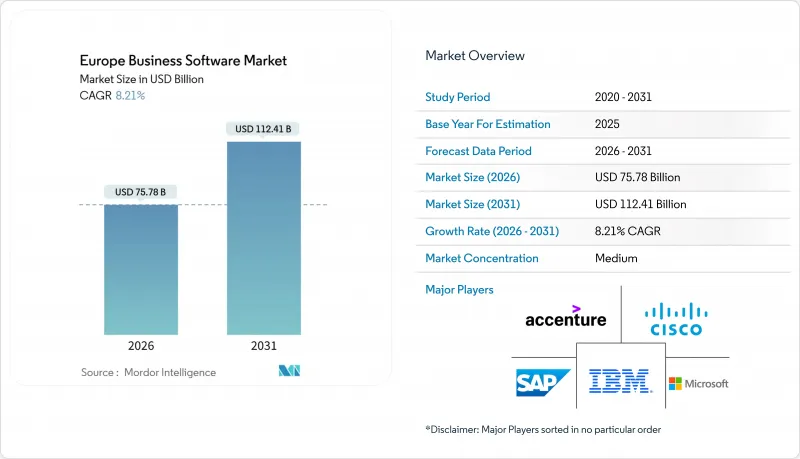
根據 Mordor Intelligence 預測,到 2026 年,歐洲商業軟體市場規模預計將達到 757.8 億美元,年複合成長率為 8.21%,預計到 2031 年銷售額將達到 1,124.1 億美元。
本報告按軟體類型(ERP、CRM、BI 和分析、供應鏈管理及其他)、部署模式(雲端、本地部署)、最終用戶行業(銀行、金融服務和保險、醫療保健和生命科學、公共部門、零售和電子商務及其他)、公司規模(大型企業、中型企業、中小企業)以及地區進行細分。市場預測以美元計價。
歐洲商業軟體市場的趨勢與洞察
歐洲中型企業正在向「雲端優先」模式轉型。
來自復甦與韌性基金 (REF) 的津貼降低了資本門檻,使中型企業能夠淘汰老舊伺服器並採用訂閱式授權模式。歐洲生活和工作條件改善基金會 (Eurofound) 和歐洲職業培訓發展中心 (Cedefop) 聯合發布的 2025 年調查顯示,73% 的中小企業將達到基本的數位化應用水平,但區域差異依然存在,尤其是在南歐地區。英國一項研究表明,透過數位化工具提高 1% 的生產力,可使 GDP 成長 940 億英鎊(1190 億美元),這促使政策制定者支持首席技術官即服務 (CTOaaS) 項目。普華永道的報告顯示,94% 的組織計劃重新設計其雲端架構,以適應地緣政治現實。儘管超大規模資料中心業者雲端服務供應商的收入不斷成長,但德國和法國企業正擴大測試 OVHcloud 和 Scaleway 提供的自主平台,以確保敏感資料留在歐盟境內。只有三分之一的歐洲企業遷移了超過一半的工作負載,這顯示工作負載平台遷移仍有很大的空間。
將人工智慧驅動的決策功能整合到ERP和SCM套件中
生成式人工智慧正在領先的商業套件中從試點階段走向生產階段,從而縮短週期時間並減少人工操作。 SAP 已將「商業人工智慧」整合到 S/4HANA 中,微軟已在 Dynamics 365 供應鏈管理中部署了「Copilot 」,並聲稱其可將預測誤差降低高達 30%。波士頓顧問公司 (BCG) 估計,生成式模型可將 ERP 實施所需的工作量減少 20% 至 40%。 Oracle、 銷售團隊和區域供應商正在競相追趕這些能力,這促使買家期望將預測分析作為基本要求。歐洲製造商是早期採用者,他們利用人工智慧驅動的視覺化工具來抵消半導體短缺的影響。阿波羅輪胎的歐洲分公司透過最佳化配送路線節省了 920 萬英鎊(1,170 萬美元)。隨著採購團隊開始將智慧自動化納入提案招標書 (RFP) 模板,無法提供可靠人工智慧藍圖的供應商將面臨產品同質化的風險。
歐盟低程式碼平台人才短缺問題仍未解決
根據歐盟委員會預測,到2024年,77%的企業將面臨資訊通訊技術(ICT)專業人才招募難題,這將阻礙低程式碼技術的普及,儘管公民開發潛力巨大。只有54%的人口具備基本的數位技能,而API設計和網路安全等高階技能的短缺更為嚴重。經合組織對捷克中小企業的分析發現,僅有16%的企業投資於ICT培訓,此趨勢在中東歐多個市場普遍存在。這種人才缺口正在造成市場兩極化。大型企業正在採用低程式碼技術來加速解決積壓問題,而中型企業仍處於概念驗證(PoC)階段。供應商正透過培訓項目來應對這項挑戰,但進展緩慢,導致許可銷售的成長預期放緩。
細分市場分析
企業資源規劃 (ERP) 應用軟體預計到 2025 年將佔銷售額的 34.19%,凸顯其在歐洲商業軟體市場財務、採購和人力資本交易中的核心地位。受歐盟資料法強制推行開放資料模型以及基於代理的儀錶板普及的推動,商業智慧和分析套件預計將以 9.43% 的複合年成長率 (CAGR) 實現最高成長。供應商正在整合自然語言介面和預測邏輯,無需手動執行 SQL 操作即可提取洞察,從而縮短業務部門經理的決策週期。
在決策流程中,客戶關係管理 (CRM) 仍然至關重要,尤其是在金融服務領域;同時,隨著製造商為應對地緣政治風險而將採購本地化,供應鏈管理的重要性也日益凸顯。隨著《企業永續發展報告指令》的實施,歐洲新興細分領域(例如環境、社會和管治(ESG) 報告)的商業軟體市場正在迅速擴張,為專業供應商提供了立足之地。競爭格局正朝著可組合架構的方向發展,使客戶能夠從 SAP、Microsoft、 銷售團隊以及越來越多的中端市場專業供應商的產品中建立最佳組合。
預計到2025年,雲端運算將佔總營收的72.34%,並且到2031年,該細分市場預計將以9.85%的複合年成長率成長,超過歐洲商業軟體市場的整體成長率。超大規模資料中心業者正將其資料中心從都柏林擴展到華沙,以確保大多數用戶的延遲低於20毫秒。然而,公共採購中的主權條款要求供應商保證在區域和歐洲法律管轄範圍內進行資料處理,從而創建了一層新的保護機制,在合規性和創新之間取得平衡。
本地部署解決方案在關鍵基礎設施、國防和某些銀行業務工作負載中仍然發揮著至關重要的作用,但即使是這些用戶也擴大採用容器化平台,以便在私有雲和公有雲環境之間遷移。多重雲端配置正在主導架構藍圖的發展,使企業柔軟性最佳化價格和容錯能力。隨著預留實例合約的日益普及,財務部門正在加強財務營運 (FinOps) 實踐,以控制預算外支出,這鞏固了雲端作為預設部署選擇的地位,儘管超大規模資料中心業者在歐洲商業軟體市場的佔有率成長正在放緩。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐洲中型企業正在向「雲端優先」模式轉型。
- 將人工智慧驅動的決策功能整合到ERP和SCM套件中
- 英國脫歐後時代,為加強合規性,對多實體融資套件的需求增加。
- 歐盟數據法正在推動SaaS分析的現代化。
- 綠色分類法促進ESG報告模組的採用
- 製造業復甦基金(IPCEI)正在推動垂直產業ERP系統的發展。
- 市場限制因素
- 歐盟低程式碼平台人才短缺問題仍未解決
- 人們越來越擔心美國託管的SaaS的主權問題
- 增值稅(VAT)體系的分散化使多邊行動變得複雜。
- 使用超大規模資料中心業者會增加總擁有成本 (TCO)。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 軟體類型
- ERP軟體
- CRM軟體
- 商業智慧和分析軟體
- 供應鏈管理軟體
- 其他軟體類型
- 按部署模式
- 雲
- 現場
- 按最終用戶行業分類
- BFSI
- 醫療保健和生命科學
- 公共部門和機構
- 零售與電子商務
- 運輸/物流
- 製造業和工業部門
- 通訊與媒體
- 按公司規模
- 大公司
- 中號
- 小規模企業
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- SAP SE
- Oracle Corporation
- Microsoft Corporation
- Salesforce, Inc.
- International Business Machines Corporation
- The Sage Group plc
- Infor Global Solutions, LLC
- IFS AB
- Unit4 NV
- Epicor Software Corporation
- Workday, Inc.
- Dassault Systemes SE
- Siemens Aktiengesellschaft
- Software AG
- QlikTech International AB
- Tableau Software, LLC
- HubSpot, Inc.
- Zoho Corporation
- Odoo SA
- Litmos, LLC
- Pipedrive OU
- Kinaxis Inc.
- Manhattan Associates, Inc.
- WiseTech Global Limited
- TOTVS Labs Europe Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe business software market size stood at USD 75.78 billion in 2026 and is projected to register an 8.21% CAGR, lifting revenue to USD 112.41 billion by 2031.
This report is Segmented by Software Type (ERP, CRM, BI and Analytics, Supply-Chain Management, and Other), Deployment Model (Cloud, and On-Premise), End-User Vertical (BFSI, Healthcare and Life Sciences, Public Sector, Retail and E-Commerce, and More), Enterprise Size (Large, Mid-Sized, and Small), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Europe Business Software Market Trends and Insights
Cloud-First Shift Across European Mid-Market Firms
Recovery and Resilience Facility grants are lowering capital barriers, allowing mid-sized enterprises to decommission aging servers and adopt subscription licenses. Eurofound and Cedefop found in 2025 that 73% of small and medium-sized enterprises had reached basic digital intensity, yet regional disparities persist, especially in Southern Europe. United Kingdom studies suggest that a 1% productivity uplift from digital tools could add GBP 94 billion (USD 119 billion) to GDP, encouraging policymakers to underwrite CTO-as-a-service programs. PwC reported that 94% of organizations plan to redesign cloud architecture to reflect geopolitical realities. Hyperscaler revenue is therefore climbing, yet German and French enterprises increasingly trial sovereign platforms from OVHcloud and Scaleway to keep sensitive data inside the bloc. Because only one-third of European firms have migrated more than half of their workloads, a substantial runway remains for workload re-platforming.
AI-Enabled Decisioning Embedded in ERP and SCM Suites
Generative AI is moving from pilot to production across core business suites, trimming cycle times and reducing manual effort. SAP infused Business AI into S/4HANA, while Microsoft launched Copilot inside Dynamics 365 Supply Chain Management, claiming up to 30% forecast-error reductions. BCG estimates that generative models can cut ERP implementation labour by 20-40%. Oracle, Salesforce, and regional vendors are racing to match these capabilities, shifting buyer expectations so that predictive analytics becomes a baseline requirement. European manufacturers are early adopters, using AI-driven visibility tools to offset semiconductor shortages; Apollo Tyres' European division saved GBP 9.2 million (USD 11.7 million) through route optimization. Vendors unable to release credible AI roadmaps risk commoditization as procurement teams bake intelligent automation into request-for-proposal templates.
Unresolved EU-Wide Skills Shortage in Low-Code Platforms
The European Commission reported that 77% of enterprises struggled to hire ICT specialists in 2024, hindering low-code uptake despite the promise of citizen development. Only 54% of the population has basic digital skills, while advanced competencies such as API design and cybersecurity remain scarcer. OECD analysis of Czech SMEs showed just 16% invest in ICT training, a pattern mirrored across several Central and Eastern European markets. This talent gap bifurcates the market: large enterprises deploy low-code to accelerate backlog reduction, whereas mid-market firms remain stuck at proof-of-concept. Vendors are responding with academy programs, but progress is slow, placing a drag on license growth forecasts.
Other drivers and restraints analyzed in the detailed report include:
- EU Data Act Spurring SaaS Analytics Modernization
- Green-Taxonomies Driving ESG Reporting Module Uptake
- Mounting Sovereignty Concerns over US-Hosted SaaS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Enterprise resource planning applications accounted for 34.19% of 2025 revenue, confirming their role as the transactional backbone for finance, procurement, and human capital across Europe Business Software market deployments. Business intelligence and analytics suites are poised to record the fastest 9.43% CAGR, helped by EU Data Act mandates that require open data models and the proliferation of agent-based dashboarding. Vendors are embedding natural language interfaces and predictive logic that surface insights without manual SQL, which shortens decision loops for line-of-business managers.
In the decision stack, customer relationship management remains crucial, especially in financial services, while supply chain management gains urgency as manufacturers localize sourcing to manage geopolitical risk. The Europe Business Software market size for emerging niches such as environmental, social, and governance reporting has grown rapidly following the Corporate Sustainability Reporting Directive, giving pure-play providers an entry wedge. Competitive positioning is shifting toward composable architectures, allowing customers to assemble best-of-breed combinations from SAP, Microsoft, Salesforce, and a growing roster of mid-market specialists.
Cloud installations comprised 72.34% of total revenue in 2025, and the segment is likely to outpace overall Europe Business Software market growth at a 9.85% CAGR through 2031. Hyperscalers are expanding data-center footprints from Dublin to Warsaw, ensuring sub-20-millisecond latency for most users. Yet sovereignty clauses in public tenders oblige providers to guarantee in-region processing and European legal jurisdiction, spawning a new tier of protected instances that balance compliance and innovation.
On-premises remains relevant for critical infrastructure, defense, and certain bank workloads, but even these users are adopting containerized platforms that can shift between private and public environments. Multi-cloud configurations dominate architecture roadmaps, giving enterprises flexibility to arbitrage pricing and resilience. As reserved-instance contracts proliferate, finance teams are sharpening FinOps practices to limit unbudgeted consumption, moderating the Europe Business Software market share gains of hyperscalers but solidifying cloud as the default deployment choice.
Complete Report Scope:
- By Software Type
- ERP Software
- CRM Software
- BI and Analytics Software
- Supply-Chain Management Software
- Other Software Type
- By Deployment Model
- Cloud
- On-premise
- By End-User Vertical
- BFSI
- Healthcare and Life Sciences
- Public Sector and Institutions
- Retail and E-commerce
- Transportation and Logistics
- Manufacturing and Industrials
- Telecom and Media
- By Enterprise Size
- Large Enterprises
- Mid-sized
- Small Businesses
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- SAP SE
- Oracle Corporation
- Microsoft Corporation
- Salesforce, Inc.
- International Business Machines Corporation
- The Sage Group plc
- Infor Global Solutions, LLC
- IFS AB
- Unit4 N.V.
- Epicor Software Corporation
- Workday, Inc.
- Dassault Systemes SE
- Siemens Aktiengesellschaft
- Software AG
- QlikTech International AB
- Tableau Software, LLC
- HubSpot, Inc.
- Zoho Corporation
- Odoo S.A.
- Litmos, LLC
- Pipedrive OU
- Kinaxis Inc.
- Manhattan Associates, Inc.
- WiseTech Global Limited
- TOTVS Labs Europe Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-First Shift Across European Mid-Market Firms
- 4.2.2 AI-Enabled Decisioning Embedded in ERP and SCM Suites
- 4.2.3 Post-BREXIT Compliance Push for Multi-Entity Finance Suites
- 4.2.4 EU Data Act Spurring SaaS Analytics Modernization
- 4.2.5 Green-Taxonomies Driving ESG Reporting Modules Uptake
- 4.2.6 Manufacturing Renaissance Funds (IPCEI) Favouring Vertical ERP
- 4.3 Market Restraints
- 4.3.1 Unresolved EU-Wide Skills Shortage in Low-Code Platforms
- 4.3.2 Mounting Sovereignty Concerns over US-Hosted SaaS
- 4.3.3 Fragmented VAT Regimes Complicating Multi-Country Rollouts
- 4.3.4 Rising Total-Cost-of-Ownership for Hyperscaler Consumption
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Software Type
- 5.1.1 ERP Software
- 5.1.2 CRM Software
- 5.1.3 BI and Analytics Software
- 5.1.4 Supply-Chain Management Software
- 5.1.5 Other Software Type
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.3 By End-User Vertical
- 5.3.1 BFSI
- 5.3.2 Healthcare and Life Sciences
- 5.3.3 Public Sector and Institutions
- 5.3.4 Retail and E-commerce
- 5.3.5 Transportation and Logistics
- 5.3.6 Manufacturing and Industrials
- 5.3.7 Telecom and Media
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Mid-sized
- 5.4.3 Small Businesses
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 SAP SE
- 6.4.2 Oracle Corporation
- 6.4.3 Microsoft Corporation
- 6.4.4 Salesforce, Inc.
- 6.4.5 International Business Machines Corporation
- 6.4.6 The Sage Group plc
- 6.4.7 Infor Global Solutions, LLC
- 6.4.8 IFS AB
- 6.4.9 Unit4 N.V.
- 6.4.10 Epicor Software Corporation
- 6.4.11 Workday, Inc.
- 6.4.12 Dassault Systemes SE
- 6.4.13 Siemens Aktiengesellschaft
- 6.4.14 Software AG
- 6.4.15 QlikTech International AB
- 6.4.16 Tableau Software, LLC
- 6.4.17 HubSpot, Inc.
- 6.4.18 Zoho Corporation
- 6.4.19 Odoo S.A.
- 6.4.20 Litmos, LLC
- 6.4.21 Pipedrive OU
- 6.4.22 Kinaxis Inc.
- 6.4.23 Manhattan Associates, Inc.
- 6.4.24 WiseTech Global Limited
- 6.4.25 TOTVS Labs Europe Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 商業應用:研究訂閱
 2026年全球商業數據分析工具市場報告
 商業軟體與服務市場-2026-2032年全球市場預測2026年全球商業軟體服務市場報告2026年全球商業軟體市場報告2026年全球商業計劃審查服務市場報告
 2026-2030年全球商業軟體服務市場
 商業軟體和服務市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶、模組和功能分類智慧選股服務軟體市場:依部署模式、定價模式和最終用戶類型分類-全球預測(2026-2032年)
 商業軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)