


 |
市場調查報告書
商品編碼
2125261
消費者身分和存取管理:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Consumer Identity And Access Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
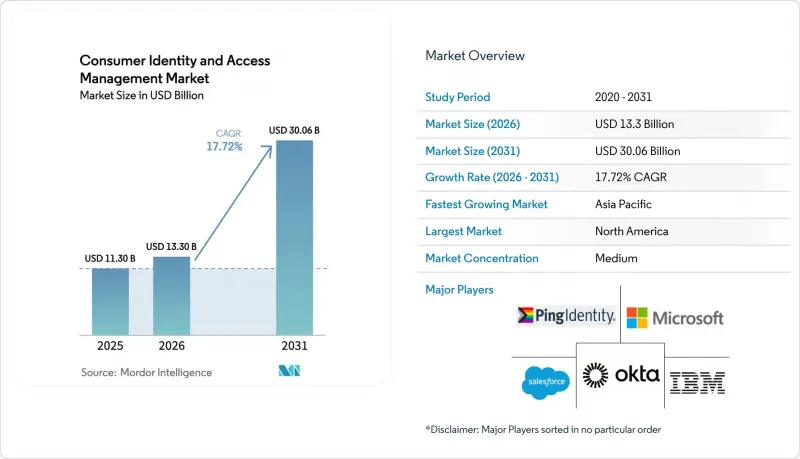
據 Mordor Intelligence 稱,2025 年消費者身分和存取管理市場價值為 113 億美元,預計到 2031 年將達到 300.6 億美元,而 2026 年為 133 億美元,預測期(2026-2031 年)的複合年成長率為 17.72%。
本報告按組件(解決方案、服務)、部署模式(基於雲端、本地部署)、最終用戶行業(銀行、金融服務和保險、醫療保健、IT 和電信、政府、能源和公共產業、交通運輸、航太航太和國防、教育)、身份驗證類型(多因素身份驗證 (MFA)、其他)、組織規模(大型企業、中小企業 (SME))和地區分類。
全球消費者身分和存取管理市場趨勢及洞察
利用世代人工智慧的自適應身份驗證
生成式人工智慧正在將客戶身分和存取管理 (CIAM) 從被動控制轉變為預測性風險評估。 Strivacity 的「AI Assist」能夠即時分析使用者旅程並自動進行合規性檢查,分析師預測,到 2025 年,35% 的組織將把生成式人工智慧融入其身分識別管理功能中。基於行為、裝置指紋和情境的動態策略可在增強安全性的同時減少使用者麻煩。這正是醫療服務提供者所重視的平衡,例如整合 Clear 和 Epic 系統以加快病患登入速度。自適應機制可根據個人風險狀況自訂分層身分驗證要求,從而減少因過度身份驗證而導致的疲勞,進而降低轉換率。
人們越來越意識到隱私和用戶體驗 (UX) 之間的權衡,這正在推動預算增加。
隨著eIDAS 2.0協議於2024年5月生效,歐盟成員國必須在2026年前發行國家數位身分錢包,這迫使企業採用以隱私為中心的客戶身分和存取管理(CIAM)策略。隨著消費者對流暢用戶體驗的需求日益成長,企業正在摒棄以往優先考慮安全性而忽視便利性的傳統登入介面。醫療保健機構便是這項轉變的典型例證。身份錢包允許患者跨網路存取其醫療記錄,同時確保符合HIPAA法規。隱私正從阻礙因素轉變為提升用戶體驗的推動因素。
API 層的機器人攻擊速度超過了 CIAM 的反應速度。
利用 API 漏洞的機器人正在擾亂客戶體驗並推高安全成本。目前,企業平均管理 613 個 API 端點,這擴大了攻擊面。預計到 2024 年,相關安全事件將增加 28%,每年造成 1,860 億美元的損失。有效的威懾需要將客戶身分和存取管理 (CIAM) 與專用 API 安全分析整合,但這需要投入大量預算並耗費大量時間。
細分市場分析
隨著企業對承包部署的需求日益成長,業務收益正在超越軟體收入。到2025年,在解決方案市場中,組件部分將佔消費者身分和存取管理市場佔有率的62.85%,而服務預計到2031年將以18.6%的年均成長率成長。大型企業正在編配給專業公司,中小企業也紛紛效仿,JumpCloud的一項調查顯示,42%的中小企業表示已將業務外包。
隨著隱私、自適應身分驗證和多通路同意流程變得日益複雜,託管服務的重要性日益凸顯。醫療機構依賴清晰的整合能力,以最大限度地減少內部編碼工作。隨著消費者身分和存取管理市場的擴張,企業與競爭對手的差異化優勢正從功能清單轉向實施品質。
到 2025 年,雲端採用將佔消費者身分和存取管理市場 77.35% 的佔有率,隨著傳統本地部署環境的逐步淘汰,預計將以 19.35% 的複合年成長率成長。微軟的 Entra ID 提供持續的功能,並讓規避風險的產業相信,雲端能夠達到甚至超越安全標準。
儘管混合部署仍然存在,以滿足資料主權和低延遲的需求,但絕大多數新部署都預設為雲端。企業優先考慮 API 優先的可擴展性和自動擴展。託管服務供應商透過建立標準化堆疊、加快價值實現速度以及確保跨區域的合規資訊保持最新,進一步強化了企業對雲端的偏好。
區域分析
北美地區在2025年佔據了43.25%的收入佔有率,這主要得益於成熟的企業級專案和豐富的供應商生態系統。儘管持續改進的重點在於自適應風險分析和CPRA合規性,但隨著基礎採用率的提高,整體成長速度正在放緩。正如CISA的研究所示,政府對中小企業成本效益的關注正在推動更廣泛的應用,並維持消費者身分和存取管理市場的活力。
亞太地區預計將以17.98%的複合年成長率實現最高增速,這主要得益於政府主導的身份錢包計劃、超級應用帶來的經濟影響以及行動優先的消費習慣。經合組織成員國的資訊通訊技術(ICT)預計到2024年平均成長率將達到7.6%,而亞太地區主要國家的成長率預計更高,這為身分認同平台的發展提供了沃土。供應商正在推動資料儲存本地化並遵守各國標準,以滿足市場需求。
在歐洲,受「eIDAS 2.0」的推動,市場正在擴張。該法案要求在2026年實現電子錢包的互通性。隨著公共和私營部門在通用數位身分框架上的合作,這項措施有望進一步擴大消費者身分和存取管理市場。歐洲供應商憑藉其在隱私保護領域的領先地位,在向海外輸出專業知識方面具有優勢,但由於部署進度不一和經濟逆風等因素,實施過程中也存在一定的風險。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 利用世代人工智慧的自適應身份驗證
- 人們越來越意識到隱私和使用者體驗之間的權衡,這推動了 CIAM 預算的增加。
- 嵌入式金融和超級應用程式的激增正在推動對聯合式客戶身分和存取管理 (CIAM) 的需求不斷成長。
- 關於PSD3/CPRA知情同意管理的合規義務
- 大型科技公司推出無密碼 FIDO2 後,密碼金鑰就廣泛應用了。
- 數位身分錢包的興起(eIDAS 2.0,NIST)
- 市場限制因素
- API 層機器人攻擊的成長速度超過了 CIAM 實施的反制措施的反應速度。
- 由於有關資料居住碎片化的法律(例如印度、巴西、阿拉伯聯合大公國),總擁有成本上升。
- CIO在CIAM編配和DevSecOps整合方面的技能差距
- 由於備受矚目的個人資料外洩事件導致顧客信任度下降(Okta 2023)
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 解決方案
- 身份驗證和授權
- 身份驗證和證明
- 使用者畫像和同意管理
- 服務
- 專業的
- 管理
- 解決方案
- 部署模式
- 基於雲端的
- 現場
- 按最終用戶行業分類
- BFSI
- 衛生保健
- 資訊科技/通訊
- 政府
- 能源與公共產業
- 運輸
- 航太/國防
- 教育
- 按身份驗證類型
- 多因素身份驗證 (MFA)
- 無密碼/密碼金鑰
- 生物識別
- 社群登入和聯合登入
- 按組織規模
- 大公司
- 中小企業
- 地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他東協國家
- 中東和非洲
- GCC
- 土耳其
- 南非
- 其他非洲地區
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- IBM Corporation
- Okta 公司(包括 Auth0)
- Ping Identity Holdings
- ForgeRock Inc.
- Salesforce Inc.
- Amazon Web Services Inc.
- Broadcom Inc.(Symantec)
- Thales Group(Gemalto)
- HID Global(Assa Abloy)
- CyberArk Software Ltd.
- Micro Focus Intl. plc
- Duo Security(Cisco)
- OneLogin(One Identity)
- Strivacity
- Frontegg
- LoginRadius Inc.
- Authgear
- SAASPASS Inc.
- IDCUBE Systems Pvt Ltd.
- AlertEnterprise Inc.
- Convergint Technologies LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the customer identity and access management market size was valued at USD 11.3 billion in 2025 and estimated to grow from USD 13.3 billion in 2026 to reach USD 30.06 billion by 2031, at a CAGR of 17.72% during the forecast period (2026-2031).
This report is Segmented by Component (Solutions, Services), Deployment Mode (Cloud-Based, On-Premise), End-User Industry (BFSI, Healthcare, IT and Telecom, Government, Energy and Utilities, Transportation, Aerospace and Defense, Education), Authentication Type (Multifactor (MFA), and More), Organisation Size (Large Enterprises, Small- and Medium-Sized Enterprises (SMEs)), and Geography.
Global Consumer Identity And Access Management Market Trends and Insights
Gen-AI Adaptive Authentication
Generative AI moves CIAM from reactive control to predictive risk assessment. Strivacity's AI Assist shows real-time analysis of user journeys and automated compliance checks, and analysts expect 35% of organizations to embed generative AI in identity functions by 2025. Dynamic policies based on behavior, device fingerprinting, and context trim user friction while raising security, a balance valued by healthcare providers integrating Clear with Epic for rapid patient sign-in. Adaptive mechanisms tailor step-up requirements to individual risk profiles and mitigate over-authentication fatigue that erodes conversion rates.
Growing Privacy-UX Trade-off Awareness Drives Budgets
The eIDAS 2.0 mandate effective May 2024 obliges EU states to issue national digital identity wallets by 2026, pushing enterprises to adopt privacy-protective CIAM strategies. Consumers demand frictionless journeys, so firms abandon legacy log-in screens that prioritize security at the expense of convenience. Healthcare providers illustrate this pivot; identity wallets let patients retrieve records across networks while retaining HIPAA compliance. Privacy moves from blocker to enabler of superior user experience.
API-layer Bot Attacks Outpace CIAM Mitigation Speed
Bots exploiting APIs compromise customer journeys and raise security costs. Enterprises now manage an average 613 API endpoints that widen attack surfaces, and related incidents climbed 28% in 2024, costing USD 186 billion annually. Effective deterrence requires integrating CIAM with dedicated API security analytics, stretching budgets, and prolonging roll-outs.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Embedded Finance & Super-apps Requiring Federated CIAM
- Mandatory PSD3/CPRA Consent Orchestration Compliance
- CIO Skill Gap in CIAM Orchestration & DevSecOps Integration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services revenue is outpacing software as firms seek turnkey deployment. The component segment captured 62.85% of the customer identity and access management market size for solutions in 2025, yet services are forecast to grow 18.6% annually through 2031. Large enterprises shift orchestration to experts, and SMEs, citing JumpCloud's survey of 42% outsourcing, follow suit.
The rising complexity of privacy, adaptive authentication, and multi-channel consent workflows makes managed services attractive. Healthcare organizations rely on Clear integrations that minimize in-house coding. As customer identity and access management market adoption broadens, competitive differentiation leans more on implementation quality than feature checklists.
Cloud installations accounted for 77.35% share of the customer identity and access management market size in 2025 and will advance at a 19.35% CAGR as legacy on-premise estates retire. Microsoft's Entra ID showcases continuous feature delivery, convincing risk-averse sectors that cloud meets or exceeds security benchmarks.
Hybrid deployments remain for data-sovereignty or low-latency needs, but most new roll-outs default to cloud. Enterprises prize API-first extensibility and automated scaling. Managed service providers build standardized stacks that shorten time-to-value and keep compliance artefacts current across regions, reinforcing cloud preference.
Complete Report Scope:
- By Component
- Solutions
- Authentication and Authorisation
- Identity Verification and Proofing
- User Profile and Consent Management
- Services
- Professional
- Managed
- Solutions
- By Deployment Mode
- Cloud-based
- On-premise
- By End-user Industry
- BFSI
- Healthcare
- IT and Telecom
- Government
- Energy and Utilities
- Transportation
- Aerospace and Defense
- Education
- By Authentication Type
- Multifactor (MFA)
- Passwordless / Passkey
- Biometric
- Social and Federated Login
- By Organisation Size
- Large Enterprises
- Small- and Medium-sized Enterprises (SMEs)
- Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of ASEAN
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America held 43.25% of 2025 revenue owing to entrenched enterprise programs and plentiful vendor ecosystems. Ongoing enhancements focus on adaptive risk analytics and regulatory alignment with CPRA, yet overall expansion rates moderate as base penetration grows. Government attention on SME affordability, reflected in CISA studies, supports broader adoption and keeps the customer identity and access management market vibrant.
Asia-Pacific is forecast to record the fastest 17.98% CAGR, propelled by government identity wallet schemes, super-app economics, and mobile-first consumer habits. ICT growth across OECD member economies averaged 7.6% in 2024 and was higher in leading APAC nations, underlining fertile ground for identity platforms. Vendors localize data storage and comply with national standards to capture demand.
Europe advances on the back of eIDAS 2.0, which mandates interoperable wallets by 2026. The initiative will enlarge the customer identity and access management market as public and private sectors converge on shared digital ID frameworks. Privacy leadership positions European vendors to export expertise abroad, although varied implementation timelines and economic headwinds inject execution risk.
- Microsoft Corporation
- IBM Corporation
- Okta Inc. (incl. Auth0)
- Ping Identity Holdings
- ForgeRock Inc.
- Salesforce Inc.
- Amazon Web Services Inc.
- Broadcom Inc. (Symantec)
- Thales Group (Gemalto)
- HID Global (Assa Abloy)
- CyberArk Software Ltd.
- Micro Focus Intl. plc
- Duo Security (Cisco)
- OneLogin (One Identity)
- Strivacity
- Frontegg
- LoginRadius Inc.
- Authgear
- SAASPASS Inc.
- IDCUBE Systems Pvt Ltd.
- AlertEnterprise Inc.
- Convergint Technologies LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Gen-AI-Powered Adaptive Authentication
- 4.2.2 Growing Privacy-UX Trade-Off Awareness Drives CIAM Budgets
- 4.2.3 Surge in Embedded Finance and Super-Apps Requiring Federated CIAM
- 4.2.4 Mandatory PSD3/CPRA Consent Orchestration Compliance
- 4.2.5 Passwordless FIDO2 Rollout by Big Tech Normalises Passkeys
- 4.2.6 Rise of Digital Identity Wallets (Eidas 2.0, NIST)
- 4.3 Market Restraints
- 4.3.1 API-Layer Bot Attacks Outpace CIAM Mitigation Speed
- 4.3.2 Fragmented Data-Residency Laws (E.G., India, Brazil, UAE) Inflate TCO
- 4.3.3 CIO Skill-Gap in CIAM Orchestration and Devsecops Integration
- 4.3.4 Customer-Trust Erosion From High-Profile Identity Breaches (Okta 2023)
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Authentication and Authorisation
- 5.1.1.2 Identity Verification and Proofing
- 5.1.1.3 User Profile and Consent Management
- 5.1.2 Services
- 5.1.2.1 Professional
- 5.1.2.2 Managed
- 5.1.1 Solutions
- 5.2 By Deployment Mode
- 5.2.1 Cloud-based
- 5.2.2 On-premise
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Healthcare
- 5.3.3 IT and Telecom
- 5.3.4 Government
- 5.3.5 Energy and Utilities
- 5.3.6 Transportation
- 5.3.7 Aerospace and Defense
- 5.3.8 Education
- 5.4 By Authentication Type
- 5.4.1 Multifactor (MFA)
- 5.4.2 Passwordless / Passkey
- 5.4.3 Biometric
- 5.4.4 Social and Federated Login
- 5.5 By Organisation Size
- 5.5.1 Large Enterprises
- 5.5.2 Small- and Medium-sized Enterprises (SMEs)
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of ASEAN
- 5.6.5 Middle East and Africa
- 5.6.5.1 GCC
- 5.6.5.2 Turkey
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 IBM Corporation
- 6.4.3 Okta Inc. (incl. Auth0)
- 6.4.4 Ping Identity Holdings
- 6.4.5 ForgeRock Inc.
- 6.4.6 Salesforce Inc.
- 6.4.7 Amazon Web Services Inc.
- 6.4.8 Broadcom Inc. (Symantec)
- 6.4.9 Thales Group (Gemalto)
- 6.4.10 HID Global (Assa Abloy)
- 6.4.11 CyberArk Software Ltd.
- 6.4.12 Micro Focus Intl. plc
- 6.4.13 Duo Security (Cisco)
- 6.4.14 OneLogin (One Identity)
- 6.4.15 Strivacity
- 6.4.16 Frontegg
- 6.4.17 LoginRadius Inc.
- 6.4.18 Authgear
- 6.4.19 SAASPASS Inc.
- 6.4.20 IDCUBE Systems Pvt Ltd.
- 6.4.21 AlertEnterprise Inc.
- 6.4.22 Convergint Technologies LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 消費者識別及存取管理市場-2026-2032年全球市場預測
 2026年全球消費者身分和訪問管理市場報告
 消費者身分和存取管理市場:依解決方案、部署類型和最終用途劃分 - 全球預測至 2036 年
 消費者身分和存取管理市場 - 全球產業規模、佔有率、趨勢、機會和預測(按解決方案、服務、部署類型、垂直產業、地區和競爭格局分類,2021-2031 年)
 消費者身分和存取管理市場規模、佔有率和成長分析(按組件、部署類型、身分驗證方法、最終用戶產業和地區分類)-2026-2033年產業預測
 美國消費者身分和存取管理:市場佔有率分析、行業趨勢和統計數據、成長預測(2025-2030 年)
 全球消費者身分和存取管理 (CIAM),2024-2029
 到 2030 年的消費者識別及存取管理市場預測:按組件、部署類型、身份驗證類型、組織規模、最終用戶和區域進行的全球分析
 消費者取向ID與訪問管理市場,規模,趨勢,產業分析報告:各零件,各部署,各認證方法,各業界,各地區 - 市場預測 2025年~2034年