


 |
市場調查報告書
商品編碼
2124610
歐洲收縮彈力套筒標籤:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Europe Shrink And Stretch Sleeve Label - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,歐洲收縮和彈力套筒標籤市場規模預計將在 2025 年達到 17.7 億美元,2026 年達到 18.4 億美元,到 2031 年達到 22.9 億美元,2026 年至 2031 年的複合年成長率為 4.49%。
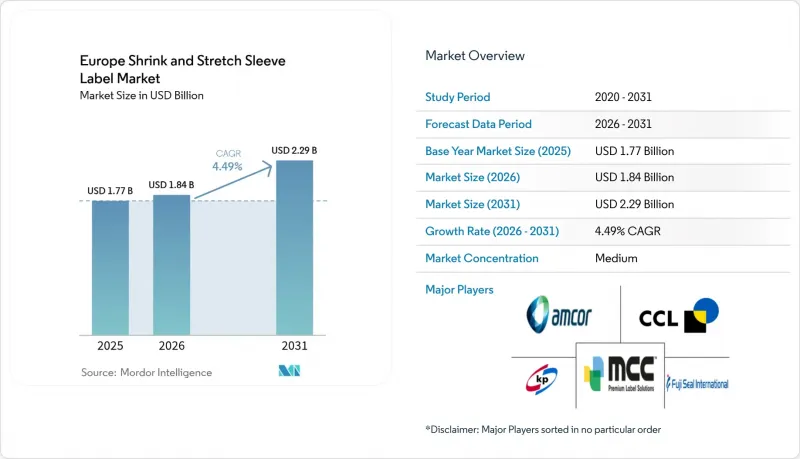
本報告按類型(熱縮套管、拉伸套、全包套管、多包裝/商品搭售套管等)、材料(PVC、PET-G、OPP和OPS、PE、PP等)、應用(食品、飲料、個人護理和化妝品等)、印刷技術(柔版印刷、凹版印刷、數位印刷等)和國家/地區進行細分。市場預測以美元(USD)為單位。
歐洲收縮彈力套筒標籤市場的趨勢和洞察。
商店對提升吸引力的需求增加
眼動追蹤研究表明,64%的歐洲消費者會在三秒鐘內決定選擇哪種飲料,這凸顯了全包覆式標籤套對提升貨架視覺衝擊力的重要性。這種360°全方位展示的標籤讓品牌能夠將鮮豔的圖案、永續性聲明和QR碼促銷活動巧妙融合,而不會破壞視覺流暢性。法國和義大利的高階洗髮精製造商正計劃在2025年前將紙質標籤過渡到熱縮套,從而為多語言文字和高階工藝騰出空間。同年,巴黎水(Perrier)的全像限量版在法國大賣場的衝動性購買量提升了17%。像Lidl這樣的自有品牌連鎖店正透過使用低成本的柔版印刷套套來融入這些高階元素,加劇了爭奪消費者注意力的競爭。隨著電商平台更青睞360°全方位展示效果優異的產品,品牌擁有者也開始將標籤套視為一項投資,而非僅將其視為成本支出,以提升轉換率與顧客忠誠度。
防篡改功能的必要性
歐盟食品接觸法規將於2027年實施,屆時液態乳製品和嬰幼兒營養補充劑的包裝上必須帶有檢驗的完整性密封。帶有易撕線的收縮膜套標無需二次重疊包裝即可滿足此要求。繼2024年發生甲醇中毒事件後,東歐的釀酒廠已根據波蘭和斯洛伐克的新安全法規,為酒精濃度超過20%的烈酒採用帶有易撕線的全包覆式收縮膜套標。德國和荷蘭的藥品包裝製造商目前正使用符合歐盟追蹤溯源法規的編碼收縮膜套標標來包裝臨床試驗管瓶。 Hootamäki公司用於無菌果汁的ISO 16495認證收縮膜套標將於2025年底在西班牙上市,該套標標將防篡改和兒童安全鎖功能整合於一體,堪稱典範。隨著監管機構對完整性要求的日益嚴格,防篡改收縮膜套標正從附加功能轉變為基本要求。
歐盟的塑膠包裝廢棄物指令更加嚴格了。
德國修訂後的《包裝法》(VerpackG)對厚度超過40微米或使用肉眼無法察覺的油墨印刷的包裝套管引入了分級生產者責任(EPR)費用,導致自2026年1月起單價上漲0.05至0.12歐元。歐盟的法案草案提案到2028年強制要求PET-G包裝套管的再生材料含量達到30%,但目前高黏度rPET的供應不足。圍繞「實際可回收」指標的不確定性阻礙了加工商的投資,而南歐的小規模企業則面臨著因投資單一材料生產線資本密集而被迫退出市場的風險。
細分市場分析
2025年,熱縮套標在歐洲收縮和彈力套筒標籤市場佔58.32%的佔有率。這反映了其與複雜瓶型的兼容性以及高速隧道式加工的優勢。由於德國和荷蘭已對阻礙瓶子回收的標籤實施處罰,預計到2031年,拉伸套市場將以每年5.65%的速度成長。這推動了對易於剝離且無需黏合劑的套標的需求。 2025年,Sleever International推出了拉伸複合機,縮小了與熱縮隧道式加工系統的速度差距。全包收縮套標繼續用於高階烈酒和化妝品,而多包裝商品搭售標仍然是碳酸飲料的主要包裝形式。
拉伸套。對於企業而言,這可以減少清洗過程中的瑕疵產品,並提高rPET的純度。另一方面,熱縮套管仍保持著材料成本優勢,每件成本為0.02-0.04歐元,而拉伸套的成本為0.05-0.07歐元。然而,隨著押金返還計畫(DRS)的處罰日益加大,品牌所有者越來越將拉伸套成本的增加視為確保合規的保障。回收費用和生產線速度優勢之間的相互作用意味著這兩種包裝形式都將繼續發揮重要作用,而其採用情況將取決於監管的嚴格程度和價格敏感度。
PET-G 具有無與倫比的透明度和均勻的收縮率,預計到 2025 年將佔據 46.23% 的市場佔有率。然而,由於其易於透過浮選和沈澱分離,且 EPR 費用較低,歐洲聚乙烯薄膜收縮和彈力套筒標籤市場正以 5.83% 的速度成長。 Klockner Pentaplast 於 2025 年推出的 35% rPET 薄膜將幫助品牌所有者履行其使用再生材料的承諾。雖然 OPP 和 OPS 在需要剛性的套標商品搭售應用中仍然發揮著重要作用,但它們的可回收性不足使其面臨其他競爭壓力。
陶氏化學的「親和性」彈性體使聚乙烯薄膜的收縮率高達60%,同時保持與PET-G相當的光澤度。斯堪地那維亞國家的禁令正在加速PVC退出市場,使其應用範圍僅限於特殊用途。聚丙烯目前正應用於熱填充飲料產業,該產業對較高的收縮溫度要求不高。預計到2027年,聚烯將在乳製品和飲用水產業取代PET-G,但PET-G在對光澤度要求較高的高階、圖案豐富的SKU中仍可能保持強勁勢頭。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對提升展示吸引力的需求
- 對防篡改功能的需求
- 過渡到 360° 品牌推廣表面
- 採用可回收聚烯收縮膜
- 線上數位印刷整合
- 鋰金屬摻雜油墨可製造超薄套管。
- 市場限制因素
- 歐盟關於塑膠和包裝廢棄物的指令日益嚴格。
- 原生PET-G和PVC樹脂價格上漲
- 多層薄膜的回收管道有限。
- 由於套幣移除問題,歐盟的押金返還系統存在瓶頸。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按類型
- 熱縮套管
- 拉伸套
- 全身袖
- 多包裝/商品搭售包裝套
- 其他類型
- 材料
- 聚氯乙烯(PVC)
- 乙二醇改質聚對苯二甲酸乙二醇酯(PET-G)
- OPP(定向聚丙烯)和 OPS(定向聚苯乙烯)
- 聚乙烯(PE)
- 聚丙烯(PP)
- 其他材料
- 透過使用
- 食物
- 飲料
- 個人護理化妝品
- 其他用途
- 透過印刷技術
- 柔版印刷
- 凹版印刷
- 數位印刷
- 其他印刷技術
- 國家
- 德國
- 法國
- 英國
- 義大利
- 波蘭
- 荷蘭
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- CCL Industries Inc.
- Klockner Pentaplast GmbH and Co. KG
- Fuji Seal International Inc.
- Huhtamaki Oyj
- Smurfit WestRock
- Mondi plc
- Multi-Color Corporation
- Sleevezone Ltd.
- Folienprint Risse Etiketten GmbH
- Oerlemans Plastics BV
- Decomatic SA
- Polifilm Extrusion GmbH
- Maca Srl
- Sleever International Company
- Derprosa Films SLU
- Dow Chemical Company
- UPM Raflatac Oy
- Constantia Flexibles Group GmbH
- Avery Dennison Corporation
- Coveris Holdings SA
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe shrink and stretch sleeve label market size is projected to be USD 1.77 billion in 2025, USD 1.84 billion in 2026, and reach USD 2.29 billion by 2031, growing at a CAGR of 4.49% from 2026 to 2031.
This report is Segmented by Type (Heat Shrink Sleeve, Stretch Sleeve, Full-Body Sleeve, Multi-Pack/Bundling Sleeve, and More), Material (PVC, PET-G, OPP and OPS, PE, PP, and More), Application (Food, Beverages, Personal Care and Cosmetics, and More), Printing Technology (Flexographic, Rotogravure, Digital, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Shrink And Stretch Sleeve Label Market Trends and Insights
Demand to Increase On-Shelf Appeal
Eye-tracking research shows that 64% of European shoppers decide within three seconds which beverage to pick, underscoring how full-body sleeves elevate shelf impact. The label's 360° canvas lets brands combine vivid graphics, sustainability claims, and QR-enabled promotions without disrupting visual flow. Luxury shampoo makers in France and Italy transitioned from paper labels to heat-shrink sleeves in 2025, unlocking room for multilingual text and premium finishes. Perrier's holographic limited edition boosted impulse sales by 17% in French hypermarkets the same year. Private-label chains such as Lidl mimic these premium cues with low-cost flexo-printed sleeves, intensifying competition for consumer attention. As e-commerce platforms favor products that photograph well in 360°, brand owners continue to treat sleeves as an investment in conversion and loyalty rather than a mere cost line.
Need for Tamper-Evident Protection
EU food-contact rules coming into force by 2027 oblige liquid dairy and infant-nutrition packs to display verifiable integrity seals. Shrink sleeves with perforated tear bands meet that need without secondary over-wraps. After a 2024 methanol poisoning incident, Eastern European distilleries adopted full-body sleeves with tear strips in spirits above 20% alcohol, following new safety decrees in Poland and Slovakia. Pharmaceutical packers in Germany and the Netherlands now wrap clinical-trial vials in coded sleeves that align with EU track-and-trace law. Huhtamaki's ISO-16495-certified sleeve for aseptic juice, launched in Spain in late 2025, shows how tamper evidence and child resistance converge in a single construction. As regulators tighten integrity demands, tamper-evident sleeves shift from value-add to baseline expectation.
Stricter EU Plastics-Packaging Waste Directives
Germany's VerpackG amendment introduces a tiered EPR fee on sleeves thicker than 40 microns or printed with non-detectable inks, raising unit costs by EUR 0.05-0.12 from January 2026. A draft EU act floats a 30% recycled-content mandate for PET-G sleeves by 2028, yet the current high-intrinsic-viscosity rPET supply is insufficient. Uncertainty over "recyclable in practice" metrics stalls converter investment, while small Southern European firms risk exit because funding mono-material lines is capital-intensive.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward 360° Branding Surfaces
- Adoption of Recyclable Polyolefin Shrink Films
- Rising Prices of Virgin PET-G and PVC Resins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Heat-shrink sleeves commanded 58.32% share of the Europe shrink and stretch sleeve label market in 2025, reflecting their compatibility with complex bottle shapes and high-speed tunnels. Stretch equivalents are forecast to expand at 5.65% to 2031 as Germany and the Netherlands penalize labels that hinder bottle recycling, making peelable, adhesive-free sleeves attractive. In 2025 Sleever International installed a stretch applicator rated at 36,000 bottles per hour, closing the speed gap with heat-tunnel systems. Full-body shrink formats continue to serve premium spirits and cosmetics, while multi-pack bundling sleeves remain mainstream in carbonated sodas.
Deposit-return economics amplify stretch demand; operators incur fewer wash-cycle rejects and score higher rPET purity. Conversely, heat-shrink sleeves retain a material-cost edge, at EUR 0.02-0.04 per unit against EUR 0.05-0.07 for stretch. As DRS penalties intensify, however, brand owners increasingly treat higher stretch-sleeve costs as compliance insurance. The interplay between recyclability fees and line-speed economics will keep both formats relevant, bifurcating adoption by regulatory stringency and price sensitivity.
PET-G delivered unsurpassed clarity and shrink uniformity, securing 46.23% share in 2025. Yet the Europe shrink and stretch sleeve label market size for polyethylene films is rising at 5.83% thanks to float-sink separability and lower EPR fees. Klockner Pentaplast's 35% rPET-content film, launched in 2025, helps brand owners inch toward recycled-content pledges. OPP and OPS stay relevant for bundling sleeves that need rigidity, but their recyclability weaknesses expose them to substitution pressure.
Dow's Affinity elastomers now enable PE films to achieve up to 60% shrink while maintaining gloss comparable to PET-G. PVC's exit accelerates under Scandinavian bans, shrinking its addressable pool to specialty applications. Polypropylene serves hot-fill beverages where high shrink temperature is tolerable. By 2027 polyolefins are likely to overtake PET-G in dairy and water, while PET-G remains entrenched in premium graphic-intensive SKUs that prize optical brilliance.
Complete Report Scope:
- By Type
- Heat Shrink Sleeve
- Stretch Sleeve
- Full-Body Sleeve
- Multi-Pack/Bundling Sleeve
- Other Types
- By Material
- Polyvinyl Chloride (PVC)
- Polyethylene Terephthalate Glycol-Modified (PET-G)
- OPP (Oriented Polypropylene) and OPS (Oriented Polystyrene)
- Polyethylene (PE)
- Polypropylene (PP)
- Other Materials
- By Application
- Food
- Beverages
- Personal Care and Cosmetics
- Other Applications
- By Printing Technology
- Flexographic Printing
- Rotogravure Printing
- Digital Printing
- Others Printing Technologies
- By Country
- Germany
- France
- United Kingdom
- Italy
- Poland
- Netherlands
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Amcor plc
- CCL Industries Inc.
- Klockner Pentaplast GmbH and Co. KG
- Fuji Seal International Inc.
- Huhtamaki Oyj
- Smurfit WestRock
- Mondi plc
- Multi-Color Corporation
- Sleevezone Ltd.
- Folienprint Risse Etiketten GmbH
- Oerlemans Plastics B.V.
- Decomatic S.A.
- Polifilm Extrusion GmbH
- Maca S.r.l.
- Sleever International Company
- Derprosa Films S.L.U.
- Dow Chemical Company
- UPM Raflatac Oy
- Constantia Flexibles Group GmbH
- Avery Dennison Corporation
- Coveris Holdings S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand to Increase On-Shelf Appeal
- 4.2.2 Need for Tamper-Evident Protection
- 4.2.3 Shift Toward 360° Branding Surfaces
- 4.2.4 Adoption of Recyclable Polyolefin Shrink Films
- 4.2.5 Inline Digital Printing Integration
- 4.2.6 Lithium-Metal Additive Inks Enabling Ultra-Thin Sleeves
- 4.3 Market Restraints
- 4.3.1 Stricter EU Plastics-Packaging Waste Directives
- 4.3.2 Rising Prices of Virgin PET-G and PVC Resins
- 4.3.3 Limited Recycling Streams for Multi-Layer Films
- 4.3.4 Sleeve Removal Bottlenecks in EU Deposit-Return Schemes
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Heat Shrink Sleeve
- 5.1.2 Stretch Sleeve
- 5.1.3 Full-Body Sleeve
- 5.1.4 Multi-Pack/Bundling Sleeve
- 5.1.5 Other Types
- 5.2 By Material
- 5.2.1 Polyvinyl Chloride (PVC)
- 5.2.2 Polyethylene Terephthalate Glycol-Modified (PET-G)
- 5.2.3 OPP (Oriented Polypropylene) and OPS (Oriented Polystyrene)
- 5.2.4 Polyethylene (PE)
- 5.2.5 Polypropylene (PP)
- 5.2.6 Other Materials
- 5.3 By Application
- 5.3.1 Food
- 5.3.2 Beverages
- 5.3.3 Personal Care and Cosmetics
- 5.3.4 Other Applications
- 5.4 By Printing Technology
- 5.4.1 Flexographic Printing
- 5.4.2 Rotogravure Printing
- 5.4.3 Digital Printing
- 5.4.4 Others Printing Technologies
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 France
- 5.5.3 United Kingdom
- 5.5.4 Italy
- 5.5.5 Poland
- 5.5.6 Netherlands
- 5.5.7 Spain
- 5.5.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 CCL Industries Inc.
- 6.4.3 Klockner Pentaplast GmbH and Co. KG
- 6.4.4 Fuji Seal International Inc.
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Smurfit WestRock
- 6.4.7 Mondi plc
- 6.4.8 Multi-Color Corporation
- 6.4.9 Sleevezone Ltd.
- 6.4.10 Folienprint Risse Etiketten GmbH
- 6.4.11 Oerlemans Plastics B.V.
- 6.4.12 Decomatic S.A.
- 6.4.13 Polifilm Extrusion GmbH
- 6.4.14 Maca S.r.l.
- 6.4.15 Sleever International Company
- 6.4.16 Derprosa Films S.L.U.
- 6.4.17 Dow Chemical Company
- 6.4.18 UPM Raflatac Oy
- 6.4.19 Constantia Flexibles Group GmbH
- 6.4.20 Avery Dennison Corporation
- 6.4.21 Coveris Holdings S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026-2030年全球收縮套標與彈力套筒標籤市場
 套筒標籤市場(2026 年)
 收縮彈力套筒標籤:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 拉伸套與收縮套筒標籤市場-全球市場預測(2026-2032年)
 套筒標籤市場:按類型、印刷技術、應用、最終用途和地區分類(2026-2034 年)
 熱縮套筒標籤市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034 年預測
 2026年全球拉伸套和收縮套筒標籤市場報告熱縮套筒標籤市場按材料類型、容器類型、印刷技術、厚度範圍和應用分類-2026年至2032年全球預測套筒標籤市場:2025-2030 年預測筆記型電腦內膽包市場:按材料、尺寸、保護類型、閉合類型、價格分佈、分銷管道和最終用戶 - 2025-2030 年全球預測