


 |
市場調查報告書
商品編碼
2124492
歐洲車隊管理:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Europe Fleet Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
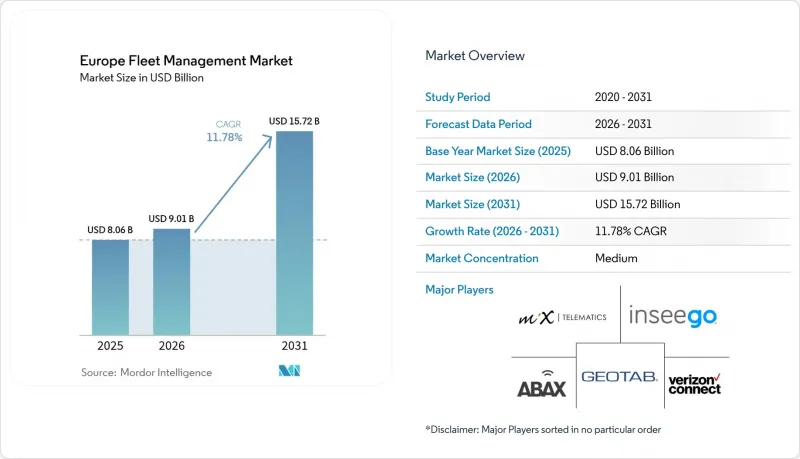
2025 年歐洲車隊管理市場規模為 80.6 億美元,預計到 2031 年將從 2026 年的 90.1 億美元成長至 157.2 億美元,在預測期(2026-2031 年)內複合年成長率為 11.78%。
本報告按部署類型(按需雲端、本地部署)、應用領域(資產管理、資訊管理等)、最終用戶行業(運輸物流、能源公共產業等)、車輛擁有量、車輛類型(輕型商用車、重型商用車等)和地區進行細分。市場預測以美元計價。
歐洲車隊管理趨勢與洞察
隨著歐盟第二階段強制實施智慧行車記錄儀,合規性至關重要。
這項將於2025年6月生效的強制規定,將要求所有重量超過3.5噸的商用車輛持續傳輸位置和行駛時間數據,從定期數據下載轉變為即時監控。 1500歐元至15,000歐元不等的自動收費方案正迫使營運商採用整合式遠端資訊處理系統。一家德國大型物流公司已完成系統部署,以避免服務中斷。供應商表示,小規模車輛所有者擴大要求為多輛車購買訂閱套餐,而不是單獨購買行車記錄器。營運商傾向於使用“單一管理平台”,以便集中管理所有類型的車輛,因此需求正蔓延至小型貨車和公司車隊,從而推動平台部署總量的成長。
電子商務的成長正在加速最後一公里配送的最佳化。
預計到2024年,歐洲線上零售額將佔總銷售額的13.4%,而「最後一公里」配送成本將佔小包裹遞送公司物流總支出的41%。隨著消費者對隔日達的需求日益成長,預計小型貨車的行駛里程將比2024年增加23%。像Seur這樣的公司已經透過實施人工智慧驅動的調度系統,將路線相關成本降低了15%,從而證明了遠端資訊處理技術的實際投資回報。在巴塞隆納、馬德里和巴黎等低排放氣體區,配送時段的限制使情況更加複雜,即時監管資料變得至關重要。因此,歐洲車隊管理正受益於這樣一種局面:電子商務的蓬勃發展和環境法規的壓力,使得對位置、交通狀況和合規性的持續數據需求日益成長。
GDPR合規性為實施過程帶來了複雜性。
根據《一般資料保護規範》(GDPR),員工必須明確同意且可撤銷地使用GPS追蹤功能。此外,2024年德國的多起法院判例確認,全面監控侵犯了員工的權利。對於一家中型汽車擁有公司而言,每年用於法律審查、資料保護官和軟體重新設計的成本可能總合約12.5萬歐元。跨國業者在跨國時,如果遇到監管較嚴格的國家,可能不得不停用諸如駕駛員攝影機視訊串流等功能,這會降低遠端資訊處理技術所承諾的效率,並延長部署週期。
細分市場分析
預計到2025年,雲端服務將佔據歐洲車隊管理市場63.55%的佔有率,並在付費使用制和自動化軟體更新的推動下,以14.56%的複合年成長率持續成長至2031年。德國電信指出,多租戶架構使營運商無需承擔採購和維護伺服器的義務,與本地部署相比,總體擁有成本 (TCO) 降低了34%。對於車隊管理員而言,彈性資料儲存可以應對資料量的季節性波動,而無需手動擴展。雖然一些關鍵基礎設施車隊由於資料主權方面的擔憂而只能使用私有伺服器,但雲端服務供應商已透過提供符合GDPR認證的歐盟資料中心解決了這一問題,從而彌補了合規性方面的不足。
邊緣運算如今不再是雲端模式的替代品,而是其延伸。對時間要求嚴格的駕駛輔助系統所需的計算在車載處理器上完成,而聚合、分析、報告和空中下載更新則透過集中式樞紐進行處理。這種混合方法既滿足了延遲要求,又滿足了管治要求,鞏固了雲端作為歐洲車隊管理市場新部署預設架構的地位。
到2025年,資產管理將佔歐洲車隊管理市場的26.72%。這主要歸功於所有營運商對位置和使用數據日益成長的重視。同時,隨著監管機構和保險公司將經濟獎勵與預防事故掛鉤,安全和合規工具正以14.34%的複合年成長率快速成長。安聯保險為那些能夠主動監控駕駛員的車輛提供高達15%的保費折扣,這加速了高里程宅配服務對相關技術的採用。歐盟的「零願景」(Vision Zero)計畫旨在到2050年實現道路零死亡,該計畫已將人工智慧驅動的疲勞檢測和盲點警告作為多個成員國運營許可證的強制性要求。供應商現在提供安全儀錶板和行車記錄器文件套裝,以確保無縫且檢驗的合規報告。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐盟強制實施智慧行車記錄器第二階段(2025年)
- 電子商務正在推動輕型商用車行駛里程的激增。
- 行動電話和物聯網費用的下降以及eSIM的普及
- 利用OEM開放API實現車載資訊服務的商業化
- 歐盟排放交易體系2(EU ETS-2)低二氧化碳排放車輛積分
- 利用 5G C-V2X 進行微孔板展示實驗
- 市場限制因素
- GDPR 和 ePrivacy 合規負擔
- 人工智慧視訊遠端資訊處理技術的高額資本投入
- 低排放氣體城區隨意建立
- 遠端資訊處理晶片供應中斷
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依部署類型
- 按需(雲端)
- 現場
- 透過使用
- 資產管理
- 資訊管理
- 駕駛員管理
- 安全與合規管理
- 風險管理
- 營運管理
- 按最終用戶行業分類
- 運輸/物流
- 能源公用事業
- 建造
- 製造業
- 其他終端用戶產業
- 以擁有單元數量計算
- 小規模(1-50 台)
- 中型(51-250)
- 大規模(251人或以上)
- 車輛類型
- 輕型商用車
- 大型商用車輛
- 巴士和長途汽車
- 按地區(國家)
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TomTom NV(WEBFLEET)
- Verizon Communications Inc.(Verizon Connect)
- Bridgestone Mobility Solutions BV(WEBFLEET)
- Masternaut Ltd.(MICHELIN Connected Fleet)
- Geotab Inc.
- MiX Telematics Ltd.
- Trimble Inc.
- Samsara Inc.
- Powerfleet Inc.(incl. Fleet Complete)
- ABAX Group AS
- Teletrac Navman(Vontier Corp.)
- AT&T Inc.
- Chevin Fleet Solutions Ltd.
- Gurtam(Wialon)
- Avrios International AG
- Mapon SIA
- Fleetster GmbH
- Shiftmove GmbH
- Transpoco Telematics Ltd.
- Fleetio(RareStep Inc.)
- Teltonika Telematics UAB
- Ruptela UAB
- Motive Technologies Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe fleet management market size was valued at USD 8.06 billion in 2025 and estimated to grow from USD 9.01 billion in 2026 to reach USD 15.72 billion by 2031, at a CAGR of 11.78% during the forecast period (2026-2031).
This report is Segmented by Deployment Type (On-Demand Cloud, On-Premises), Application (Asset Management, Information Management, and More), End-User Vertical (Transportation and Logistics, Energy and Utilities, and More), Fleet Size, Vehicle Type (Light Commercial Vehicles, Heavy Commercial Vehicles, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe Fleet Management Market Trends and Insights
EU Smart-Tachograph Phase II Mandate Creates Compliance Imperative
The mandate enforced from June 2025 forces every commercial vehicle above 3.5 t to transmit location and driver-hours data continuously, replacing periodic data downloads with real-time oversight. Automatic fines structured between EUR 1,500 and EUR 15,000 leave operators' little choice but to install integrated telematics suites. Large German logistics firms have already completed rollouts to avoid service disruption, and suppliers report that small fleets now request multi-vehicle subscriptions rather than standalone tachographs. Because operators prefer a single pane of glass across all classes of vehicles, demand is spilling into light vans and company-car pools, lifting total platform adoption.
E-Commerce Growth Intensifies Last-Mile Delivery Optimization
Online retail penetration climbed to 13.4% of European sales in 2024, and last-mile costs swallow 41% of logistics spend for parcel operators. Light vans now cover 23% more mileage than in 2024 as consumers expect next-day delivery. Operators such as Seur cut route-related costs by 15% after introducing AI-based scheduling, demonstrating tangible return on telematics. Low-emission zones in Barcelona, Madrid, and Paris add further complexity by restricting time-window access, making real-time regulatory data essential. The Europe fleet management market, therefore benefits from converging e-commerce and environmental pressures that require constant location, traffic, and compliance feeds.
GDPR Compliance Creates Implementation Complexity
Under GDPR, employee consent for GPS tracking must be explicit and revocable, and several German court cases in 2024 confirmed that blanket monitoring infringes worker rights. For medium fleets, annual spending on legal review, data-protection officers, and software redesign totals about EUR 125,000. Multinational operators must sometimes deactivate features such as driver-cam streaming when crossing borders with stricter rules, diluting the efficiency promise of telematics and extending deployment timelines.
Other drivers and restraints analyzed in the detailed report include:
- Cellular-IoT Cost Reductions Enable Mass-Market Adoption
- OEM Telematics Platforms Monetize Connected Vehicle Data
- AI Video Telematics Capital Requirements Limit SME Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud services captured 63.55% of Europe fleet management market share in 2025 and are climbing at a 14.56% CAGR through 2031, propelled by pay-as-you-go pricing and automatic software updates. Deutsche Telekom observes that a multi-tenant architecture trims total cost of ownership by 34% relative to on-premises hosting because operators avoid server procurement and maintenance obligations. For fleet managers, elastic data storage accommodates seasonal volume swings without manual scaling. Data-sovereignty concerns confined some critical infrastructure fleets to private servers, yet cloud providers have responded with EU-based data centers that carry GDPR certification, closing the compliance gap.
Edge computing now operates as an extension of the cloud model rather than a replacement. Time-sensitive driver-assistance calculations run on in-vehicle processors, while aggregate analysis, reporting, and over-the-air updates flow through centralized hubs. This hybrid approach satisfies both latency and governance requirements, cementing cloud as the default architecture for new deployments within the Europe fleet management market.
Asset management held 26.72% of Europe fleet management market size in 2025 because every operator values location and utilization data. Safety and compliance tools, however, are advancing at a 14.34% CAGR because regulators and insurers tie monetary incentives to incident prevention. Allianz provides up to 15% premium discounts when fleets demonstrate proactive driver monitoring, accelerating adoption among high-mileage courier services. The EU Vision Zero program, which aims for zero road fatalities by 2050, positions AI-enabled fatigue detection and blind-spot alerts as pre-requisites for operating licenses in several member states. Vendors now bundle safety dashboards with tachograph files, ensuring compliance submissions are seamless and verifiable.
Complete Report Scope:
- By Deployment Type
- On-Demand (Cloud)
- On-Premises
- By Application
- Asset Management
- Information Management
- Driver Management
- Safety and Compliance Management
- Risk Management
- Operations Management
- By End-user Vertical
- Transportation and Logistics
- Energy and Utilities
- Construction
- Manufacturing
- Other End-Users Verticals
- By Fleet Size
- Small (1-50 vehicles)
- Medium (51-250)
- Large (251 +)
- By Vehicle Type
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Bus and Coach
- By Geography (Country)
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
List of Companies Covered in this Report:
- TomTom N.V. (WEBFLEET)
- Verizon Communications Inc. (Verizon Connect)
- Bridgestone Mobility Solutions B.V. (WEBFLEET)
- Masternaut Ltd. (MICHELIN Connected Fleet)
- Geotab Inc.
- MiX Telematics Ltd.
- Trimble Inc.
- Samsara Inc.
- Powerfleet Inc. (incl. Fleet Complete)
- ABAX Group AS
- Teletrac Navman (Vontier Corp.)
- AT&T Inc.
- Chevin Fleet Solutions Ltd.
- Gurtam ( Wialon )
- Avrios International AG
- Mapon SIA
- Fleetster GmbH
- Shiftmove GmbH
- Transpoco Telematics Ltd.
- Fleetio ( RareStep Inc. )
- Teltonika Telematics UAB
- Ruptela UAB
- Motive Technologies Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU smart-tachograph Phase II mandate (2025)
- 4.2.2 E-commerce-driven LCV mileage surge
- 4.2.3 Falling cellular-IoT tariffs and eSIM adoption
- 4.2.4 OEM open-API telematics monetisation
- 4.2.5 EU ETS-2 credits for low-CO? fleets
- 4.2.6 5G C-V2X micro-platooning pilots
- 4.3 Market Restraints
- 4.3.1 GDPR and ePrivacy compliance burden
- 4.3.2 High cap-ex for AI video telematics
- 4.3.3 Patchwork low-emission city zones
- 4.3.4 Telematics-chip supply disruptions
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 On-Demand (Cloud)
- 5.1.2 On-Premises
- 5.2 By Application
- 5.2.1 Asset Management
- 5.2.2 Information Management
- 5.2.3 Driver Management
- 5.2.4 Safety and Compliance Management
- 5.2.5 Risk Management
- 5.2.6 Operations Management
- 5.3 By End-user Vertical
- 5.3.1 Transportation and Logistics
- 5.3.2 Energy and Utilities
- 5.3.3 Construction
- 5.3.4 Manufacturing
- 5.3.5 Other End-Users Verticals
- 5.4 By Fleet Size
- 5.4.1 Small (1-50 vehicles)
- 5.4.2 Medium (51-250)
- 5.4.3 Large (251 +)
- 5.5 By Vehicle Type
- 5.5.1 Light Commercial Vehicles
- 5.5.2 Heavy Commercial Vehicles
- 5.5.3 Bus and Coach
- 5.6 By Geography (Country)
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Spain
- 5.6.5 Italy
- 5.6.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level overview, market-level overview, core segments, financials, strategic information, market rank/share, products and services, recent developments)
- 6.4.1 TomTom N.V. (WEBFLEET)
- 6.4.2 Verizon Communications Inc. (Verizon Connect)
- 6.4.3 Bridgestone Mobility Solutions B.V. (WEBFLEET)
- 6.4.4 Masternaut Ltd. (MICHELIN Connected Fleet)
- 6.4.5 Geotab Inc.
- 6.4.6 MiX Telematics Ltd.
- 6.4.7 Trimble Inc.
- 6.4.8 Samsara Inc.
- 6.4.9 Powerfleet Inc. (incl. Fleet Complete)
- 6.4.10 ABAX Group AS
- 6.4.11 Teletrac Navman (Vontier Corp.)
- 6.4.12 AT&T Inc.
- 6.4.13 Chevin Fleet Solutions Ltd.
- 6.4.14 Gurtam ( Wialon )
- 6.4.15 Avrios International AG
- 6.4.16 Mapon SIA
- 6.4.17 Fleetster GmbH
- 6.4.18 Shiftmove GmbH
- 6.4.19 Transpoco Telematics Ltd.
- 6.4.20 Fleetio ( RareStep Inc. )
- 6.4.21 Teltonika Telematics UAB
- 6.4.22 Ruptela UAB
- 6.4.23 Motive Technologies Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026年全球車隊管理系統市場報告
 中東車隊管理市場(第一版)
 北美車隊管理解決方案:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 自動駕駛車隊管理市場預測至2034年-按自動駕駛等級、車隊能力、部署模式、車輛類別、最終用戶和地區分類的全球分析車隊管理市場預測至2034年—全球解決方案、車隊類型、車輛類型、部署模式、通訊技術、應用程式、最終用戶、銷售管道和區域分析
 乘用車車隊管理市場:全球市場預測,2026-2032年
 施工機械車隊管理軟體市場機會、成長要素、產業趨勢分析及2026-2035年預測
 2026-2034年全球重型車輛車隊維修服務市場規模、佔有率、趨勢與成長分析報告
 全球車隊管理市場(至 2032 年):按解決方案(車隊管理、車輛維護與診斷、性能管理、車輛分析與報告)和車隊類型(客運計程車、商用車輛、公共交通)分類車隊管理解決方案市場預測至2034年-全球分析(按組件、部署模式、車隊類型、車輛類型、功能、最終用戶和地區分類)