


 |
市場調查報告書
商品編碼
2124456
印度雷射市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)India Laser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
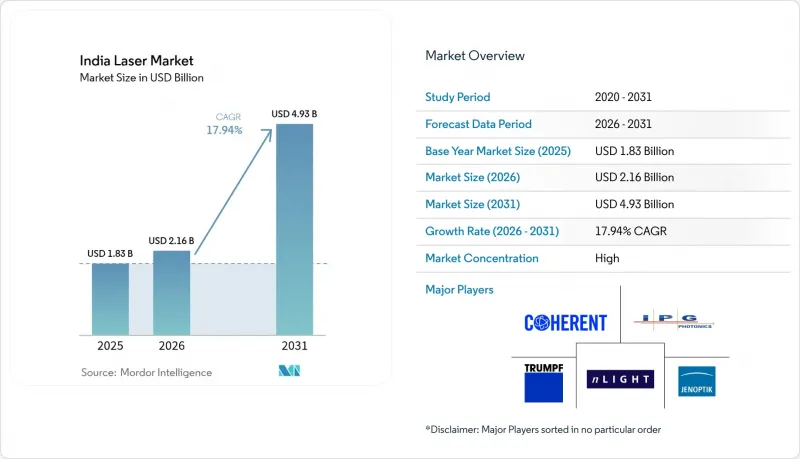
根據 Mordor Intelligence 預測,印度雷射市場規模將從 2025 年的 18.3 億美元和 2026 年的 21.6 億美元成長到 2031 年的 49.3 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 17.94%。
本報告按雷射類型(光纖雷射、固體、二氧化碳雷射、二極體雷射、準分子雷射等)、功率輸出(低功率、中功率、高功率)、應用領域(材料加工、通訊等)以及終端用戶產業(汽車、航太與國防、電子與半導體、醫療等)分類。市場預測以美元(USD)計價。
印度雷射市場趨勢與洞察
政府對半導體製造廠的支持措施
在「印度半導體計畫」政策支持下,已批准興建10座晶圓廠,總投資16億盧比(約192億美元)。每座晶圓廠都配備了雷射切割、打標和劃線設備,這些設備需要以亞微米級精度運作。 「出口促進資本資本財」計畫下的免稅進口使擁有成本降低了18%至22%,縮短了高運轉率光纖平台的投資回收期。僅美光位於薩南德的工廠一旦投入運營,就需要數十個雷射檢測和打標站。預計到2030年,整個晶圓廠的建造將使雷射器的安裝數量增加15倍,從而確保對服務和耗材的長期需求。
電動車和電池生產線的快速擴張
耗資1,810億盧比(約22億美元)的先進化學電池(PLI)計畫正在打造一條年產能達50吉瓦時的電池生產線,而雷射焊接技術適用於鋁銅的連接。與點焊相比,雷射焊接可將接頭電阻降低18%。總理電動驅動計畫(PM E-DRIVE)的補貼正在支持160萬輛電動二輪車和50萬輛電動三輪車的生產,每個電池組均採用雷射縫焊工藝,以滿足AIS-156碰撞安全標準。已採用遠端雷射焊接技術的汽車原始設備製造商(OEM)證實,與電阻焊接相比,頂縫焊接週期縮短了30%。因此,隨著生產線密度的增加,對高功率的需求正從等離子切割機轉向多千瓦級連續波光纖雷射設備。
高功率光纖雷射需要高額資本投入
幾台售價在15萬至40萬美元之間的千瓦級設備,給淨利率12%至18%的代工製造商帶來了沉重的財務壓力。租賃方式在印度的企業中應用不到25%(相較之下,德國的比例為60%至70%),迫使買家以9%至11%的利率申請營運資金貸款,導致投資回收期超過四年。再生雷射二手市場的匱乏實際上使支出加倍,再加上採購延遲,預計到2025年,IPG在印度的銷售額將比前一年下降8%。此外,三線城市的中小型企業用戶缺乏應用實驗室,加劇了他們對技術風險的擔憂,並減緩了訂單轉換率。
細分市場分析
預計到2025年,光纖平台將佔銷售額的41.23%,在鈑金切割、電池極耳焊接和PCB打標等領域的適用性尤其顯著。在印度雷射市場,光纖系統的市場規模預計將成長四倍以上。這主要得益於單模光源標準化進程的加速,其電光轉換效率超過40%,這主要得益於製造、電動車生產線和太陽能發電廠的廣泛應用。超快光纖雷射目前仍屬於小眾市場,但其複合年成長率高達19.18%,主要成長動力來自飛秒微加工在醫療設備以及智慧型手機蓋板玻璃透明基板鑽孔技術。固體Nd:YAG雷射和二極體泵浦雷射在珠寶焊接和鐘錶製造領域仍然發揮著重要作用,其地位的維持更依賴於使用者對現有設備的熟悉程度,而非其卓越的性能。 CO2 雷射器仍用於切割壓克力、木材和皮革,但隨著交貨期限越來越短,許多代工製造商正在逐步淘汰雙波長裝置,以簡化維護。
在科研和國防領域,準分子雷射、紫外線雷射和新興的兆赫光源各自發揮獨特的作用。印度太空研究組織(ISRO)於2025年12月競標採購具備諧波產生能力的飛秒雷射系統,這清晰地展現了該國家實驗室在量子光學和高能實驗領域主導的雄心。印度科學與工業研究理事會(CSIR)正在採購用於測量的頻率穩定氦氖雷射器,這表明市場對低功率、高穩定性的桌上型設備有著強勁的需求。雖然染料雷射和自由電子雷射目前仍主要應用於學術領域,但該領域的突破性進展通常會在十年內轉化為商業波長,從而確保創新週期能夠持續推動印度雷射市場的發展,其影響遠超當前的預測期。
功率範圍在 1 至 100 瓦之間的中功率雷射器預計在 2025 年將佔印度市場銷售額的 48.67%,可滿足印度大多數工作場所的常見需求,例如序號雕刻、選擇性焊接和薄金屬板切割。即插即用的風冷系統、220 伏特電壓相容性以及覆蓋全國、48 小時內即可回應的服務網路,使得總停機時間低於 2%,這對中小企業而言是一個至關重要的賣點。功率超過 100 瓦的高功率雷射在印度的市場佔有率正在迅速成長,這與能夠以等離子切割無法企及的速度焊接鋁製電池機殼和 20 毫米厚船用鋼板的多千瓦級焊接單元密切相關。 TRUMPF 位於浦那的工廠於 2025 年 8 月投產,目前已在本地組裝6kW 至 12kW 的盤式和光纖光源,將前置作業時間縮短至 8-10 週,從而消除了 OEM 廠商對運輸不確定性的擔憂。
系統整合商仍然面臨技能缺口。只有十分之三的公司能夠對六軸機器人進行編程,使其達到遠端焊接所需的亞0.1毫米路徑精度,這限制了它們向農村地區擴張的能力。同時,在低功率(亞1瓦)領域,條碼掃描器、智慧型手機深度感測器和對準模組的出貨量仍位居榜首。然而,儘管由於平均售價下降,行動電話組裝業務的出貨量激增,但該領域在印度雷射市場整體中所佔佔有率仍然很小。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 國內電子製造群激增
- 電動車和電池生產線的快速擴張
- 政府對半導體製造廠的優惠待遇
- 雷射積層製造領域新創公司的擴張
- 增加智慧城市專案中基於雷射的LiDAR感測器的採購
- 用於需要雷射劃線的太陽能電池組件生產線的PLI
- 市場限制因素
- 高功率光纖雷射需要高額資本投入
- 盧比兌美元/人民幣匯率波動
- 州際間資本財稅抵減延遲
- 本地高精度光隔離器的供應鏈有限。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 依雷射類型
- 光纖雷射
- 固體雷射(Nd-YAG、DPSS 等)
- 二氧化碳雷射
- 二極體/直接半導體雷射器
- 準分子/紫外線雷射
- 超高速光纖雷射
- 其他類型的雷射器
- 依輸出類型
- 低功率(小於1瓦)
- 中功率(1-100瓦)
- 高功率(超過100瓦)
- 透過使用
- 材料加工(切割、焊接、打標)
- 通訊和光學儲存
- 醫療美容
- 測量和測試設備
- 國防與安全
- 研究與開發
- 家用電子產品
- 其他用途
- 按最終用戶行業分類
- 車
- 航太/國防
- 電子和半導體
- 衛生保健
- 電訊
- 研究機構
- 其他終端用戶產業
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- IPG Photonics Corporation
- Coherent Corp.
- TRUMPF SE+Co. KG
- nLIGHT, Inc.
- Jenoptik AG
- Lumentum Holdings Inc.
- MKS Instruments, Inc.(Spectra-Physics)
- Han's Laser Technology Industry Group Co., Ltd.
- Wuhan Raycus Fiber Laser Technologies Co., Ltd.
- Synrad Inc.(Novanta Inc.)
- SPI Lasers UK Ltd.
- Laserline GmbH
- Maxphotonics Co., Ltd.
- EKSPLA UAB
- EdgeWave GmbH
- Toptica Photonics AG
- Amplitude Laser Group(Amplitude SAS)
- Light Conversion UAB
- Bystronic Laser AG
- Litron Lasers Ltd.
- HUBNER Photonics GmbH
- Epilog Corporation
- Universal Laser Systems, Inc.
- JPT Opto-electronics Co., Ltd.
- IPG Laser India Pvt. Ltd.
- Sahajanand Laser Technology Ltd.(SLTL Group)
- Additive India Tech Pvt. Ltd.
- Laser Technologies Pvt. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the India laser market size is projected to expand from USD 1.83 billion in 2025 and USD 2.16 billion in 2026 to USD 4.93 billion by 2031, registering a CAGR of 17.94% between 2026 and 2031.
This report is Segmented by Laser Type (Fiber, Solid-State, CO2, Diode, Excimer, and More), Power Output (Low-Power, Medium-Power, and High-Power), Application (Material Processing, Communication, and More), End-User Industry (Automotive, Aerospace and Defense, Electronics and Semiconductors, Healthcare, and More). Market Forecasts are Provided in Terms of Value (USD).
India Laser Market Trends and Insights
Government Incentives For Semiconductor Fabs
Policy support under the India Semiconductor Mission approved 10 fabs with INR 1.6 lakh crore (USD 19.2 billion) committed, each embedding laser dicing, marking and scribing tools that must run at sub-micron tolerances. Zero-duty imports under the Export Promotion Capital Goods window cut ownership cost by 18%-22%, compressing payback periods on high-uptime fiber platforms. Micron's Sanand plant alone will require several dozen laser-based inspection and marking stations once operations commence. Collectively, the fab build-out implies a 15-fold scale-up in installed laser base by 2030, locking in long-tail service and consumables demand.
Rapid Adoption of EV And Battery Fabrication Lines
The Advanced Chemistry Cell PLI of INR 18,100 crore (USD 2.2 billion) creates a 50 GWh battery capacity pipeline that favors laser welding for aluminum-to-copper joints, cutting joint resistance by 18% relative to spot welding. Subsidies under the PM E-DRIVE scheme support 1.6 million electric two-wheelers and 0.5 million three-wheelers, each battery pack relying on laser seam welds to meet AIS-156 crash norms. Automotive OEMs adapting remote laser welding have recorded 30 % faster roof-seam cycles versus resistance methods. Growing line densities are therefore shifting high-power demand from plasma cutters to multi-kilowatt continuous-wave fiber units.
High Capex Of High-Power Fiber Lasers
Multi-kilowatt units priced between USD 150,000 and USD 400,000 strain balance sheets of job shops operating on 12%-18% net margins. Lease finance penetration is below 25% versus 60%-70% in Germany, forcing buyers into working-capital loans at 9%-11% interest, stretching paybacks beyond four years. The absence of a secondary market for refurbished lasers doubles the net outlay, while deferred purchases pressured IPG's India revenue to fall 8% year-over-year in 2025. SME adopters in tier-3 cities also lack access to application labs, raising perceived technical risk and slowing order conversion.
Other drivers and restraints analyzed in the detailed report include:
- Surge In Domestic Electronics Manufacturing Clusters
- PLI For Solar Module Lines Requiring Laser Scribing
- Rupee Volatility Vs USD/CNY
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiber platforms dominated 41.23 % of 2025 revenue, underlining their fit for sheet-metal cutting, battery tab welding and PCB marking. The india laser market size for fiber systems is projected to expand by more than four-fold as fabs, EV lines and solar plants race to standardize on single-mode sources with wall-plug efficiencies exceeding 40%. Ultrafast fiber lasers, though just a niche today, are climbing at a 19.18% CAGR on the back of femtosecond micro-machining in medical devices and transparent-substrate drilling for smartphone cover glass. Solid-state Nd-YAG and diode-pumped variants keep resonance in jewelry welding and watchmaking, protected by installed-base familiarity rather than raw performance. CO2 units still cut acrylic, wood and leather, yet many job shops are shedding dual-wavelength setups to streamline maintenance under tighter delivery windows.
In research and defense, excimer, ultraviolet and emerging terahertz sources fill specialized roles. ISRO's December 2025 tender for a harmonics-enabled femtosecond system underscores how national labs are staking claims in quantum optics and high-energy experiments. The Council of Scientific and Industrial Research procured frequency-stabilized helium-neon lasers for metrology, hinting at enduring demand for low-power but ultrastable benches. Dye and free-electron configurations remain academic curiosities, yet breakthroughs here often migrate to commercial wavelengths within a decade, ensuring that innovation cycles continue to refresh the india laser market long after the present forecast horizon.
Medium-power lasers between 1 and 100 watts accounted for 48.67 % of 2025 revenue, covering serial-number marking, selective soldering and thin-metal cutting tasks that populate most Indian workshops. Their plug-and-play air cooling, 220-volt compatibility and 48-hour nationwide service reach keep total downtime below 2 %, a critical selling point for SMEs. The india laser market share for high-power systems above 100 watts is rising fast, tied to multi-kilowatt weld cells that fuse aluminum battery enclosures and 20-millimeter ship-steel blanks at speeds unattainable by plasma. TRUMPF's Pune factory, opened in August 2025, now assembles 6 kW through 12 kW disk and fiber sources locally, slicing lead times to 8-10 weeks and comforting OEMs wary of shipment uncertainty.
System integrators still confront a skills gap. Only three in ten can program six-axis robots to the sub-0.1 mm path accuracy that remote welding demands, limiting provincial roll-outs. Conversely, the low-power tier below 1 watt keeps volume leadership in barcode scanners, smartphone depth sensors and alignment modules. ASP compression, however, means this tier contributes a minor fraction of india laser market size, even as shipment counts explode alongside handset assembly.
Complete Report Scope:
- By Laser Type
- Fiber Laser
- Solid-State Laser (Nd-YAG, DPSS etc.)
- CO2 Laser
- Diode / Direct Semiconductor Laser
- Excimer / UV Laser
- Ultrafast Fiber Laser
- Other Laser Types
- By Power Output
- Low-Power (less than 1 W)
- Medium-Power (1-100 W)
- High-Power (above 100 W)
- By Application
- Material Processing (Cutting, Welding, Marking)
- Communication and Optical Storage
- Medical and Aesthetic
- Instrumentation and Measurement
- Defense and Security
- Research and Development
- Consumer Electronics
- Other Applications
- By End-User Industry
- Automotive
- Aerospace and Defense
- Electronics and Semiconductors
- Healthcare
- Telecommunications
- Research Institutions
- Other End-User Industries
List of Companies Covered in this Report:
- IPG Photonics Corporation
- Coherent Corp.
- TRUMPF SE + Co. KG
- nLIGHT, Inc.
- Jenoptik AG
- Lumentum Holdings Inc.
- MKS Instruments, Inc. (Spectra-Physics)
- Han's Laser Technology Industry Group Co., Ltd.
- Wuhan Raycus Fiber Laser Technologies Co., Ltd.
- Synrad Inc. (Novanta Inc.)
- SPI Lasers UK Ltd.
- Laserline GmbH
- Maxphotonics Co., Ltd.
- EKSPLA UAB
- EdgeWave GmbH
- Toptica Photonics AG
- Amplitude Laser Group (Amplitude SAS)
- Light Conversion UAB
- Bystronic Laser AG
- Litron Lasers Ltd.
- HUBNER Photonics GmbH
- Epilog Corporation
- Universal Laser Systems, Inc.
- JPT Opto-electronics Co., Ltd.
- IPG Laser India Pvt. Ltd.
- Sahajanand Laser Technology Ltd. (SLTL Group)
- Additive India Tech Pvt. Ltd.
- Laser Technologies Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Domestic Electronics Manufacturing Clusters
- 4.2.2 Rapid Adoption of EV and Battery Fabrication Lines
- 4.2.3 Government Incentives for Semiconductor Fabs
- 4.2.4 Expansion of Laser-Based Additive Manufacturing Startups
- 4.2.5 Rising Procurement of Laser-Based LiDAR Sensors by Smart-City Projects
- 4.2.6 PLI for Solar Module Lines Requiring Laser Scribing
- 4.3 Market Restraints
- 4.3.1 High Capex of High-Power Fiber Lasers
- 4.3.2 Rupee Volatility vs USD/CNY
- 4.3.3 Inter-State GST Credit Delays on Capital Machinery
- 4.3.4 Limited Local Supply Chain for High-Precision Optical Isolators
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Laser Type
- 5.1.1 Fiber Laser
- 5.1.2 Solid-State Laser (Nd-YAG, DPSS etc.)
- 5.1.3 CO2 Laser
- 5.1.4 Diode / Direct Semiconductor Laser
- 5.1.5 Excimer / UV Laser
- 5.1.6 Ultrafast Fiber Laser
- 5.1.7 Other Laser Types
- 5.2 By Power Output
- 5.2.1 Low-Power (less than 1 W)
- 5.2.2 Medium-Power (1-100 W)
- 5.2.3 High-Power (above 100 W)
- 5.3 By Application
- 5.3.1 Material Processing (Cutting, Welding, Marking)
- 5.3.2 Communication and Optical Storage
- 5.3.3 Medical and Aesthetic
- 5.3.4 Instrumentation and Measurement
- 5.3.5 Defense and Security
- 5.3.6 Research and Development
- 5.3.7 Consumer Electronics
- 5.3.8 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Aerospace and Defense
- 5.4.3 Electronics and Semiconductors
- 5.4.4 Healthcare
- 5.4.5 Telecommunications
- 5.4.6 Research Institutions
- 5.4.7 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 IPG Photonics Corporation
- 6.4.2 Coherent Corp.
- 6.4.3 TRUMPF SE + Co. KG
- 6.4.4 nLIGHT, Inc.
- 6.4.5 Jenoptik AG
- 6.4.6 Lumentum Holdings Inc.
- 6.4.7 MKS Instruments, Inc. (Spectra-Physics)
- 6.4.8 Han's Laser Technology Industry Group Co., Ltd.
- 6.4.9 Wuhan Raycus Fiber Laser Technologies Co., Ltd.
- 6.4.10 Synrad Inc. (Novanta Inc.)
- 6.4.11 SPI Lasers UK Ltd.
- 6.4.12 Laserline GmbH
- 6.4.13 Maxphotonics Co., Ltd.
- 6.4.14 EKSPLA UAB
- 6.4.15 EdgeWave GmbH
- 6.4.16 Toptica Photonics AG
- 6.4.17 Amplitude Laser Group (Amplitude SAS)
- 6.4.18 Light Conversion UAB
- 6.4.19 Bystronic Laser AG
- 6.4.20 Litron Lasers Ltd.
- 6.4.21 HUBNER Photonics GmbH
- 6.4.22 Epilog Corporation
- 6.4.23 Universal Laser Systems, Inc.
- 6.4.24 JPT Opto-electronics Co., Ltd.
- 6.4.25 IPG Laser India Pvt. Ltd.
- 6.4.26 Sahajanand Laser Technology Ltd. (SLTL Group)
- 6.4.27 Additive India Tech Pvt. Ltd.
- 6.4.28 Laser Technologies Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 2026年全球電池供電神經外科電源系統市場報告
 高功率雷射系統:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 全球戶外旋轉雷射水平儀市場:按傾角、測量範圍、傾角功能、分銷管道、價格範圍、應用和地區分類-預測至2032年
 國防雷射(2026):技術、應用與市場趨勢雷射:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)2026年顱骨牽引手術動力系統全球市場報告
 綠光雷射市場規模、佔有率和成長分析:按產品類型、功率輸出、工作模式、應用、最終用戶和地區分類-2026-2033年產業預測
 中紅外線雷射器市場規模、佔有率和成長分析:按類型、波長範圍、應用、技術、功率輸出和地區分類-2026-2033年產業預測
 可調式雷射光源市場預測至2034年-按技術、類型、波長、應用、最終用戶和地區分類的全球分析2026年全球綠光雷射市場報告