


 |
市場調查報告書
商品編碼
2124126
二氧化矽:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Silica - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
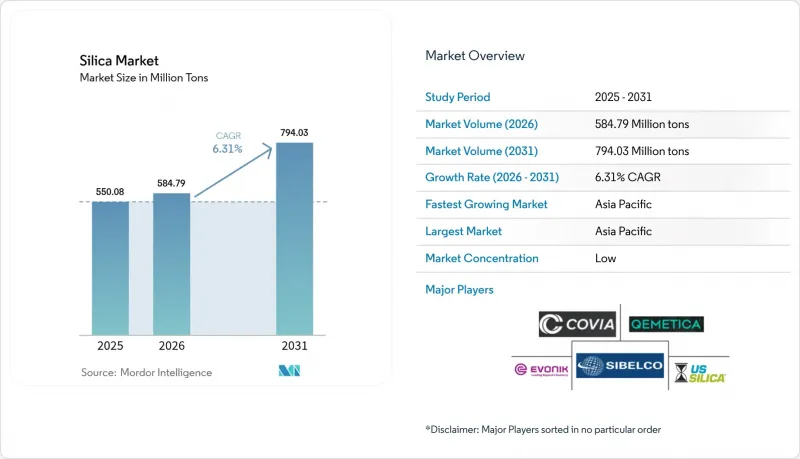
根據 Mordor Intelligence 預測,二氧化矽市場將從 2025 年的 5.5008 億噸成長到 2026 年的 5.8479 億噸,然後在 2031 年達到 7.9403 億噸,2026 年至 2031 年的複合年成長率為 6.31%。
本報告按類型(非晶態(氣相/熱解法和水合物)、晶態(石英、鱗石英和方矽石))、終端用戶行業(建築施工、頁岩油氣、玻璃製造、水處理等)以及地區(亞太地區、北美地區、歐洲地區、南美地區以及中東和非洲地區)進行細分。市場預測以噸為單位。
全球二氧化矽市場趨勢及洞察
節能環保輪胎對沉澱二氧化矽的需求強勁。
低滾動阻力輪胎可提高燃油效率3%至7%,而歐洲強制要求輪胎標註效率標識的法規正在推動胎面配方中二氧化矽含量的增加。目前,高階乘用車輪胎的沉澱二氧化矽含量高達90 phr,是2020年平均值的兩倍。商用車隊也採用類似的配方以降低柴油成本,而電動車製造商則進一步加速這一趨勢,以延長續航里程。
太陽能發電玻璃製造能力的持續擴大
每1吉瓦太陽能發電設備需要1.5萬至2萬噸鐵含量低於120ppm的超白石英玻璃。中國佔全球太陽能玻璃產能的85%以上,為了確保原料質量,中國正將新建的浮法玻璃生產線與自有的石英選礦廠結合。隨著雙面透光面板對純度要求越來越高,對先進選礦技術的投資也不斷增加。
來自鋁矽酸鹽和矽酸鈣填充材的競爭威脅
煅燒黏土和偏高嶺土產品在混凝土和聚合物複合材料中具有與二氧化矽相當的增強效果,同時價格比通用級二氧化矽低25%。供應商正在投資顆粒表面處理技術以縮小性能差距,微粉化鋁矽酸鹽在對成本敏感的建築混合料中的市場佔有率正在擴大。
細分市場分析
到2025年,結晶質級二氧化矽將佔二氧化矽市場的99.15%,到2031年將以6.22%的複合年成長率成長。由於其熱穩定性和成熟的供應鏈,石英在混凝土、玻璃和鑄造模具中仍然至關重要。鱗石英和方矽石在小規模高溫陶瓷領域佔據著一定的市場佔有率,但其複雜的相變加工過程阻礙了規模化生產。非晶級二氧化矽雖然在銷售上佔比不高,但在生胎料、高固態電池漿料和半導體化學機械拋光漿料等領域,其價格更高。專業供應商正在利用親水和疏水錶面處理技術,在單純追求銷售之外創造附加價值。
更嚴格的環境法規正推動原料生產方式從礦山開採的結晶質原料轉向人工合成的非晶質原料,後者可降低吸入性粉塵的風險。生物基稻殼衍生二氧化矽不僅滿足這項要求,還具有許多優勢,例如在其整個生命週期中減少碳排放,以及地理位置接近性亞洲輪胎製造地。對真空閃蒸反應器和低鹼精煉生產線的投資,支持著一種瞄準利潤小規模的細分市場的策略,而非追求通用產品的大規模生產。因此,二氧化矽市場正日益分化,一邊是高純度、特定用途的等級產品,另一邊是用於建築的散裝砂,預計到2030年,兩者的價格差距將進一步擴大。
區域分析
亞太地區是二氧化矽市場的主要驅動力,預計到2025年將佔據41.00%的市場佔有率,並在2031年之前以8.10%的複合年成長率成長。在中國,由於戰略儲備和一體化礦石加工中心,每年建築、太陽能玻璃和化工衍生品等行業的二氧化矽消費量超過2億噸。在印度,高速公路擴建和智慧城市計畫正在提振國內需求,而政府補貼則加速了稻殼衍生二氧化矽產業的發展,為當地輪胎工廠和出口市場提供產品。
北美在頁岩氣丙烷供應中佔據關鍵地位,威斯康辛州、德克薩斯州和亞伯達的礦床符合嚴格的壓裂強度標準。區域加工廠正在縮短向墨西哥灣沿岸玻璃熔爐的供應鏈,而加拿大生產商則正在滿足液化天然氣建設和綠色氫能基礎設施的需求。監管因素,特別是美國職業安全與健康管理局(OSHA)對可吸入二氧化矽的容許濃度限制,正迫使礦商轉向濕式加工和封閉式處理系統,這雖然增加了資本投資,但降低了保險責任。
在歐洲,尤其是在德國、法國和英國,市場對高附加價值產品的需求穩定且強勁。汽車和化學工業的使用者對高純度產品有特定要求,而歐盟的循環經濟指令也大力推廣使用再生材料和生物基材料。東歐供應商,尤其是Qemetica公司擴建其波蘭工廠的供應商,受益於其地理位置優勢,既靠近西歐的原始設備製造商,也靠近土耳其和北非快速成長的建築市場。對節能爐技術和現場太陽能發電設施的投資符合歐盟的脫碳法規,並鞏固了該地區的長期競爭力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究的先決條件
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 節能「綠色」輪胎對沉澱二氧化矽的需求強勁
- 太陽能發電玻璃製造能力的持續擴大
- 在尖端半導體製程擴大高純度二氧化矽的應用。
- 亞洲向生物基稻殼二氧化矽轉型,以減少碳足跡
- 氣相二氧化矽在高固態電池漿料中的快速擴散
- 市場限制因素
- 來自鋁矽酸鹽和矽酸鈣填料的競爭威脅
- 散裝矽砂運輸費率頻繁變動
- 收緊可吸入結晶質二氧化矽的暴露限值(美國職業安全與健康管理局,歐盟)
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 非晶質
- 燻蒸法/熱解法
- 水合型
- 水晶
- 石英
- 鱗石英
- 方矽石
- 非晶質
- 按最終用戶行業分類
- 建築/施工
- 頁岩油氣
- 玻璃製造
- 水處理
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 馬來西亞
- 泰國
- 印尼
- 越南
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐國家
- 土耳其
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 奈及利亞
- 卡達
- 阿拉伯聯合大公國
- 埃及
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AGSCO Corp
- AMS Applied Material Solutions
- Cabot Corporation
- China-Henan Huamei Chemical Co. Ltd
- Covia Holdings LLC
- Denka Company Limited
- Evonik Industries AG
- Heraeus Holding
- Kemitura Group
- Madhu Silica Pvt. Ltd
- Merck KGaA
- Mitsubishi Chemical Group Corporation
- Nouryon
- OCI Company Ltd
- QEMETICA
- Sibelco
- Tokuyama Corporation
- US Silica(Apollo Funds)
- WR Grace and Co.
- Wacker Chemie AG
第7章 市場機會與未來展望
According to Mordor Intelligence, the silica market size is expected to grow from 550.08 Million tons in 2025 to 584.79 Million tons in 2026 and is forecast to reach 794.03 Million tons by 2031 at 6.31% CAGR over 2026-2031.
This report is Segmented by Type (Amorphous (Fumed/Pyrogenic, and Hydrated), Crystalline (Quartz, Tridymite, and Cristobalite)), End-User Industry (Building and Construction, Shale Oil and Gas, Glass Manufacturing, Water Treatment, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Silica Market Trends and Insights
Robust Demand for Precipitated Silica in Energy-Efficient Green Tires
Low-rolling-resistance tires improve fuel economy by 3-7%, and European regulations that mandate tire-efficiency labeling spur higher silica loadings in tread compounds. Premium passenger-car tires now contain up to 90 phr of precipitated silica, double typical 2020 levels. Commercial fleets adopt similar formulations to lower diesel costs, while electric-vehicle makers intensify the trend to extend driving range.
Ongoing Build-Out of Photovoltaic Glass Manufacturing Capacity
Each gigawatt of solar deployment requires 15,000-20,000 tons of ultra-clear silica-based glass with iron content below 120 ppm. China commands over 85% of global PV-glass capacity and is pairing new float-glass lines with captive silica-beneficiation plants to guarantee feedstock quality. Thinner bifacial-panel glass further tightens purity specifications, driving investment in advanced beneficiation.
Competitive Threat from Aluminosilicate and Calcium-Silicate Fillers
Calcined-clay and metakaolin products undercut commodity-grade silica by up to 25% while offering comparable reinforcement in concrete and polymer composites. Suppliers invest in particle-surface treatments that narrow historical performance gaps, with micronized aluminosilicates gaining share in cost-sensitive construction mixes.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of High-Purity Silica in Advanced Semiconductor Nodes
- Shift Toward Bio-Based Rice-Husk Silica in Asia to Cut Carbon Footprint
- Volatility in Freight Cost for Bulk Silica Sand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crystalline grades account for 99.15% of the silica market in 2025 and are expanding at a 6.22% CAGR through 2031. Quartz remains indispensable in concrete, glass, and foundry molds thanks to thermal stability and a well-established supply chain. Tridymite and cristobalite fill smaller high-temperature ceramics niches, but their complex phase-conversion processing limits scale. Amorphous grades, while minor by tonnage, command premium pricing in green-tire compounds, high-solids battery slurries, and semiconductor CMP slurries. Specialty suppliers leverage hydrophilic and hydrophobic surface treatments that capture value beyond bulk tonnage.
Elevated environmental scrutiny encourages migration from mined crystalline inputs toward engineered amorphous forms with lower respirable-dust risk. Bio-based rice-husk silica meets this requirement while offering life-cycle carbon savings and proximity to Asian tire-manufacturing centers. Investment in vacuum flash reactors and low-alkali purification lines underscores the strategy of targeting smaller, higher-margin parcels rather than chasing commodity volume. As a result, the silica market continues bifurcating into high-purity, application-specific grades and bulk construction sand, with pricing divergence expected to widen through 2030.
Complete Report Scope:
- By Type
- Amorphous
- Fumed/Pyrogenic
- Hydrated
- Crystalline
- Quartz
- Tridymite
- Cristobalite
- Amorphous
- By End-user Industry
- Building and Construction
- Shale Oil and Gas
- Glass Manufacturing
- Water Treatment
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordic Countries
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Nigeria
- Qatar
- United Arab Emirates
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominates the silica market with 41.00% share in 2025 and an 8.10% CAGR to 2031. China consumes over 200 million tons annually across construction, photovoltaic glass, and chemical derivatives, underpinned by strategic reserves and integrated beneficiation hubs. India's highway expansion and smart-city programs lift domestic demand, while government subsidies accelerate rice-husk silica ventures that feed both local tire plants and export outlets.
North America holds a pivotal position in shale proppant supply, with Wisconsin, Texas, and Alberta deposits meeting stringent crush-strength specifications. Regional processing plants shorten supply chains for Gulf Coast glass furnaces, while Canadian producers capture demand from LNG construction and green-hydrogen infrastructure. Regulatory drivers, notably OSHA respirable-silica limits, push miners toward wet-processing and enclosed-handling systems that boost capex but lower insurance liabilities.
Europe presents stable, value-added demand centered on Germany, France, and the United Kingdom. Automotive and chemical users specify high-purity grades, and EU circular-economy directives promote recycled and bio-based inputs. Eastern European suppliers, led by Qemetica's expanded Polish site, benefit from proximity to both Western OEMs and growing Turkish and North African construction markets. Investments in energy-efficient kiln technology and on-site solar arrays align with EU decarbonization rules, anchoring long-term regional competitiveness.
- AGSCO Corp
- AMS Applied Material Solutions
- Cabot Corporation
- China-Henan Huamei Chemical Co. Ltd
- Covia Holdings LLC
- Denka Company Limited
- Evonik Industries AG
- Heraeus Holding
- Kemitura Group
- Madhu Silica Pvt. Ltd
- Merck KGaA
- Mitsubishi Chemical Group Corporation
- Nouryon
- OCI Company Ltd
- QEMETICA
- Sibelco
- Tokuyama Corporation
- U.S. Silica (Apollo Funds)
- W.R. Grace and Co.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust demand for precipitated silica in energy-efficient "green" tires
- 4.2.2 Ongoing build-out of photovoltaic glass manufacturing capacity
- 4.2.3 Rising adoption of high-purity silica in advanced semiconductor nodes
- 4.2.4 Shift toward bio-based rice-husk silica in Asia to cut carbon footprint
- 4.2.5 Rapid uptake of fumed silica in high-solids battery slurries
- 4.3 Market Restraints
- 4.3.1 Competitive threat from aluminosilicate and calcium-silicate fillers
- 4.3.2 Volatility in freight cost for bulk silica sand
- 4.3.3 Tightening respirable-crystalline-silica exposure limits (OSHA, EU)
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Type
- 5.1.1 Amorphous
- 5.1.1.1 Fumed/Pyrogenic
- 5.1.1.2 Hydrated
- 5.1.2 Crystalline
- 5.1.2.1 Quartz
- 5.1.2.2 Tridymite
- 5.1.2.3 Cristobalite
- 5.1.1 Amorphous
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Shale Oil and Gas
- 5.2.3 Glass Manufacturing
- 5.2.4 Water Treatment
- 5.2.5 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Malaysia
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Nordic Countries
- 5.3.3.8 Turkey
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Nigeria
- 5.3.5.4 Qatar
- 5.3.5.5 United Arab Emirates
- 5.3.5.6 Egypt
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AGSCO Corp
- 6.4.2 AMS Applied Material Solutions
- 6.4.3 Cabot Corporation
- 6.4.4 China-Henan Huamei Chemical Co. Ltd
- 6.4.5 Covia Holdings LLC
- 6.4.6 Denka Company Limited
- 6.4.7 Evonik Industries AG
- 6.4.8 Heraeus Holding
- 6.4.9 Kemitura Group
- 6.4.10 Madhu Silica Pvt. Ltd
- 6.4.11 Merck KGaA
- 6.4.12 Mitsubishi Chemical Group Corporation
- 6.4.13 Nouryon
- 6.4.14 OCI Company Ltd
- 6.4.15 QEMETICA
- 6.4.16 Sibelco
- 6.4.17 Tokuyama Corporation
- 6.4.18 U.S. Silica (Apollo Funds)
- 6.4.19 W.R. Grace and Co.
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 高純度二氧化矽市場規模:依純度、應用、終端用戶產業、地區及預測分類。全球二氧化矽市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 二氧化矽市場-2026年至2032年全球市場預測二氧化矽粉末市場-2026-2032年全球市場預測
 二氧化矽花:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)農業矽市場規模:依產品類型、形態、應用、地區及預測分類。
 環境二氧化矽市場:依產品類型、應用、最終用途產業、市場規模及地區分類高純度二氧化矽市場:按類型、應用、終端用戶產業和地區分類。全球介孔二氧化矽市場:依產品、應用及地區分類
 球形二氧化矽市場報告:趨勢、預測與競爭分析(至2035年)