


 |
市場調查報告書
商品編碼
2123466
企業金鑰管理(EKM):市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Enterprise Key Management (EKM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
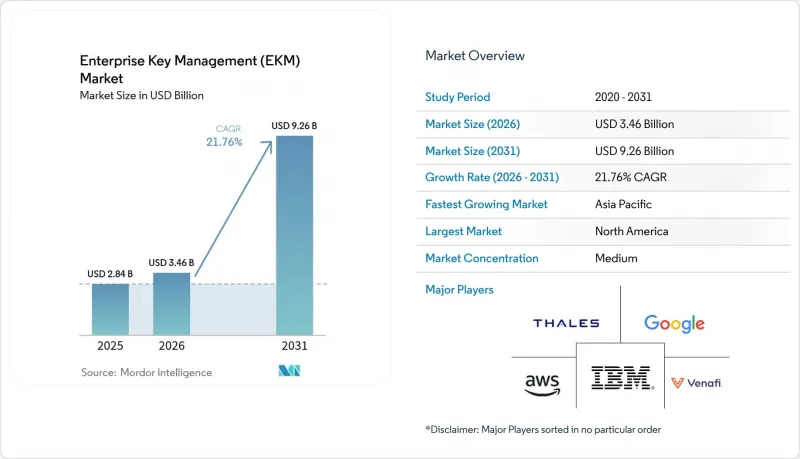
根據 Mordor Intelligence 預測,企業金鑰管理 (EKM) 市場將從 2025 年的 28.4 億美元成長到 2026 年的 34.6 億美元,然後在 2031 年達到 92.6 億美元,2026 年至 2031 年的複合年成長率為 21.76%。
本報告按部署模式(雲端和本地部署)、企業規模(中小企業和大型企業)、應用領域(磁碟加密、文件和文件夾加密等)、最終用戶行業(銀行、金融服務和保險 (BFSI)、醫療保健、政府和國防、IT 和電信、零售以及其他最終用戶行業)和地區進行細分。市場預測以美元 (USD) 為單位。
全球企業金鑰管理 (EKM) 市場趨勢與洞察
各行業對資料加密的監管要求日益成長
目前,全球監管機構已將加密視為基本控制措施,而非可選項。 2024年,歐洲資料保護委員會 (EDPB) 共處以16億美元的罰款,其中43%的罰款是由於加密管理不善造成的。同時,HIPAA雲端指南的更新以及PCI-DSS和SOX等金融法規的重疊要求也加劇了這一趨勢,這些法規均要求實現可驗證的金鑰分離。因此,跨國公司需要在不同的地區法規下建立統一的金鑰管治,從而加速了能夠將單一控制體系映射到多個審計框架的平台的需求。隨著大型承包商將加密條款納入採購契約,小規模供應商也紛紛加入,擴大了整體買家群體,並進一步增強了市場發展勢頭。
雲端運算和物聯網工作負載導致資料爆炸
2024年,企業資料量年增47%,其中成長最快的是來自物聯網和邊緣部署的非結構化感測器輸出。在這種規模下,基於設備的金鑰儲存已不再實用,因為即使在間歇性連接環境下,數百萬台設備也需要低延遲的身份驗證資訊輪換。每天收集TB級Terabyte資料的製造工廠和實施遠端患者監護系統的醫療保健系統都清楚地表明了這項挑戰的緊迫性。雲端原生金鑰管理服務透過API驅動的可擴充性來應對此負載,使微服務能夠為每個容器執行個體產生臨時金鑰,而無需人工干預。隨著微隔離成為標準,這些服務正成為現代DevSecOps工作流程的重要基礎。
關鍵管理解決方案之間缺乏互通性標準
儘管 PKCS#11 和 KMIP 已經存在,但它們僅涵蓋基本功能,並不適用於雲原生模式和後量子演算法。專有介面將企業限制在單一供應商的技術堆疊中,使遷移策略和多重雲端部署變得複雜。在不同供應商的 HSM 之間遷移金鑰通常需要重新加密數據,這不僅會阻礙敏捷性,還會造成營運障礙,從而推高整體擁有成本。因此,互通性差距會延緩大規模部署,採購團隊在簽署多年合約之前,也越來越要求供應商提供基於開放標準的藍圖。
細分市場分析
到2025年,雲端部署將佔總營收的62.54%,鞏固其在企業金鑰管理市場核心細分領域的地位。隨著買家將演算法敏捷性和彈性擴展性置於硬體更換週期之上,預計到2031年,該細分領域的複合年成長率將達到23.62%。雲端原生服務可無縫整合到DevSecOps工具鏈中,從而加快容器化工作負載從程式碼提交到憑證頒發的速度。金融機構正順應這一趨勢,將即時付款管道遷移到雲端金庫,以確保亞毫秒的密鑰檢索速度。隨著各國央行批准對系統關鍵型金融機構實施雲端管理措施,消除長期存在的監管障礙,這一趨勢正進一步加速發展。
在資料主權和延遲要求等情況下,以硬體為中心的部署仍然至關重要,因為本地金鑰儲存必不可少。然而,即使在這些環境中,混合聯合(將特定金鑰路由到公共雲端HSM 以實現全域容錯移轉)也日益普及。能夠透過統一主機同時支援這兩種模式的供應商更受青睞,因為它們允許企業在保留原有投資的同時,選擇性地進行現代化改造。因此,由混合部署驅動的企業金鑰管理市場規模正在不斷擴大,其中雲端仍然是規模最大且成長最快的細分市場。
到2025年,大型企業將佔據企業金鑰管理市場57.12%的佔有率,反映出其成熟的合規義務和強大的安全團隊。同時,中小企業(SME)正以23.55%的複合年成長率成長,主要得益於供應鏈法規將加密要求向下游延伸。訂閱式收費系統消除了資本支出(CAPEX)的障礙,而託管服務供應商則將監管報告功能打包,以彌補技能缺口。醫療診所就是這一趨勢的一個典型例子,它們採用CloudVault訂閱服務來確保符合HIPAA合規性,而無需聘用內部密碼學家。
監管機構透過對分包主要承包商對中小企業的滲透。這促使一級企業獎勵為小規模合作夥伴提供實施支援計畫。因此,企業金鑰管理市場正吸引著越來越多先前依賴簡易密碼庫的中型企業。提供預先打包合規模板和自動輪換策略的供應商在該領域獲得了廣泛認可。
區域分析
預計到 2025 年,北美將佔總收入的 38.35%,這主要得益於 NIST 在後量子標準領域的主導地位,以及美國聯邦機構早期提供的資金支持,這些機構要求在 2035 年前實現量子防護。加拿大公司正乘著美國創新浪潮的東風,同時調整部署以適應《個人資訊保護和電子文件法》(PIPEDA) 的限制;而在墨西哥,工業復甦正在推動對物聯網密碼管理解決方案的需求,這些解決方案涵蓋了跨境供應鏈中的生產線。
亞太地區正呈現最強勁的成長勢頭,年複合成長率高達22.58%,這得益於各國網路安全政策的逐步落實。中國的《密碼法》規定關鍵基礎設施金鑰必須託管在國內,這不僅促進了國內供應商的發展,也促使西方供應商採用合資模式。在印度,正在推進的《個人資料保護法案》和「數位印度」計畫正在加速金融、保險、證券(BFSI)和醫療保健產業的網路安全應用。同時,日本的「社會5.0」計畫正在加速工廠環境中邊緣HSM叢集的部署。韓國先進的電信基礎設施正在滿足5G邊緣節點對超低延遲金鑰取得的需求。
在歐洲,隨著《一般資料保護規則》(GDPR) 的罰款凸顯了加密措施不足的實際成本,以及即將實施的《人工智慧法案》將加密義務擴展到自動化決策系統,加密技術正逐步擴展。德國的中型企業(Mittelstands)正專注於機器身分管治,而法國的雲端主權理念正在促進本地雲端硬體安全模組(HSM)生態系統的發展。英國正利用脫歐後資料保護體系的監管柔軟性,在金融服務領域試行機密電腦制。這些因素共同促進了區域收入來源的多元化,並對沖了單一市場的波動風險。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 各行各業都在加強對資料加密的監管要求。
- 由於雲端運算和物聯網工作負載,資料量迅速成長
- 資料外洩帶來的成本增加,正在推高董事會層級的安全預算。
- 向混合雲和多重雲端架構的轉變需要集中式金鑰管理。
- 一項旨在為後量子密碼學做好準備的計劃正在出現。
- 硬體安全模組與DevSecOps流水線的整合
- 市場限制因素
- 主要管理解決方案之間缺乏互通性標準
- 網路安全專業人員短缺,尤其是具備加密金鑰管理專業知識的人員。
- 與舊有系統整合的初始階段
- 加密技術的普及管治帶來了挑戰。
- 產業價值鏈分析
- 宏觀經濟因素的影響
- 技術展望
- 監理情勢
- 波特五力分析
- 宏觀經濟因素的影響
- 投資分析
第5章 市場規模與成長預測
- 依部署類型
- 雲
- 現場
- 按公司規模
- 小型企業
- 大公司
- 透過使用
- 磁碟加密
- 文件和資料夾加密
- 資料庫加密
- 通訊加密
- 雲端加密
- 按最終用戶行業分類
- BFSI
- 衛生保健
- 政府/國防
- 資訊科技/通訊
- 零售
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amazon Web Services, Inc.
- Venafi, Inc.
- Thales Group
- Google LLC
- International Business Machines Corporation
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Quantum Corporation
- WinMagic Inc.
- Microsoft Corporation
- Dell Technologies Inc.
- HashiCorp, Inc.
- Micro Focus International plc
- Entrust Corporation
- Fortanix Inc.
- ESCRYPT GmbH
- Keyfactor, Inc.
- nCipher Security, LLC
- HyTrust, Inc.
- CipherCloud, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the enterprise key management market size is expected to grow from USD 2.84 billion in 2025 to USD 3.46 billion in 2026 and is forecast to reach USD 9.26 billion by 2031 at 21.76% CAGR over 2026-2031.
This report is Segmented by Deployment Type (Cloud, and On-Premises), Size of Enterprise (Small- and Medium-Sized Enterprises, and Large Enterprises), Application (Disk Encryption, File and Folder Encryption, and More), End-User Vertical (BFSI, Healthcare, Government and Defense, IT and Telecom, Retail, Other End-User Verticals), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise Key Management (EKM) Market Trends and Insights
Growing Regulatory Mandates for Data Encryption Across Industries
Global regulators now frame encryption as a baseline control, not a discretionary enhancement. In 2024 the European Data Protection Board issued USD 1.6 billion in fines, and 43% cited inadequate encryption controls. Parallel pressure comes from HIPAA cloud guidance updates and overlapping financial directives such as PCI-DSS and SOX that demand demonstrable key segregation. Multinational corporations must therefore orchestrate homogeneous key governance across diverging regional statutes, propelling demand for platforms capable of mapping a single control stack to multiple audit frameworks. Smaller suppliers are swept in as prime contractors embed encryption clauses into procurement contracts, broadening the total purchasing cohort and reinforcing market momentum.
Exponential Data Growth From Cloud and IoT Workloads
Enterprise data volumes climbed 47% year-over-year in 2024, with unstructured sensor output from IoT and edge deployments driving the steepest curve. Such scale renders appliance-based key stores impractical because millions of devices require low-latency credential rotation even in intermittent-connectivity scenarios. Manufacturing plants that now capture terabytes of telemetry daily and healthcare systems deploying remote patient monitors illustrate the urgency. Cloud-native key services counter this strain through API-driven elasticity, enabling microservices to generate short-lived keys per container instance without manual intervention. As micro-segmentation becomes standard, these services emerge as mandatory underpinnings of modern DevSecOps workflows.
Limited Interoperability Standards Among Key Management Solutions
Although PKCS#11 and KMIP exist, they cover baseline functions unsuited for cloud-native patterns and post-quantum algorithms. Proprietary interfaces lock enterprises into single-vendor stacks, complicating exit strategies and multi-cloud rollouts. Migrating keys between provider HSMs often requires data re-encryption, an operational hurdle that curtails agility and inflates cost of ownership. Interoperability gaps consequently decelerate large-scale deployments and inspire procurement teams to insist on open-standard roadmaps before signing multi-year agreements.
Other drivers and restraints analyzed in the detailed report include:
- Rising Cost of Data Breaches Elevating Board-Level Security Budgets
- Shift Toward Hybrid and Multi-Cloud Architectures Requiring Centralized Key Management
- Shortage of Cybersecurity Professionals Skilled in Cryptographic Key Management
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud deployment generated 62.54% of 2025 revenue, cementing its status as the anchor segment within the enterprise key management market. The segment is forecast to record a 23.62% CAGR through 2031 as buyers favor algorithmic agility and elastic scaling over hardware replacement cycles. Cloud-native services integrate seamlessly into DevSecOps toolchains, shortening the interval between code commit and credential issuance for containerized workloads. Financial institutions exemplify adoption momentum by migrating real-time payment platforms to cloud-based vaults that guarantee sub-millisecond key retrieval. The trend intensifies as central banks approve cloud controls for systemically important institutions, removing a longstanding regulatory barrier.
Hardware-centric deployments remain relevant where data sovereignty or latency demands insist on local key custody, yet even these environments increasingly employ hybrid federations that route certain keys to public cloud HSMs for global failover. Vendors that support both patterns within a unified console gain preference because they allow organizations to preserve legacy investments while modernizing selectively. As a result, the enterprise key management market size attributable to hybrid deployments is expanding, although cloud remains both the largest and fastest growing slice.
Large enterprises retained 57.12% of enterprise key management market share in 2025, reflecting their mature compliance obligations and deep security staffing benches. Yet small and medium enterprises are advancing at a 23.55% CAGR, propelled by supply-chain mandates that cascade encryption requirements downstream. Subscription pricing removes capex barriers, while managed service providers bundle regulatory reporting to offset skills shortages. Healthcare clinics illustrate the pattern by adopting cloud-vault subscriptions that ensure HIPAA alignment without hiring in-house cryptographers.
Regulators indirectly accelerate SME penetration by penalizing prime contractors for subcontractor lapses, which incentivizes tier-1 firms to sponsor onboarding programs for smaller partners. Consequently, a growing share of enterprise key management market size now originates from mid-market accounts that historically relied on rudimentary password vaults. Vendors that offer pre-packaged compliance templates and automated rotation policies capture disproportionate mindshare among this cohort.
Complete Report Scope:
- By Deployment Type
- Cloud
- On-Premises
- By Size of Enterprise
- Small- and Medium-sized Enterprises
- Large Enterprises
- By Application
- Disk Encryption
- File and Folder Encryption
- Database Encryption
- Communication Encryption
- Cloud Encryption
- By End-user Vertical
- BFSI
- Healthcare
- Government and Defense
- IT and Telecom
- Retail
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 38.35% of 2025 revenue, anchored by NIST's leadership in post-quantum standards and early budget commitments from U.S. federal agencies that require quantum-safe readiness by 2035. Canadian enterprises piggyback on the U.S. innovation stream while tailoring deployments to PIPEDA privacy constraints, and Mexico's industrial renaissance drives demand for IoT-grade vaults that span factory lines in cross-border supply chains.
Asia Pacific records the briskest trajectory at 22.58% CAGR as sovereign cybersecurity agendas take hold. China's Cryptography Law compels domestic hosting of keys for critical infrastructure, fueling indigenous vendor growth while obligating Western suppliers to establish joint-venture models. India's pending Personal Data Protection Bill and Digital India push prompt BFSI and healthcare rollouts, whereas Japan's Society 5.0 blueprint accelerates factory-floor deployments of edge HSM clusters. South Korea's advanced telecom infrastructure underpins demand for ultra-low-latency key retrieval at 5G edge nodes.
Europe sustains moderate expansion as GDPR fines demonstrate tangible cost for weak encryption and the forthcoming AI Act extends cryptographic duties to automated decision systems. Germany's Mittelstand industrial base focuses on machine identity governance, and France's cloud sovereignty doctrine nurtures local-cloud HSM ecosystems. The United Kingdom, operating under its post-Brexit Data Protection regime, leverages regulatory flexibility to pilot confidential computing constructs in financial services. Collectively, these forces uphold a diversified regional revenue mix and hedge against single-market volatility.
- Amazon Web Services, Inc.
- Venafi, Inc.
- Thales Group
- Google LLC
- International Business Machines Corporation
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Quantum Corporation
- WinMagic Inc.
- Microsoft Corporation
- Dell Technologies Inc.
- HashiCorp, Inc.
- Micro Focus International plc
- Entrust Corporation
- Fortanix Inc.
- ESCRYPT GmbH
- Keyfactor, Inc.
- nCipher Security, LLC
- HyTrust, Inc.
- CipherCloud, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Regulatory Mandates for Data Encryption Across Industries
- 4.2.2 Exponential Data Growth From Cloud and IoT Workloads
- 4.2.3 Rising Cost of Data Breaches Elevating Board-Level Security Budgets
- 4.2.4 Shift Toward Hybrid and Multi-Cloud Architectures Requiring Centralized Key Management
- 4.2.5 Emergence of Post-Quantum Cryptography Readiness Programs
- 4.2.6 Integration of Hardware Security Modules With DevSecOps Pipelines
- 4.3 Market Restraints
- 4.3.1 Limited Interoperability Standards Among Key Management Solutions
- 4.3.2 Shortage of Cybersecurity Professionals Skilled in Cryptographic Key Management
- 4.3.3 High Initial Integration Complexity With Legacy Systems
- 4.3.4 Rising Cryptographic Sprawl Leading to Governance Challenges
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors
- 4.10 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 Cloud
- 5.1.2 On-Premises
- 5.2 By Size of Enterprise
- 5.2.1 Small- and Medium-sized Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Application
- 5.3.1 Disk Encryption
- 5.3.2 File and Folder Encryption
- 5.3.3 Database Encryption
- 5.3.4 Communication Encryption
- 5.3.5 Cloud Encryption
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 Healthcare
- 5.4.3 Government and Defense
- 5.4.4 IT and Telecom
- 5.4.5 Retail
- 5.4.6 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Venafi, Inc.
- 6.4.3 Thales Group
- 6.4.4 Google LLC
- 6.4.5 International Business Machines Corporation
- 6.4.6 Oracle Corporation
- 6.4.7 Hewlett Packard Enterprise Company
- 6.4.8 Quantum Corporation
- 6.4.9 WinMagic Inc.
- 6.4.10 Microsoft Corporation
- 6.4.11 Dell Technologies Inc.
- 6.4.12 HashiCorp, Inc.
- 6.4.13 Micro Focus International plc
- 6.4.14 Entrust Corporation
- 6.4.15 Fortanix Inc.
- 6.4.16 ESCRYPT GmbH
- 6.4.17 Keyfactor, Inc.
- 6.4.18 nCipher Security, LLC
- 6.4.19 HyTrust, Inc.
- 6.4.20 CipherCloud, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

 電子烘乾櫃市場報告:趨勢、預測及競爭分析(至2035年)
 加密金鑰管理服務市場:全球市場預測,2026-2032年
 主權金鑰管理系統軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)企業金鑰管理市場-2026-2032年全球市場預測
 IT管理服務市場:按應用程式、最終用戶和地區分類(2026-2034年)企業金鑰管理市場規模、佔有率、趨勢和預測:按組件、部署類型、企業規模、應用、最終用戶行業和地區分類,2026-2034 年
 2026年全球密鑰管理軟體市場報告KMaaS(金鑰管理即服務)全球市場報告(2026 年)2026年全球企業密鑰管理市場報告電子鎖箱市場按類型、控制機制、材料、功能、應用和銷售管道,全球預測(2026-2032年)