


 |
市場調查報告書
商品編碼
2123295
非製冷紅外線成像:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Uncooled Infrared Imaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,非冷凍紅外線成像市場將從 2025 年的 47.5 億美元成長到 2026 年的 51.4 億美元,然後在 2031 年達到 76.3 億美元,2026 年至 2031 年的複合年成長率為 8.21%。
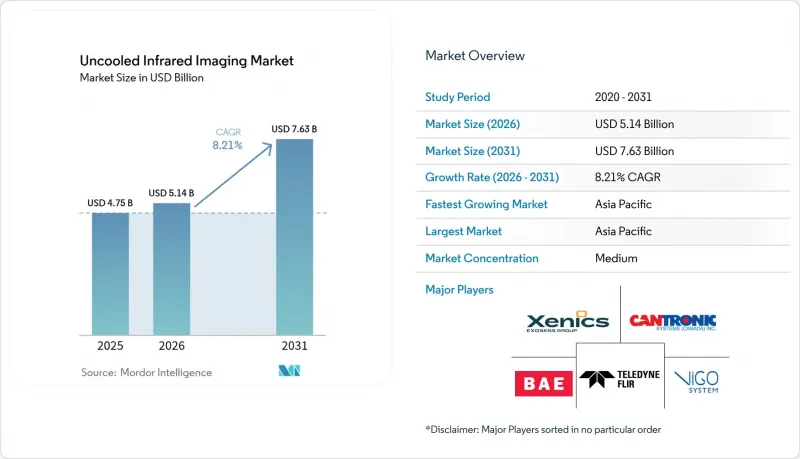
本報告按應用領域(汽車、軍事與國防、工業與製造業及其他)、檢測器技術(氧化釩微測輻射熱計、非晶質及其他)、頻譜頻寬(長波紅外線、中波紅外線及其他)、產品類型(手持式相機、固定式相機及其他)和地區進行細分。市場預測以美元計價。
全球非製冷紅外線成像市場趨勢及洞察
在汽車ADAS和夜視系統中的應用日益廣泛。
隨著美國國家公路交通安全管理局 (NHTSA) 新規生效,強制要求車輛配備具備夜間行人偵測功能的自動緊急煞車系統,熱成像攝影機正從豪華配置轉變為主流安全設備。法雷奧 (Valeo) 和泰萊達因 (Teledyne) 的 FLIR 公司已於 2024 年獲得首個汽車安全完整性等級 B (SIL B) 契約,這表明他們已做好大規模量產的準備。雷達難以在噪音環境中識別生物體,雷射雷達 (LiDAR) 在雨天性能下降,可見光感測器在弱光環境下失效,而熱成像技術則克服了這些挑戰,即使在超過 100 公尺的距離上也能正常工作。分析師預測,微測輻射熱計的年出貨量將從 2024 年的不到 200 萬台成長到 2030 年的超過 1,600 萬台,預計這一成長將使非製冷紅外線成像市場的晶圓成本降至個位數美元水平。麥格納 (Magna) 已在其駕駛輔助系統套件中部署了超過 120 萬套熱成像系統,這表明其已贏得眾多原始設備製造商 (OEM) 的信賴。
工業預測性維護和檢測的需求日益成長
半導體製造廠、化工廠和發電廠的意外運作每小時可能造成超過 5 萬美元的損失,這進一步證明了即時熱成像檢測的商業可行性。使用價格低於 5000 美元的非製冷手持式熱像儀,技術人員每個班次可以掃描數百個設備,並在故障發生前數週識別出熱點。整合到感測器中的邊緣推理模組透過在設備上執行卷積網路分析來克服延遲和頻寬限制。在電動車電池生產線上,熱成像陣列正被用於在失控事件發生之前檢測電池堆疊缺陷,從而保護整個生產批次。此外,ISO 50001 能源效率審核也推動了採購,因為它允許建築管理人員將溫度圖納入維修優先級,從而降低營運成本。
與冷卻式紅外線檢測器相比,性能有其局限性
50–100 mK 的噪音等效溫差限制了其在遠程監視、精確導引飛彈和巡天光譜等領域的應用。在這些領域,仍需使用能夠實現低於 20 mK 性能的冷卻式中波長陣列。對於非冷卻陣列,熱時間常數限制了影格速率約為 60 Hz,遠低於彈道成像所需的千赫茲級速度。因此,冷卻技術仍然是軍用狙擊系統和渦輪機診斷的合約要求,儘管非冷卻陣列具有成本和功耗優勢,但其應用仍然有限。
細分市場分析
受周界安防系統(可減少陰影和車燈造成的誤報)的推動,安防監控產業預計在2025年將佔銷售額的34.10%。相較之下,汽車應用雖然規模較小,但預計到2031年將以10.05%的年均成長率成長,成為所有終端應用中成長最快的領域。這主要得益於美國提案的煞車法規,該法規要求車輛在夜間必須能夠偵測行人、騎乘者和大型動物。這些法規將非製冷紅外線成像市場的成長機會從豪華車品牌擴展到了量產車型平台。
在工業維護領域,開關設備和旋轉機械的熱成像掃描正在推動市場需求;而在家用電子電器領域,售價低於200美元的智慧型手機核心產品正在模糊專業用戶和準專業用戶之間的界限,從而擴大市場。在測繪領域,配備非冷凍攝影機的無人機用於農作物生長和電力線路巡檢,目前仍屬於小眾市場。疫情過後,醫療領域對體溫篩檢的需求已恢復正常,並在醫院和交通樞紐保持穩定。
預計到2025年,氧化釩裝置將佔銷售額的48.60%。這部分歸功於國防預算的持續投入,提高了裝置的靈敏度;但隨著晶圓廠採用標準CMOS設備,非晶質元件的市佔率正以9.62%的複合年成長率成長。非晶質的製程親和性顯著降低了晶片成本,並簡化了與讀出電路的單晶片整合。這對於汽車產業的規模經濟至關重要。由於汽車產量遠超國防需求,氧化釩裝置在非製冷紅外線成像市場的佔有率可能會下降,資本投資將轉向矽基產品線。
熱電堆和熱電陣列在運動偵測領域僅佔個位數的市場佔有率,解析度在該領域並非首要考慮因素。新興的量子點原型預計將在室溫下覆蓋短波長區域,但製造方面的挑戰使其仍主要停留在實驗室階段。 Lynred 於 2024 年 10 月收購 New Imaging Technologies,凸顯了隨著長波長細分市場日趨成熟,供應商尋求利用短波長資產對沖風險的趨勢。
區域分析
預計到2025年,亞太地區將佔全球銷售額的41.10%,到2031年複合年成長率將達到11.29%。由於中國供應商集中了檢測器製造、晶圓加工和相機組裝等環節,這一比例遠高於非製冷紅外線成像市場的平均水平。這種垂直整合將前置作業時間縮短至八週,並使他們能夠在東南亞的周界安防和工業領域以比西方公司競標低40%的價格中標。印度的「60%在地採購率」條款正引導國防相關訂單流向合資企業,從而刺激對國內晶圓廠的投資,並提高供應鏈的韌性。
預計到2025年,北美將佔銷售額的約29.80%。諸如「斯特瑞克」核生化防護車升級、士兵瞄準鏡和反無人機載荷等國防項目仍然是需求的主要驅動力。在汽車領域,夜視煞車系統的試點測試正在如火如荼地進行,為強制實施做準備。然而,由於最終法規尚未訂定,商業化進程較為緩慢,成長也落後於亞洲。預計到2025年,歐洲將佔銷售額的約15.20%,這得益於北約2%的國防費用目標和歐盟強制性的建築檢查制度。儘管歐洲擁有世界一流的研發體系,但分散的採購體系和嚴格的出口限制阻礙了其成長。
預計到2025年,中東和非洲地區的銷售額將佔全球總銷售額的約8.10%,這主要得益於沿岸地區基礎設施項目在管道和機場部署人工智慧熱成像攝影機。政治風險和外匯波動對多年預測構成壓力,但關鍵基礎設施的保護支撐著基本支出。南美洲5.80%的市佔率主要歸功於巴西和智利的應用案例,例如採礦、公共產業和野火監測。進口關稅和缺乏獎勵阻礙了技術的廣泛應用,但區域能源轉型計畫有望刺激新的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 汽車ADAS和夜視系統應用範圍的擴大
- 工業預測性維護和檢測的需求日益成長
- 國防和安全部門在熱成像方面的支出增加
- 降低微測輻射熱計感測器的成本
- 智慧型手機整合熱成像攝影機的出現。
- 晶圓級封裝技術的進步已將像素間距縮小到 10µm 以下。
- 市場限制因素
- 與冷卻式紅外線檢測器相比,性能有其局限性
- 紅外線元件的出口限制
- 大眾市場消費應用中的價格敏感性
- 影響紅外線光學元件的鍺供應限制
- 產業價值/價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 透過使用
- 車
- 軍事/國防
- 工業和製造業
- 安全監控
- 家用電子產品
- 測量和地圖繪製
- 衛生保健
- 透過檢測器技術
- 釩氧化物微測輻射熱計
- 非晶質微測輻射熱計
- 熱電堆陣列
- 熱電陣列
- 其他非製冷檢測器
- 按頻譜頻寬
- 長波紅外線(LWIR)
- 中波紅外線(MWIR)
- 短波紅外線(SWIR)
- 遠紅外線(FIR)
- 依產品類型
- 手持攝影機
- 固定攝影機
- 雲台變焦攝影機
- 車輛感應器
- 智慧型手機模組
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 肯亞
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Teledyne FLIR LLC
- Xenics NV
- Cantronic Systems Inc.
- BAE Systems plc
- Teledyne DALSA Inc.
- Zhejiang ULIRVISION Technology Co., Ltd.
- VIGO System SA
- Axis Communications AB
- Lynred USA Inc.
- Seek Thermal Inc.
- Wuhan Guide Infrared Co., Ltd.
- Zhejiang Dali Technology Co., Ltd.
- Yantai IRay Technology Co., Ltd.
- Raytheon Technologies Corporation
- L3Harris Technologies, Inc.
- Leonardo DRS, Inc.
- Fluke Corporation
- Opgal Optronic Industries Ltd.
- Honeywell International Inc.
- Excelitas Technologies Corp.
- InfraTec GmbH Infrarotsensorik und Messtechnik
- Hamamatsu Photonics KK
第7章 市場機會與未來展望
According to Mordor Intelligence, the uncooled infrared imaging market size is expected to grow from USD 4.75 billion in 2025 to USD 5.14 billion in 2026 and is forecast to reach USD 7.63 billion by 2031 at 8.21% CAGR over 2026-2031.
This report is Segmented by Application (Automotive, Military and Defense, Industrial and Manufacturing, and More), Detector Technology (Vanadium Oxide Microbolometers, Amorphous Silicon, and More), Spectral Band (Long-Wave Infrared, Mid-Wave Infrared, and More), Product Type (Handheld Cameras, Fixed-Mount Cameras, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Uncooled Infrared Imaging Market Trends and Insights
Rising Adoption in Automotive ADAS and Night Vision Systems
Pending National Highway Traffic Safety Administration rules that mandate automatic emergency braking capable of night-time pedestrian detection are propelling thermal cameras from luxury options to mainstream safety equipment. Valeo and Teledyne FLIR secured the first Automotive Safety Integrity Level B contract in 2024, validating production readiness for high-volume models. Radar struggles to classify living objects in clutter, lidar performance degrades in rain, and visible sensors fail in low light; thermal imaging closes these gaps at ranges beyond 100 m. Analysts now forecast annual microbolometer volumes exceeding 16 million units by 2030 versus fewer than 2 million in 2024, a scale shift that drives the uncooled infrared imaging market toward single-digit dollar die costs. Magna has already deployed more than 1.2 million thermal systems across its driver-assistance suite, signaling growing OEM confidence.
Growing Demand for Industrial Predictive Maintenance and Inspection
Unplanned downtime in semiconductor fabs, chemical plants, and power stations costs upwards of USD 50,000 per hour, sharpening the business case for real-time thermal inspection. Uncooled handheld cameras priced below USD 5,000 let technicians scan hundreds of assets per shift, flagging hot spots weeks before failures emerge. Edge-inferencing modules embedded within the sensor conduct convolutional-network analysis on-device, removing latency and bandwidth barriers. Electric-vehicle battery lines rely on thermal arrays to catch cell-stacking defects before runaway events, protecting entire production batches. ISO 50001 energy-efficiency audits further stimulate purchases as building managers translate temperature maps into retrofit priorities that cut operating costs.
Performance Limitations Compared to Cooled Infrared Detectors
Noise-equivalent temperature differences of 50-100 mK limit long-range surveillance, precision munitions, and research spectroscopy, domains that still specify cooled mid-wave arrays capable of sub-20 mK performance. Uncooled frame-rates top out near 60 Hz due to thermal time constants, well below the kilohertz speeds needed for ballistic imaging. Military sniper systems and turbine diagnostics therefore keep cooled technology on contract, capping the ceiling for uncooled penetration despite its cost and power benefits.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Defense and Security Expenditure on Thermal Imaging
- Decreasing Cost of Microbolometer Sensors
- Export Control Regulations on Infrared Components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Security and surveillance retained 34.10% of 2025 revenue, fueled by perimeter systems that cut false alarms from shadows and headlights. In contrast, automotive applications, though smaller, are forecast to grow at 10.05% through 2031, the fastest among all end-uses, driven by proposed U.S. braking rules that require nighttime detection of pedestrians, cyclists, and large animals. This regulation anchors the uncooled infrared imaging market size opportunity within mass-production vehicle platforms, moving beyond premium marques.
Industrial maintenance gains from thermal scans of switchgear and rotating machinery, while consumer electronics expand via sub-USD 200 smartphone cores that blur professional and prosumer boundaries. Mapping and surveying segments attach uncooled cameras to drones for crop health and power-line inspection, yet remain niche. Healthcare fever-screening demand has normalized post-pandemic, leaving a stable base in hospitals and transit hubs.
Vanadium-oxide designs captured 48.60% revenue in 2025, a legacy of defense funding that honed sensitivity, but amorphous silicon is climbing at 9.62% CAGR as fabs leverage standard CMOS tooling. Amorphous silicon's process affinity slashes per-die costs and simplifies monolithic integration with read-out circuits, critical for automotive economies of scale. The uncooled infrared imaging market share for vanadium-oxide may erode as car volumes dwarf defense demand, tilting capital investment toward silicon lines.
Thermopile and pyroelectric arrays hold low single-digit slices for motion sensing, where resolution is secondary. Emerging quantum-dot prototypes promise short-wave coverage at ambient temperature, yet manufacturability hurdles keep them in labs. Lynred's October 2024 purchase of New Imaging Technologies highlights supplier moves to hedge with short-wave assets as long-wave niches mature
Complete Report Scope:
- By Application
- Automotive
- Military and Defense
- Industrial and Manufacturing
- Security and Surveillance
- Consumer Electronics
- Mapping and Surveying
- Healthcare
- By Detector Technology
- Vanadium Oxide Microbolometers
- Amorphous Silicon Microbolometers
- Thermopile Arrays
- Pyroelectric Arrays
- Other Uncooled Detectors
- By Spectral Band
- Long-Wave Infrared (LWIR)
- Mid-Wave Infrared (MWIR)
- Short-Wave Infrared (SWIR)
- Far Infrared (FIR)
- By Product Type
- Handheld Cameras
- Fixed-Mount Cameras
- Pan-Tilt-Zoom Cameras
- Vehicle-Mounted Sensors
- Smartphone Modules
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 41.10% of 2025 revenue and is projected to post an 11.29% CAGR to 2031, well above the uncooled infrared imaging market average, as Chinese vendors integrate detector growth, wafer processing, and camera assembly under one roof . Vertical integration trims lead times to eight weeks and undercuts Western quotes by up to 40%, winning perimeter and industrial bids across Southeast Asia. India's 60% local-content clause reroutes defense orders to joint ventures, catalyzing domestic fab investment and broadening supply resilience.
North America contributed roughly 29.80% of 2025 revenue. Defense programs such as Stryker NBCRV upgrades, soldier-borne sights, and counter-drone payloads continue to anchor demand, while automotive pilots ramp ahead of night-vision brake mandates. Growth, however, lags Asia as commercial uptake waits for the final regulatory text. Europe secured about 15.20% revenue, buoyed by NATO's 2% GDP defense pledge and EU building-audit mandates. Fragmented procurement and strict export controls temper growth despite world-class R&D.
The Middle East and Africa combined for around 8.10% of 2025 revenue, led by Gulf infrastructure projects that deploy AI-enabled thermal cameras along pipelines and airports. Political risk and currency volatility dampen multi-year forecasts, yet critical-infrastructure protection sustains baseline spending. South America's 5.80% share stems from mining, utility, and wildfire-monitoring use cases in Brazil and Chile; import tariffs and limited incentives restrain broader adoption, yet regional energy-transition projects may unlock incremental demand.
- Teledyne FLIR LLC
- Xenics NV
- Cantronic Systems Inc.
- BAE Systems plc
- Teledyne DALSA Inc.
- Zhejiang ULIRVISION Technology Co., Ltd.
- VIGO System S.A.
- Axis Communications AB
- Lynred USA Inc.
- Seek Thermal Inc.
- Wuhan Guide Infrared Co., Ltd.
- Zhejiang Dali Technology Co., Ltd.
- Yantai IRay Technology Co., Ltd.
- Raytheon Technologies Corporation
- L3Harris Technologies, Inc.
- Leonardo DRS, Inc.
- Fluke Corporation
- Opgal Optronic Industries Ltd.
- Honeywell International Inc.
- Excelitas Technologies Corp.
- InfraTec GmbH Infrarotsensorik und Messtechnik
- Hamamatsu Photonics K.K.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption in Automotive ADAS and Night Vision Systems
- 4.2.2 Growing Demand for Industrial Predictive Maintenance and Inspection
- 4.2.3 Increasing Defense and Security Expenditure on Thermal Imaging
- 4.2.4 Decreasing Cost of Microbolometer Sensors
- 4.2.5 Emergence of Smartphone Integrated Thermal Cameras
- 4.2.6 Wafer-Level Packaging Advancements Reducing Pixel Pitch Below 10 µm
- 4.3 Market Restraints
- 4.3.1 Performance Limitations Compared to Cooled Infrared Detectors
- 4.3.2 Export Control Regulations on Infrared Components
- 4.3.3 Price Sensitivity in Mass-Market Consumer Applications
- 4.3.4 Germanium Supply Constraints Impacting Infrared Optics
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Automotive
- 5.1.2 Military and Defense
- 5.1.3 Industrial and Manufacturing
- 5.1.4 Security and Surveillance
- 5.1.5 Consumer Electronics
- 5.1.6 Mapping and Surveying
- 5.1.7 Healthcare
- 5.2 By Detector Technology
- 5.2.1 Vanadium Oxide Microbolometers
- 5.2.2 Amorphous Silicon Microbolometers
- 5.2.3 Thermopile Arrays
- 5.2.4 Pyroelectric Arrays
- 5.2.5 Other Uncooled Detectors
- 5.3 By Spectral Band
- 5.3.1 Long-Wave Infrared (LWIR)
- 5.3.2 Mid-Wave Infrared (MWIR)
- 5.3.3 Short-Wave Infrared (SWIR)
- 5.3.4 Far Infrared (FIR)
- 5.4 By Product Type
- 5.4.1 Handheld Cameras
- 5.4.2 Fixed-Mount Cameras
- 5.4.3 Pan-Tilt-Zoom Cameras
- 5.4.4 Vehicle-Mounted Sensors
- 5.4.5 Smartphone Modules
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Teledyne FLIR LLC
- 6.4.2 Xenics NV
- 6.4.3 Cantronic Systems Inc.
- 6.4.4 BAE Systems plc
- 6.4.5 Teledyne DALSA Inc.
- 6.4.6 Zhejiang ULIRVISION Technology Co., Ltd.
- 6.4.7 VIGO System S.A.
- 6.4.8 Axis Communications AB
- 6.4.9 Lynred USA Inc.
- 6.4.10 Seek Thermal Inc.
- 6.4.11 Wuhan Guide Infrared Co., Ltd.
- 6.4.12 Zhejiang Dali Technology Co., Ltd.
- 6.4.13 Yantai IRay Technology Co., Ltd.
- 6.4.14 Raytheon Technologies Corporation
- 6.4.15 L3Harris Technologies, Inc.
- 6.4.16 Leonardo DRS, Inc.
- 6.4.17 Fluke Corporation
- 6.4.18 Opgal Optronic Industries Ltd.
- 6.4.19 Honeywell International Inc.
- 6.4.20 Excelitas Technologies Corp.
- 6.4.21 InfraTec GmbH Infrarotsensorik und Messtechnik
- 6.4.22 Hamamatsu Photonics K.K.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 熱成像/紅外線缺陷檢測:市場佔有率分析、行業趨勢與統計數據、成長預測(2025-2030 年)
 紅外線成像市場:2026-2032年全球市場預測(依產品、技術、波長、應用及通路分類)
 紅外線和熱成像系統市場報告:趨勢、預測和競爭分析(至2035年)
 紅外線成像市場預測至2034年—按組件、波長、技術、應用、最終用戶和地區分類的全球分析
 2026年全球紅外線成像市場報告
 紅外線成像市場規模、佔有率、趨勢和預測:按技術、組件、波長、應用、產業和地區分類,2026-2034年紅外線成像軟體市場:2026-2032年全球市場預測(按產品類型、技術類型、波段、部署模式、應用和最終用戶產業分類)
 紅外線成像市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區的洞察,2026-2034年的預測紅外線成像氣體檢測器市場:按產品類型、技術、波長、應用、終端用戶產業和分銷管道分類,全球預測,2026-2032年
 熱成像建築檢測市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、最終用戶、流程、安裝類型、設備分類