


 |
市場調查報告書
商品編碼
2123022
3D重建:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)3D Reconstruction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,3D 重建市場預計到 2026 年價值 18.6 億美元,高於 2025 年的 16.7 億美元,預計到 2031 年將達到 31.9 億美元。
預計 2026 年至 2031 年的複合年成長率為 11.39%。
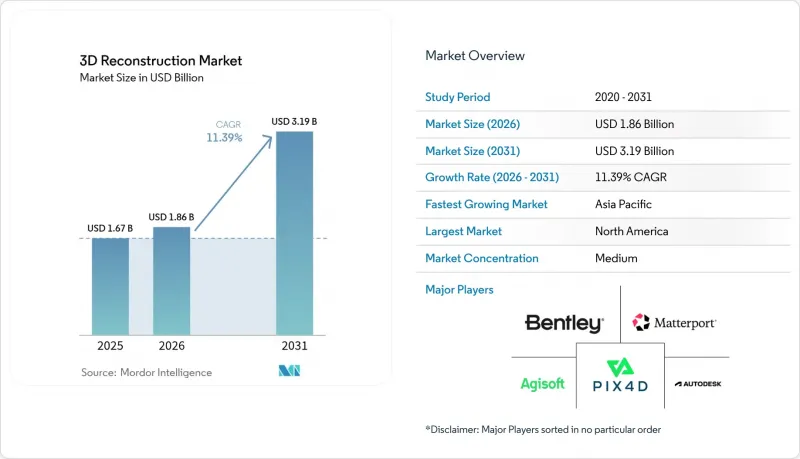
本報告按組件(軟體和服務)、技術類型(主動式3D重建和被動式3D重建)、部署模式(本地部署和雲端部署)、應用領域(建築和設計、醫療保健和醫學影像、文化遺產和博物館、工業製造和檢測等)以及地區進行細分。市場預測以美元(USD)計價。
全球3D重建市場趨勢與洞察
建築業中主導BIM的數位孿生技術
3D重建已成為一個“運作反饋循環”,不斷將BIM模型與現場實際情況同步。英國的國家數位孿生計畫和新加坡的虛擬新加坡等項目要求公共基礎設施承包商提供整合數位孿生模型,其中包含定期掃描數據,從而加速了對自動化點雲數據採集和網格對齊的需求。承包商表示,精確的重建可以減少現場返工,縮短交貨時間,因此,尋求最大限度降低生命週期成本的業主更傾向於採用這項技術。改進的互通性標準(例如ISO 19650的擴展)降低了資料轉換的門檻,並促進了多供應商工作流程。隨著數位孿生計畫擴展到市政和公共產業資產,3D重建市場也從設計團隊擴展到設施管理人員和維護承包商。
感測器和LiDAR成本的下降將促進它們的普及應用。
固態技術的創新和大規模生產已將車用級雷射雷達的成本降至每台500美元以下,使其應用範圍不再局限於一級承包商和大型國防公司。曾經售價高達5萬美元的手持式SLAM掃描儀,如今售價已低於3萬美元;無人機搭載的雷射雷達有效載荷價格也低於1萬美元,這使得公共產業合作社和中型測繪公司也能進行走廊測繪。硬體成本的降低正推動新的服務供應商進入南美洲、非洲和南亞市場。在這些地區,地面掃描在經濟上不可行,以往的專案都依賴衛星影像。然而,技能缺口正在轉向資料處理,供應商正透過提供雲端人工智慧工具集來解決這個問題,這些工具集可以自動對點雲資料進行分類、著色和降維,從而縮短非地理空間專家的培訓週期。
高昂的初始硬體和軟體投資成本
實用的地面掃描器價格仍然在 4 萬到 8 萬美元之間,而主流攝影測量軟體的授權和維護費用也超過每位使用者每年 4,000 美元。使用雲端 GPU 會進一步增加這些成本。對包含 1 萬張影像的量測資料進行高密度重建可能需要消耗 200 到 300 個 GPU 小時,處理成本高達 1,000 美元。對於文化遺產機構、小規模保險公司和市政規劃部門而言,這些高昂的資本投入可能會延緩技術應用,甚至促使他們考慮外包。供應商提供的解決方案包括硬體即服務 (HaaS) 套餐、按掃描收費和短期租賃,但這些方案通常會將客戶束縛在自己的生態系統中,並將總體成本推遲到以後,而不是降低成本。
細分市場分析
在軟體領域,預計到2025年,永久授權和訂閱模式的收入將佔總收入的68.52%,這主要得益於核心攝影測量和點雲平台的推動。同時,業務收益正以11.67%的複合年成長率成長,因為企業越來越傾向選擇承包工程而非內部系統開發。託管服務公司將現場資料收集、GPU處理、品質保證(QA)和資料管理打包成月費,提供的解決方案更適合專案預算而非資本採購。美國土木工程師協會(ASCE)指出,越來越多的客戶尋求第三方檢驗證書以證明測量精度,這為審計和諮詢服務帶來了更多機會。供應商正在透過組建專門的服務團隊來擴展其產品線。 Autodesk、Bentley Systems和Trimble等公司正在收購當地的測量專家,以提供建立可操作工作流程和建立合規文件的服務。隨著有關位置資料精度和個人資料脫敏的法規日益嚴格,這項服務將繼續成為3D重建市場中成長最快的領域。
推動該服務需求的第二個因素是某些高價值應用情境的間歇性。保險公司、執法機關和緊急應變組織需要在罕見事件發生後快速取得現場文檔,但維持常駐團隊和設備並不現實。基於訂閱的預錄製城市模型、按需現場團隊以及按掃描收費的機器人技術降低了這些間歇性客戶的准入門檻。在整個預測期內,從建築業的變更檢測分析到公共產業行業的客製化人工智慧細分模型,專業服務領域的收入預計將超過核心軟體收入,並重塑供應商的收入結構。
主動成像技術(主要由雷射雷達、結構光和飛行時間 (ToF) 感測器構成)預計到 2025 年將佔據 3D 重建市場 60.85% 的佔有率,這得益於其在受控環境下實現亞厘米級精度的能力。主動感測器在工業測量、工廠自動化和自動駕駛汽車領域仍然至關重要。然而,被動攝影測量技術正以 11.75% 的複合年成長率成長,神經輻射場和高斯散射技術能夠從分散的照片中獲得可列印的精確度。目前,「行動優先」的應用程式可以在幾分鐘內將 30-40 台行動裝置拍攝的影像轉換為紋理網格,從而以極低的成本在電子商務、住宅房地產和保險等領域得到應用。被動採集的成本優勢在戶外和大型專案中尤為顯著,尤其是在新興市場,關稅和供應鏈延遲阻礙了雷射雷達的進口。
將高密度LiDAR點雲與攝影測量紋理融合的混合工作流程正逐漸成為過渡方案。文物保護人員和橋樑檢測人員正在結合這些技術,以在單一模型中實現毫米級的形狀精度和照片級逼真的表面細節。隨著3D重建市場的擴張,供應商正在提供整合工具包,以協調主動和被動輸入,從而減輕工作人員的負擔。組件成本也在不斷下降。隨著LiDAR價格降至 500 美元以下,價格差異正在縮小,專案經理可以根據預算限制以及部署環境來選擇技術堆疊。
區域分析
北美地區得益於早期BIM強制實施、強大的國防工業基礎以及廣泛採用3D方式記錄保險索賠的保險業,預計到2025年將佔全球需求的35.25%。諸如「每日計數」(Every Day Counts)之類的聯邦項目正在推動使用雷射雷達(LiDAR)進行橋樑檢測,而加拿大礦業和林業公司則正在部署無人機進行環境監測。美國和加拿大各州的資料儲存法規差異可能會使跨國計畫變得複雜,但使用本地雲端區域可以緩解這個問題。在墨西哥,隨著鐵路和機場的現代化改造,走廊測繪計畫正在進行中,但由於國內專業技術有限,現場實施進展緩慢。
歐洲憑藉英國、德國和法國全國的BIM強制要求,以及地中海地區廣泛的文化遺產保護工作,保持著強勁的地位。 「地平線歐洲」計畫已撥款1,073.5億美元用於數位孿生和地理空間技術的研究,旨在重振產學研合作。 GDPR和即將推出的人工智慧法案等隱私法規增加了合規成本,同時也推動了對自動化遮罩、縮減和本土化處理的需求。面臨進口限制的俄羅斯建築公司正在轉向使用國產軟體,儘管存在功能上的不足,但這些軟體促進了當地生態系統的發展。
亞太地區正經歷最快成長,預計年複合成長率將達12.44%。在中國,超過2億元的公共計畫必須採用BIM技術,這推動了大規模的掃描到BIM工作流程。日本國土交通省正在使用配備LiDAR的無人機監測地震多發地區的隧道和橋樑,旨在保護供應鏈並確保公共安全。印度測量局正在推動城市3D測繪,以實現土地登記現代化並制定災害應變計畫。韓國的造船廠和半導體工廠需要進行亞毫米級檢測,而澳洲的採礦業正在利用航空LiDAR最佳化礦場。在印尼、菲律賓和太平洋島嶼地區,寬頻接入的不均衡和攝影測量培訓的缺乏阻礙了市場擴張。
在中東和非洲,隨著沙烏地阿拉伯的「NEOM」和阿拉伯聯合大公國的「杜拜2040」等舉措需要城市規模的數位孿生技術,銷售額正在加速成長。南非的深層礦井正在接受安全掃描,埃及旅遊部則在將文物數位化,用於虛擬旅遊。在一些撒哈拉以南非洲國家,政治不穩定和外匯波動阻礙了資本籌集,導致市場滲透率不平衡。然而,波灣合作理事會(GCC)成員國的成長,透過大型企劃的支出,正在提升全部區域。
在南美洲,建築業正在復甦,阿根廷正在擴大鋰礦開採規模,重拾發展動能。巴西的土地改革計畫正在推動無人機測繪技術的應用,以明確土地所有權,從而增加了對雲端攝影測量技術的需求。智利公共工程部正在利用雷射雷達(LiDAR)技術繪製泛美公路沿線的滑坡區域地圖,但雷射掃描儀和GPU的進口關稅增加了專案預算。南方共同市場數位基礎設施工作小組正在製定通用技術標準,以協調跨境資料交換,但實際實施仍處於緩慢階段。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在建設產業中擴大使用BIM的數位孿生技術
- 感測器和LiDAR成本的下降正在推動它們的廣泛應用。
- 整個媒體和娛樂產業對VR/AR內容的需求正在爆炸式成長。
- 利用無人機進行資料收集,實現大面積測繪
- 保險業正朝著 3D 現場記錄方向發展,以加快保險理賠速度。
- 以患者為中心的個人化手術計劃平台正引起廣泛關注。
- 市場限制因素
- 硬體和軟體的前期投入較高
- 工作流程複雜,需要專門的技能。
- 關於城市資料收集的隱私和資料主權法規
- 加強雲處理中碳足跡的監測
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 按組件
- 軟體
- 服務
- 依技術類型
- 主動式3D重建
- 被動式3D重建
- 按部署模式
- 現場
- 雲
- 透過使用
- 建築/建築設計
- 醫療保健和醫學影像
- 媒體與娛樂
- 文化遺產與博物館
- 工業製造與檢驗
- 公共安全與法醫學
- 機器人和無人機
- 教育/研究
- 遊戲和虛擬實境
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Autodesk Inc.
- Pix4D SA
- Agisoft LLC
- Bentley Systems Incorporated
- Capturing Reality sro
- Matterport Inc.
- Paracosm Inc.
- PhotoModeler Technologies
- Trimble Inc.
- Hexagon AB
- FARO Technologies Inc.
- Siemens AG
- Dassault Systemes SE
- 3Dflow SRL
- Skyline Software Systems Inc.
- NavVis GmbH
- GeoSLAM Ltd.
- DroneDeploy Inc.
- SimActive Inc.
- Artec Europe Sa rl(Artec 3D)
- SZ DJI Technology Co. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, 3D reconstruction market size in 2026 is estimated at USD 1.86 billion, growing from 2025 value of USD 1.67 billion with 2031 projections showing USD 3.19 billion, growing at 11.39% CAGR over 2026-2031.
This report is Segmented by Component (Software and Services), Technology Type (Active 3D Reconstruction and Passive 3D Reconstruction), Deployment Model (On-Premise and Cloud), Application (Construction and Architecture, Healthcare and Medical Imaging, Cultural Heritage and Museum, Industrial Manufacturing and Inspection, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global 3D Reconstruction Market Trends and Insights
BIM-Driven Digital Twins in Construction
3D reconstruction is now an always-on feedback loop that keeps BIM models synchronized with on-site reality. Mandates such as the United Kingdom's National Digital Twin Programme and Singapore's Virtual Singapore require public infrastructure contractors to deliver federated digital twins that ingest periodic scans, accelerating demand for automated point cloud capture and mesh alignment. Contractors report that accurate reconstructions reduce field rework and compress handover times, thereby boosting adoption among owners seeking to minimize lifecycle costs. Improved interoperability standards, typified by ISO 19650 extensions, are reducing data conversion friction and encouraging multi-vendor workflows. As digital-twin programs extend to municipal and utility assets, the 3D reconstruction market is expanding from design teams to facilities managers and maintenance contractors.
Falling Sensor and LiDAR Costs Boosting Accessibility
Solid-state innovation and volume manufacturing have pulled LiDAR price points below USD 500 per automotive-grade unit, widening the accessible customer base beyond tier-one contractors and defense primes. Handheld SLAM scanners, which once cost USD 50,000, now list for under USD 30,000, and drone-mounted LiDAR payloads have dropped below USD 10,000, making corridor mapping accessible to utility cooperatives and mid-sized survey firms. Lower hardware cost is drawing new service entrants in South America, Africa, and South Asia, where earlier projects relied on satellite imagery because terrestrial scanning was uneconomical. The skills gap, however, has shifted to data processing; vendors are responding with cloud-hosted AI toolsets that automatically classify, colorize, and thin-point clouds, thereby shortening training cycles for non-geospatial professionals.
High Up-Front Hardware-Software Investment Outlay
A production-grade terrestrial scanner still ranges from USD 40,000 to USD 80,000, and leading photogrammetry software carries annual license and maintenance charges that can exceed USD 4,000 per seat. Cloud GPU time compounds these commitments: dense reconstruction of a 10,000-image survey can consume 200-300 GPU hours and incur USD 1,000 in processing fees. For cultural heritage bodies, small insurers, and municipal planning offices, capital intensity can slow adoption or prompt them to consider outsourcing. Vendor responses include hardware-as-a-service bundles, per-scan pricing, and short-term rentals; however, these alternatives often lock customers into proprietary ecosystems and defer, rather than eliminate, total costs.
Other drivers and restraints analyzed in the detailed report include:
- Explosive VR and AR Content Demand Across Media and Entertainment
- Drone-Based Data Capture Enabling Large-Area Mapping
- Workflow Complexity Requiring Specialist Skillsets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software captured 68.52% of 2025 revenue through perpetual-license and subscription models, monetizing core photogrammetry and point-cloud platforms. Services revenue, however, is rising at an 11.67% CAGR because enterprises increasingly favor turnkey deliverables over in-house buildouts. Managed-service firms bundle field capture, GPU processing, QA, and data management into monthly fees that better align with project budgets than capital purchases. The American Society of Civil Engineers notes that a rising share of owners demand third-party validation certificates for survey accuracy, expanding opportunity for audit and advisory engagements. Vendors are augmenting product lines with captive service teams. Autodesk, Bentley Systems, and Trimble have each acquired regional survey specialists to offer hands-on workflow configuration and compliance documentation. As regulatory oversight around geolocation precision and personal-data masking tightens, services will remain the fastest-growing component of the 3D reconstruction market.
A second factor elevating services is the episodic nature of several high-value use cases. Insurers, law enforcement units, and emergency response agencies require rapid scene capture after rare events but cannot justify maintaining permanent teams or equipment. Subscription access to pre-shot city twins, on-demand field crews, and pay-per-scan robotics lowers barriers for these intermittent customers. Over the forecast horizon, professional services lines, ranging from change-detection analytics in construction to bespoke AI segmentation models in utilities, are expected to outpace core software revenue and reshape the vendor revenue mix.
Active imaging, dominated by LiDAR, structured light, and time-of-flight sensors, held a 60.85% market share in 3D reconstruction in 2025, owing to its unmatched sub-centimeter fidelity in controlled conditions. Industrial metrology, factory automation, and autonomous vehicles still treat active sensors as mandatory. Yet passive photogrammetry is growing at an 11.75% CAGR as neural radiance fields and Gaussian splatting yield printable accuracy from sparse photographs. Mobile-first apps now transform 30-40 handheld images into textured meshes within minutes, a capability that unlocks ecommerce, residential real estate, and insurance use cases at negligible cost. The cost advantage of passive capture is particularly decisive for outdoor and large-area projects, especially in emerging markets where LiDAR imports face tariffs and supply chain delays.
Hybrid workflows that blend dense LiDAR point clouds with photogrammetric textures occupy a rising middle ground. Cultural heritage conservators and bridge inspectors combine modalities to achieve millimeter-level geometry and photorealistic surface detail in a single model. As the 3D reconstruction market size expands, vendors are shipping integrated toolkits that co-register active and passive inputs, reducing operator effort. Component costs are converging as well: as LiDAR falls below USD 500, price differentials shrink, allowing project managers to choose technology stacks based on the deployment environment rather than solely on budget constraints.
Complete Report Scope:
- By Component
- Software
- Services
- By Technology Type
- Active 3D Reconstruction
- Passive 3D Reconstruction
- By Deployment Model
- On-Premise
- Cloud
- By Application
- Construction and Architecture
- Healthcare and Medical Imaging
- Media and Entertainment
- Cultural Heritage and Museum
- Industrial Manufacturing and Inspection
- Public Safety and Forensics
- Robotics and Drones
- Education and Research
- Gaming and Virtual Reality
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.25% of 2025 demand, buoyed by early BIM mandates, a robust defense-industrial base, and an insurance sector that widely documents claims in 3D. U.S. federal programs, such as Every Day Counts, promote LiDAR bridge inspections, while Canadian mining and forestry firms deploy drones for environmental monitoring. Data-residency differences among U.S. states and Canadian provinces can complicate cross-border projects; however, local cloud regions help mitigate this issue. Mexico's rail and airport modernizations have led to corridor-mapping projects, although limited domestic expertise has slowed the field execution.
Europe maintains a strong position through nationwide BIM requirements in the United Kingdom, Germany, and France, as well as through extensive cultural heritage preservation across the Mediterranean. Horizon Europe allocated USD 107.35 billion in research funding toward digital twin and geospatial technologies, stimulating university-industry consortia. Privacy rules under GDPR and the forthcoming AI Act increase compliance costs but also drive demand for automated masking, redaction, and on-shore processing. Russian construction firms, facing import constraints, have turned to domestic software, which has encouraged the growth of the local ecosystem despite capability gaps.
The Asia-Pacific region is the fastest-growing, with a projected 12.44% CAGR. China's mandate that public projects above CNY 200 million deploy BIM is feeding large-scale scan-to-BIM workflows. Japan's transport ministry utilizes LiDAR-equipped drones to monitor tunnels and bridges in seismic zones, thereby protecting supply chains and ensuring public safety. India's Survey of India is mapping cities in 3D to modernize land records and disaster-response planning. South Korea's shipyards and fabs require sub-millimeter inspection, while Australia's mining sector leverages aerial LiDAR for pit optimization. Broadband gaps and limited photogrammetry training restrict expansion in Indonesia, the Philippines, and Pacific Island states.
Middle East and Africa sales accelerate as Saudi Arabia's NEOM and the United Arab Emirates' Dubai 2040 initiatives demand city-scale digital twins. South Africa's deep mines scan underground workings for safety, and Egypt's Ministry of Tourism digitizes antiquities for virtual tourism. Political instability and currency volatility hinder capital acquisitions in several sub-Saharan countries, resulting in uneven market penetration. Gulf Cooperation Council growth, however, drags regional averages upward through mega-project spending.
South America experiences renewed momentum as Brazil's construction sector rebounds, and Argentina expands its lithium mining operations. Brazilian land-reform programs now mandate drone surveys for land-tenure clarification, spurring demand for cloud photogrammetry. Chile's public-works ministry relies on LiDAR to map landslide zones on the Pan-American Highway, but import tariffs on laser scanners and GPUs inflate project budgets. A Mercosur digital infrastructure working group is drafting shared technical standards to harmonize cross-border data exchange; yet, tangible adoption remains incremental.
- Autodesk Inc.
- Pix4D SA
- Agisoft LLC
- Bentley Systems Incorporated
- Capturing Reality s.r.o.
- Matterport Inc.
- Paracosm Inc.
- PhotoModeler Technologies
- Trimble Inc.
- Hexagon AB
- FARO Technologies Inc.
- Siemens AG
- Dassault Systemes SE
- 3Dflow SRL
- Skyline Software Systems Inc.
- NavVis GmbH
- GeoSLAM Ltd.
- DroneDeploy Inc.
- SimActive Inc.
- Artec Europe S.a r.l. (Artec 3D)
- SZ DJI Technology Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption of BIM-Driven Digital Twins in Construction
- 4.2.2 Falling Sensor and LiDAR Costs Boosting Accessibility
- 4.2.3 Explosive VR- and AR-Content Demand Across Media and Entertainment
- 4.2.4 Drone-Based Data Capture Enabling Large-Area Mapping
- 4.2.5 Insurance Sector Shift to 3D Scene Documentation for Rapid Claims
- 4.2.6 Patient-Specific Surgical Planning Platforms Gaining Traction
- 4.3 Market Restraints
- 4.3.1 High Up-Front Hardware-Software Investment Outlay
- 4.3.2 Workflow Complexity Requiring Specialist Skillsets
- 4.3.3 Urban-Capture Privacy and Data-Sovereignty Regulations
- 4.3.4 Cloud Processing's Rising Carbon-Footprint Scrutiny
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Degree of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Technology Type
- 5.2.1 Active 3D Reconstruction
- 5.2.2 Passive 3D Reconstruction
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.4 By Application
- 5.4.1 Construction and Architecture
- 5.4.2 Healthcare and Medical Imaging
- 5.4.3 Media and Entertainment
- 5.4.4 Cultural Heritage and Museum
- 5.4.5 Industrial Manufacturing and Inspection
- 5.4.6 Public Safety and Forensics
- 5.4.7 Robotics and Drones
- 5.4.8 Education and Research
- 5.4.9 Gaming and Virtual Reality
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Autodesk Inc.
- 6.4.2 Pix4D SA
- 6.4.3 Agisoft LLC
- 6.4.4 Bentley Systems Incorporated
- 6.4.5 Capturing Reality s.r.o.
- 6.4.6 Matterport Inc.
- 6.4.7 Paracosm Inc.
- 6.4.8 PhotoModeler Technologies
- 6.4.9 Trimble Inc.
- 6.4.10 Hexagon AB
- 6.4.11 FARO Technologies Inc.
- 6.4.12 Siemens AG
- 6.4.13 Dassault Systemes SE
- 6.4.14 3Dflow SRL
- 6.4.15 Skyline Software Systems Inc.
- 6.4.16 NavVis GmbH
- 6.4.17 GeoSLAM Ltd.
- 6.4.18 DroneDeploy Inc.
- 6.4.19 SimActive Inc.
- 6.4.20 Artec Europe S.a r.l. (Artec 3D)
- 6.4.21 SZ DJI Technology Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 3D重建技術市場規模、佔有率和成長分析:按組件、類型、企業規模、部署方式、應用、最終用途和地區分類-2026-2033年產業預測
 3D重建市場:依建築類型、最終用戶產業和地區分類
 3D重建技術市場:按組件、技術、應用、最終用戶和部署類型分類-2026-2032年全球預測
 全球3D重建技術市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 攝影測量軟體市場 - 全球產業規模、佔有率、趨勢、機會和預測:按類型、部署模式、定價模式、最終用戶供應商、地區和競爭格局分類,2021-2031 年
 2026-2030年全球攝影測量軟體市場
 照相測量軟體的全球市場 (~2032年):照相測量類型·部署模型·定價模式·終端用途產業·各地區
 3D重建軟體的全球市場3D 重建技術的全球市場
 亞太地區 3D 重建技術市場預測至 2031 年 - 區域分析 - 按類型、組件、部署、企業規模和最終用途行業