


 |
市場調查報告書
商品編碼
2122973
曳引機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Tractor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
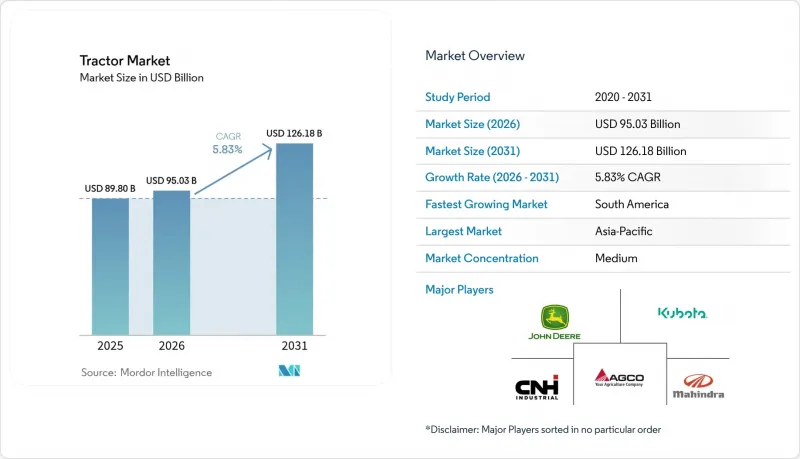
根據 Mordor Intelligence 預測,到 2026 年,曳引機市場規模預計將達到 950.3 億美元,高於 2025 年的 898 億美元。
此外,預計到 2031 年,該產業的價值將達到 1,261.8 億美元,並且預計從 2026 年到 2031 年的複合年成長率將達到 5.83%。
本報告按馬力(40馬力以下及其他)、驅動方式(兩輪驅動 (2WD)、四輪驅動/全輪驅動 (4WD/AWD))、動力類型(柴油、純電動、混合動力)、應用領域(農業、建築、林業及其他)和地區進行細分。市場預測以美元 (USD) 為單位。
全球曳引機市場趨勢與洞察
新興國家對機械化的需求不斷成長
由於人口向都市區遷移以及農村地區勞動力短缺,機械化已成為亞洲和非洲的戰略要務。印度的機械化率僅40-45%,遠低於中國的57%和美國的95%,顯示其機械化程度仍有很大的提升空間。中國一項新的補貼計畫優先推廣智慧四驅曳引機,並加速向高馬力曳引機的轉型,以提高單位面積生產力。合作所有權模式和設備共用應用程式透過分攤成本進一步促進了機械化的普及,而精準施肥等優勢則有助於改善土壤健康。這些趨勢共同作用,使曳引機從單純的動力源轉變為多功能資產,從而推動了全球曳引機市場的長期需求。
經合組織和金磚國家農業勞動力短缺問題日益嚴重。
美國農民正面臨嚴重的勞動力短缺,導致人事費用飆升,利潤率承壓。歐盟和中國也出現了類似的短缺情況。為了應對這項挑戰,生產者正在加快購買機械設備,並在薪資上漲之前採用省力技術。在園藝和特種作物種植領域,自動駕駛和遙控曳引機的應用取得了顯著進展,尤其是在那些季節性勞動力供應仍面臨持續挑戰的地區,趨勢更為明顯。持續的勞動力短缺構成了全球曳引機市場需求的根本基礎,並凸顯了農業實踐的變革性變化。隨著這些先進機械被引入農場,它們不僅填補了勞動力缺口,還革新了作物的種植和收割方式,為這個亟需創新的行業開闢了提高效率和生產力的新途徑。
電子晶片供應瓶頸
持續的半導體短缺對動力傳動系統控制器和感測器模組的生產造成了嚴重影響。 2025年初,32位元微控制器的前置作業時間竟超過驚人的50週,導致生產線停工和交貨期延長等令人沮喪的情況。儘管一些汽車晶片製造廠終於開始恢復運營,但產能壓力依然存在,限制了全球曳引機市場的關鍵短期產量。在競爭日益激烈的市場環境下,這種供應限制的連鎖反應正愈演愈烈,製造商正竭力滿足市場需求。
細分市場分析
40-100馬力等級的曳引機用途廣泛,是其旗艦產品,預計到2025年將佔全球曳引機市場46.93%的佔有率,為全球曳引機市場提供支撐。隨著大型農場尋求更高的面積效率,預計100馬力以上的曳引機在預測期內將以7.16%的複合年成長率成長。動力提升支援先進的液壓系統和更寬的作業寬度,從而實現整合式精準技術。約翰迪爾在愛荷華州擴建9RX系列曳引機生產線,凸顯了其對曳引機需求長期顯著成長的信心。
大型農業經營模式充分利用配備遠端資訊處理技術的車隊的協調能力,將馬力轉化為顯著提升生產力的關鍵驅動力。同時,40匹馬力以下的小型曳引機在園藝等專業領域仍佔據著獨特的細分市場,但由於小規模農場機械化進程緩慢,其未來前景仍不不確定性。因此,對高馬力曳引機日益成長的需求正在推動全球曳引機市場的高階細分市場發展,加速收入成長而非銷售成長。
到2025年,經濟實惠的兩輪驅動平台將佔據曳引機市場77.10%的佔有率。然而,四輪驅動的優勢在於其更強的牽引力,以及在潮濕或坡地耕作時能夠更好地分配扭矩。預計到2031年,四輪驅動的複合年成長率將達到7.69%,這與精密農業的廣泛應用不謀而合,精準農業中,持續的車輪打滑能夠確保播種的精準度。
氣候變遷的不可預測性正在改變農業耕作方式,進一步縮短了土壤水分低於理想水平時可進行田間作業的時間。這項變革凸顯了投資乾濕交替(AWD)耕作方式的價值,並加強了農民與創新解決方案之間的連結。隨著農民努力實現全年耕作,許多人越來越將四輪驅動(4WD)車輛視為應對不可預測天氣的關鍵保障。這種觀念的轉變進一步加深了四輪驅動車輛的普及與提高盈利之間的聯繫,凸顯了這些技術進步對於克服現代農業挑戰的重要性。
區域分析
到2025年,亞太地區將佔全球曳引機市場規模的55.35%。隨著中國向高馬力和智慧曳引機轉型,其將繼續發揮關鍵作用。東南亞各國政府為農機採購提供優惠融資,從而維持了該地區在全球曳引機市場的強勁成長動能。
南美洲正經歷最快的成長,複合年成長率達6.89%,這主要得益於巴西大豆和玉米種植面積的擴大以及促進設備升級的國內融資機制。馬賽·弗格森、瓦爾特拉和紐荷蘭在巴西佔據了相當大的市場佔有率,這清楚地表明了本地組裝對客戶偏好的影響。智利和哥倫比亞透過水果出口多元化進一步擴大了需求,從而增強了整個南美洲的成長勢頭。
北美和歐洲是成熟的汽車市場,其特點是銷售成長相對緩慢,但單車價值較高。 2024年,歐洲汽車註冊量暴跌至近十年來的最低水平,反映出盈利挑戰日益嚴峻。儘管如此,歐洲在電動車測試和自動駕駛技術法規結構的發展方面發揮先鋒作用。
同時,中東和非洲市場仍處於發展初期,但其對全球曳引機產業的長期擴張和多元化發展的重要性日益凸顯。在這個充滿成長機會的地區,這些地區象徵著新的發展機遇,其戰略重要性不容小覷。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興國家對機械化的需求不斷成長
- 政府補貼和低利率農業貸款計劃
- 經合組織和金磚國家農業勞動力短缺問題日益嚴重。
- 精密農業和遠端資訊處理平台的快速普及
- 電池動力和燃料電池動力曳引機的商業化
- 數據驅動型曳引機租賃平台的發展
- 市場限制因素
- 初始成本高且產品價格波動較大
- 季風/氣候週期導致的營收季節性波動
- 電子晶片供應瓶頸
- 貿易協定中的新本地化和原產地規則
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 惠普
- 小於40馬力
- 40~100HP
- 超過100馬力
- 透過驅動系統
- 兩輪驅動(2WD)
- 四輪驅動/全輪驅動(4WD/AWD)
- 依推進類型
- 柴油引擎
- 電池供電
- 混合動力(柴油/電動)
- 透過使用
- 農業
- 建造
- 林業
- 地方政府/場地管理
- 運輸/物流
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Deere & Company
- CNH Industrial NV(Case IH, New Holland)
- AGCO Corporation(Massey Ferguson, Valtra, Fendt)
- Mahindra & Mahindra Ltd.
- Kubota Corporation
- CLAAS KGaA mbH
- Escorts Kubota Ltd.
- TAFE Ltd.
- Sonalika(International Tractors Ltd.)
- SDF Group(Same Deutz-Fahr)
- Yanmar Co. Ltd.
- Argo Tractors SpA
- LS Mtron Ltd.
- Daedong(Kioti)
- TYM Corporation
- Weichai Lovol Intelligent Agricultural Technology CO., LTD
- YTO Group Corp.
- XCMG Construction Machinery Co., Ltd.
- Zetor Tractors as
- JC Bamford Excavators Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, tractor market size in 2026 is estimated at USD 95.03 billion, growing from 2025 value of USD 89.8 billion with 2031 projections showing USD 126.18 billion, growing at 5.83% CAGR over 2026-2031.
This report is Segmented by Horsepower (Below 40 HP, and More), Drive Type (Two-Wheel Drive and Four-/All-Wheel Drive), Propulsion Type (Diesel, Battery-Electric, and Hybrid), Application (Agriculture, Construction, Forestry, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Tractor Market Trends and Insights
Rising Mechanization Demand in Emerging Economies
Urban migration and shrinking rural labor pools make mechanization a strategic necessity across Asia and Africa. India's 40-45% mechanization rate trails China's 57% and the United States' 95%, offering clear catch-up potential. New subsidy schemes in China prioritize smart 4WD tractors, promoting a shift toward higher horsepower that lifts per-acre productivity. Cooperative ownership models and equipment-sharing apps further catalyze adoption by spreading costs, while precision-placement benefits such as optimized fertilizer use improve soil health. Collectively, these trends embed tractors as multifunctional assets rather than basic power units, reinforcing long-term demand for the global tractor market.
Escalating Farm-Labor Shortages in OECD and BRICS
United States farmers grapple with a significant labor shortage, leading to heightened wage costs and squeezed profit margins. Similar gaps exist in the European Union and China. Growers respond by accelerating machinery purchases, now adopting labor-saving technology ahead of wage hikes. Autonomous and remotely operated tractors are making significant strides in the realms of horticulture and specialty crop farming, particularly in areas where securing a reliable seasonal workforce has become an ongoing challenge. This persistent labor shortage creates a fundamental baseline for the demand in the global tractor market, underscoring a transformative shift in agricultural practices. As these advanced machines take to the fields, they are not just filling a gap; they are revolutionizing the way crops are cultivated and harvested, opening up new possibilities for efficiency and productivity in an industry in need of innovation.
Electronics-Grade Chip Supply Bottlenecks
The ongoing semiconductor shortages are casting a long shadow over the production of power-train controllers and sensor modules. In early 2025, the lead times for 32-bit microcontrollers soared beyond a staggering 50 weeks, leading to frustrating line stoppages and protracted delivery timelines. While some automotive chip fabrication facilities are finally beginning to open their doors, the strain on capacity persists, limiting the immediate output crucial for the global tractor market. The ripple effects of this constraint are felt deeply, as manufacturers scramble to keep pace with demand amid an increasingly competitive landscape.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Precision-Ag and Telematics Platforms
- Growth of Data-Driven Tractor-Rental Platforms
- New Localization and Content-Origin Rules in Trade Pacts
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 40-100 HP class supplied mainstream versatility and claimed 46.93% of the tractor market size in 2025, anchoring the global tractor market. Above-100 HP units are forecast to grow at a 7.16% CAGR during the forecast period, as larger farms seek acreage efficiency. This up-powering supports advanced hydraulic systems and greater implement widths, allowing integrated precision technologies. John Deere's Iowa expansion to build 9RX machines underscores long-term confidence in significant iron demand.
Farm business models focusing on larger scales harness the power of telematics-driven fleet coordination, transforming horsepower into a catalyst for extraordinary productivity. While smaller tractors with less than 40 HP continue to carve out their niche in the specialized realm of horticulture, the gradual pace of mechanization in micro-plots casts a shadow over their prospects. Consequently, high-horsepower momentum lifts the premium end of the global tractor market size, propelling revenue faster than unit volume.
Cost-efficient 2WD platforms held a 77.10% share of the tractor market in 2025. Yet 4WD adoption benefits from added traction, distributing torque for tillage under wetter or sloped conditions. The 7.69% CAGR projected for 4WD through 2031 aligns with broader precision-ag uptake, where consistent wheel slip protects seed placement accuracy.
The unpredictable nature of climate variability is reshaping the landscape of agricultural practices, extending the fleeting windows of opportunity for fieldwork when soil moisture levels fall below ideal conditions. This shift underscores the value of Alternate Wetting and Drying (AWD) investments, forging a stronger connection between farmers and innovative solutions. As they strive for year-round cultivation, many are now viewing four-wheel drive (4WD) vehicles as a vital safeguard against the whims of the weather. This evolving mindset deepens the relationship between the adoption of 4WD and the quest for greater profitability, highlighting how essential these advancements have become in navigating the challenges of modern farming.
Complete Report Scope:
- By Horsepower
- Below 40 HP
- 40 - 100 HP
- Above 100 HP
- By Drive Type
- Two-Wheel Drive (2WD)
- Four-/All-Wheel Drive (4WD/AWD)
- By Propulsion Type
- Diesel
- Battery-Electric
- Hybrid (Diesel-Electric)
- By Application
- Agriculture
- Construction
- Forestry
- Municipal & Grounds Maintenance
- Haulage & Logistics
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 55.35% of the tractor market size in 2025. China remains pivotal as it pivots toward high-horsepower and smart tractors. Southeast Asian governments channel concessional credit into machinery purchases, maintaining a solid growth runway for the global tractor market in the region.
South America delivers the fastest expansion at 6.89% CAGR, buoyed by Brazil's soy and corn acreage gains and domestic credit lines that spur equipment upgrades. Massey Ferguson, Valtra, and New Holland have a significant share of Brazilian sales, illustrating the influence of localized assembly on customer preference. Chile and Colombia inject incremental demand through fruit-export diversification, reinforcing continental momentum.
North America and Europe showcase well-established markets characterized by a more measured pace of volume growth, yet they boast a higher value per unit. In 2024, European vehicle registrations plummeted to a decade low, reflecting the tightening grip of profitability challenges. Despite this, Europe stands at the forefront of pioneering electric vehicle trials and developing regulatory frameworks for autonomous technology.
Meanwhile, the Middle East and Africa, still in their early stages of market development, are becoming increasingly vital to the long-term expansion and diversity of the global tractor industry. Their strategic importance cannot be understated as they represent emerging opportunities in a landscape ripe for growth.
- Deere & Company
- CNH Industrial N.V. (Case IH, New Holland)
- AGCO Corporation (Massey Ferguson, Valtra, Fendt)
- Mahindra & Mahindra Ltd.
- Kubota Corporation
- CLAAS KGaA mbH
- Escorts Kubota Ltd.
- TAFE Ltd.
- Sonalika (International Tractors Ltd.)
- SDF Group (Same Deutz-Fahr)
- Yanmar Co. Ltd.
- Argo Tractors S.p.A.
- LS Mtron Ltd.
- Daedong (Kioti)
- TYM Corporation
- Weichai Lovol Intelligent Agricultural Technology CO., LTD
- YTO Group Corp.
- XCMG Construction Machinery Co., Ltd.
- Zetor Tractors a.s.
- J C Bamford Excavators Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Mechanization Demand in Emerging Economies
- 4.2.2 Government Subsidies and Low-Interest Ag-Credit Lines
- 4.2.3 Escalating Farm-Labor Shortages in OECD and BRICS
- 4.2.4 Rapid Adoption of Precision-Ag and Telematics Platforms
- 4.2.5 Commercialization of Battery-Electric and Fuel-Cell Tractors
- 4.2.6 Growth of Data-Driven Tractor-Rental Platforms
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost and Commodity-Price Volatility
- 4.3.2 Seasonal Income Dependence on Monsoon/Weather Cycles
- 4.3.3 Electronics-Grade Chip Supply Bottlenecks
- 4.3.4 New Localization and Content-Origin Rules In Trade Pacts
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Horsepower
- 5.1.1 Below 40 HP
- 5.1.2 40 - 100 HP
- 5.1.3 Above 100 HP
- 5.2 By Drive Type
- 5.2.1 Two-Wheel Drive (2WD)
- 5.2.2 Four-/All-Wheel Drive (4WD/AWD)
- 5.3 By Propulsion Type
- 5.3.1 Diesel
- 5.3.2 Battery-Electric
- 5.3.3 Hybrid (Diesel-Electric)
- 5.4 By Application
- 5.4.1 Agriculture
- 5.4.2 Construction
- 5.4.3 Forestry
- 5.4.4 Municipal & Grounds Maintenance
- 5.4.5 Haulage & Logistics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 CNH Industrial N.V. (Case IH, New Holland)
- 6.4.3 AGCO Corporation (Massey Ferguson, Valtra, Fendt)
- 6.4.4 Mahindra & Mahindra Ltd.
- 6.4.5 Kubota Corporation
- 6.4.6 CLAAS KGaA mbH
- 6.4.7 Escorts Kubota Ltd.
- 6.4.8 TAFE Ltd.
- 6.4.9 Sonalika (International Tractors Ltd.)
- 6.4.10 SDF Group (Same Deutz-Fahr)
- 6.4.11 Yanmar Co. Ltd.
- 6.4.12 Argo Tractors S.p.A.
- 6.4.13 LS Mtron Ltd.
- 6.4.14 Daedong (Kioti)
- 6.4.15 TYM Corporation
- 6.4.16 Weichai Lovol Intelligent Agricultural Technology CO., LTD
- 6.4.17 YTO Group Corp.
- 6.4.18 XCMG Construction Machinery Co., Ltd.
- 6.4.19 Zetor Tractors a.s.
- 6.4.20 J C Bamford Excavators Ltd
7 Market Opportunities & Future Outlook

 全輪驅動曳引機市場:全球市場預測(2026-2032年)
 全球二手曳引機市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 全輪驅動曳引機市場機會、成長要素、產業趨勢分析及 2026-2035 年預測。
 大馬力曳引機市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、地區和競爭格局分類,2021-2031年二手曳引機市場機會、成長要素、產業趨勢分析及2026-2035年預測
 低馬力曳引機市場:按馬力、驅動系統、應用和地區分類(2026-2034 年)
 曳引機市場:按功率輸出、驅動類型、應用和地區分類履帶曳引機市場:2026-2032年全球市場預測(按應用、功率範圍、最終用戶、燃料類型、變速箱類型和銷售管道)全球全輪驅動曳引機市場:市場規模、佔有率、趨勢和成長分析(2026-2034 年)大型推土機市場:2026-2032年全球市場預測(依型號、功率範圍、動力傳動系統、應用、最終用戶和銷售管道分類)