


 |
市場調查報告書
商品編碼
2122869
路燈:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Street And Roadway Lighting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,到 2026 年,街道和道路照明市場價值將達到 106.3 億美元,高於 2025 年的 101 億美元,預計到 2031 年將達到 137.5 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.28%。
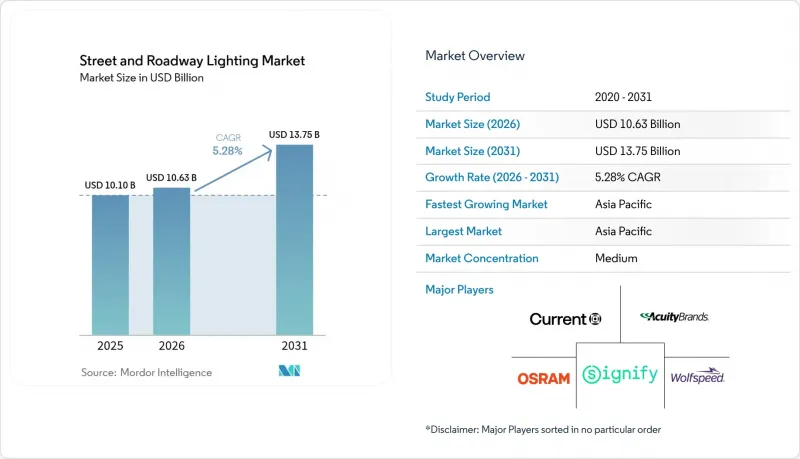
本報告依照明類型(傳統照明、智慧/連網照明)、光源(LED、螢光、HID燈)、交付方式(硬體、軟體/服務)、功率範圍(50W以下、50-150W、150W以上)、應用領域(高速公路、城區、隧道、停車場)、連接方式(有線、無線)及地區(北美、南美)區進行區隔。市場預測以美元計價。
全球街道和道路照明市場趨勢及洞察
加速LED維修計劃
市政LED部署舉措目前正將感測器網路、自適應控制和電網現代化目標相結合,以減少碳排放並進一步降低營運和維護成本。紐約電力公司(NYPA)的「紐約智慧路燈」計畫透過將需量反應和需量反應調諧融入LED升級改造中,展示了這種模式。愛爾蘭耗資1750萬歐元的農村轉型計畫也同樣優先考慮能夠處理未來車聯網(V2I)通訊的照明設備,這表明都市區「面向頻譜升級」的照明規範正在不斷發展。資金籌措方案、能源服務合約、綠色債券和基礎設施基金正在擴大LED照明的普及範圍,降低生命週期成本,並拓寬目標街道和道路照明市場。
擴大連網/物聯網路燈的普及應用
隨著細粒度資產數據的價值日益凸顯,城市正從試點計畫轉向街道級智慧照明部署。 Signify 報告稱,到 2024 年,其管理的智慧照明節點將達到 1.44 億個,充分展現了該平台的擴充性。低功耗廣域通訊技術(例如 NB-IoT 和 LoRaWAN)降低了連接成本,使得智慧照明的部署即使在較小的城市也成為可能。在哥本哈根,一個由 44,000 個節點組成的網路將空氣品質感測器整合到照明設備中,透過分析環境法規的合規情況,為市政當局創造了新的收入來源。這種從節能到數據貨幣化的轉變,透過提高供應商轉換門檻和延長合約期限,正在推動長期成長。
大規模照明昇級需要高額的初始資本投入。
互聯系統的總擁有成本可能超過每台500美元,是基本LED燈具更換成本的三倍。這迫使市政當局尋求透過能源服務公司(ESCO)或官民合作關係進行資金籌措,導致採購週期延長至18個月。沒有資本改善預算的小規模城市面臨最嚴峻的融資,儘管長期節能效果顯著,但仍難以即時部署。津貼專案雖然可以部分彌補資金缺口,但通常需要詳細的測量和檢驗(M&V)文件,這增加了行政負擔,延緩了部署進程。
細分市場分析
儘管智慧/連網解決方案預計將以 6.82% 的複合年成長率成長,但到 2025 年,傳統照明燈具仍將佔銷售額的 56.15%。這種並存的局面顯示資產更新周期正在逐步推進,也證實了傳統照明方案在基礎照明應用中仍然可行。大都會圈政府正在優先路線上部署互聯系統,因為數據分析能夠證明更高的定價合理;而小規模的地區則傾向於用配備可升級節點的被動式 LED 燈具替換現有系統。無論採用哪種方式,隨著老舊的高強度氣體放電燈泡逐步淘汰,街道和道路照明市場都將從中受益。 Signify 平台擁有 1.44 億個照明點,這凸顯了其平台的擴充性,同時也加劇了廠商的鎖定效應。
隨著標準化機構將互聯互通納入未來的能源標準,並將資本投資轉向數位化照明設備,這種發展勢頭將持續下去。根據供應商的藍圖,邊緣人工智慧視覺感測器正被整合到照明設備中,從而實現自適應調光和情境察覺,預計這將提升其在公共安全方面的提案。在整個預測期內,智慧平台的成長速度預計將是前幾代的三倍,從而重新定義整個街道和道路照明產業的服務模式。
預計到2025年,LED將佔據83.55%的市場佔有率,並保持其主導地位至2031年,因為其發光效率略高於200 lm/W。作為螢光和高強度氣體放電燈(HID)替代品的特定應用領域,主要集中在工業區,目前仍處於等待預算調整的階段。波長590奈米的琥珀色LED燈在沿海地區越來越受歡迎,用於保護夜間活動的野生動物;而考慮到晝夜節律,暖白光在住宅也越來越受歡迎。受每流明成本下降和頻譜客製化技術進步的推動,基於LED的街道和道路照明市場預計將以6.52%的複合年成長率成長。
驅動IC的整合和散熱路徑的改進使額定壽命接近10萬小時,從而減少了燈具更換所需的服務次數。專用IC供應緊張仍然是一個瓶頸,高級調光控制器的交貨週期長達52週。儘管如此,多年框架協議和區域庫存中心正在幫助全球供應商緩解供應衝擊,並保持其在LED市場的中心地位。
區域分析
預計到2025年,亞太地區將佔全球銷售額的36.85%,並在2031年之前以6.12%的複合年成長率成長,這主要得益於中國、印度和東南亞國協的大規模都市化進程。在北京的低碳區,新型照明燈具正在整合空氣品質感測器;而在印度的「智慧城市計畫」中,LED照明標準化正在100個城市推進,從而推動了區域街道和道路照明市場的發展。在地化的製造能力正在縮短前置作業時間,並支持強力的補貼計劃,將投資回收期縮短至四年以內。
北美市場規模位居第二,並得到聯邦政府資助框架的支持,例如9.82億美元的「交通安全促進援助」(SS4A)機制,該機制為減少交通事故的照明項目撥款。紐約、波特蘭和洛杉磯的「零願景」(Vision Zero)行動計畫正在推動向自適應光學技術的轉型,以提高行人能見度。然而,由於電線杆基礎設施歸公共產業所有,協調方面面臨挑戰,LED照明的普及有時會被延誤。儘管如此,更嚴格的電氣安全標準和碳計量框架仍在不斷對落後的市政當局施加壓力。
儘管LED照明在歐洲的應用日趨成熟,但在歐盟綠色新政和EN-13201標準修訂的推動下,智慧控制升級仍在繼續。市政暗夜保護條例推動了對精密光學元件和超暖色溫(CCT)的需求,以減少光污染,從而支撐了街道和道路照明市場的平均售價(ASP)。斯堪地那維亞和德語區(德國、奧地利和瑞士)市場的創新津貼項目正在支持探索野生動物友好型頻譜和V2I(車路協同)走廊照明的先導計畫,為尋求出口機會的供應商提供了試驗平台。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速LED更換計劃
- 擴大連網/物聯網路燈的普及應用
- 政府強制措施和財政援助促進碳排放減少
- 新興國家智慧城市的快速發展
- 邊緣人工智慧自適應調光技術打造安全野生動物走廊
- C-V2X走廊中的車路協同(V2I)融合
- 市場限制因素
- 大規模轉型需要大量的初始資本投資
- 網路安全和資料隱私漏洞
- 公共產業與業主之間的利益衝突延緩了設備升級。
- LED驅動IC供應鏈波動
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依照明類型
- 傳統照明
- 智慧/互聯照明
- 透過光源
- LED
- 螢光
- 高亮度放電燈泡
- 報價
- 硬體
- 照明燈具和燈泡
- 照明設備
- 控制系統
- 軟體服務
- 硬體
- 按輸出功率範圍(瓦特)
- 小於 50 瓦
- 50~150 W
- 150瓦或以上
- 透過使用
- 高速公路
- 城市道路和市區道路
- 隧道和地下通道
- 停車場和公共區域
- 透過連接技術
- 有線(PLC、DALI、PoE)
- 無線技術(Zigbee、NB-IoT、LoRa、5G)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Signify NV
- OSRAM GmbH
- Current Lighting Solutions, LLC
- Wolfspeed Inc.(Cree LED)
- Acuity Brands Inc.
- Hubbell Inc.
- Zumtobel Group AG
- Schreder SA
- Eaton Corporation plc(Cooper Lighting Solutions)
- Valmont Industries Inc.
- Telensa Ltd.
- Silver Spring Networks Inc.
- Wipro Lighting(Wipro Enterprises)
- Nichia Corporation
- Dialight plc
- LED Roadway Lighting Ltd.
- Kingsun Optoelectronic Co.
- Syska LED Lights Pvt Ltd.
- DCD Technologies ME FZCO
- Itron Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the street and roadway lighting market size in 2026 is estimated at USD 10.63 billion, growing from 2025 value of USD 10.10 billion with 2031 projections showing USD 13.75 billion, growing at 5.28% CAGR over 2026-2031.
This report is Segmented by Lighting Type (Conventional, Smart/Connected), Light Source (LEDs, Fluorescent, HID), Offering (Hardware, Software/Services), Power Range (Below 50W, 50-150W, Above 150W), Application (Highways, Streets, Tunnels, Parking), Connectivity (Wired, Wireless), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Street And Roadway Lighting Market Trends and Insights
Accelerated LED Retrofit Programs
Municipal LED initiatives now bundle sensor networks, adaptive controls, and grid modernization objectives to unlock deeper carbon and O&M savings. New York Power Authority's Smart Street Lighting NY illustrates the model by folding demand-response and spectral tuning into LED upgrades. Ireland's EUR 17.5 million rural conversion plan likewise favors fixtures capable of future V2I communication, indicating that cities increasingly write "upgrade-ready" specifications. Financing tools, energy-service contracts, green bonds, and infrastructure funds are widening access and lowering lifecycle costs, expanding the addressable street and roadway lighting market.
Rising Deployment of Connected/IoT-Enabled Street Lights
Cities are moving from pilots to fleet-scale connected lighting roll-outs as the value of granular asset data becomes clear. Signify reported 144 million managed connected light points in 2024, demonstrating platform scalability. Low-power wide-area technologies like NB-IoT and LoRaWAN have cut connectivity costs, enabling secondary cities to embrace smart lighting. Copenhagen's 44,000-node network folds air-quality sensing into luminaires, creating new municipal revenue streams from environmental compliance analytics. This pivot from energy savings to data monetization raises switching barriers and lengthens vendor contracts, reinforcing long-term growth.
High Upfront Capex for Large-Scale Conversions
Total cost of ownership for connected systems can surpass USD 500 per fixture, triple a basic LED swap, forcing municipalities to seek ESCO financing or PPP structures that prolong procurement cycles by up to 18 months. Smaller cities without capital-improvement budgets face the sharpest squeeze, constraining immediate conversion volumes despite compelling long-term savings. Grant programs partially bridge the gap but often require detailed M&V documentation, adding an administrative burden that delays deployment.
Other drivers and restraints analyzed in the detailed report include:
- Government Carbon-Reduction Mandates and Funding
- Cyber-Security and Data-Privacy Vulnerabilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smart/connected solutions recorded a 6.82% CAGR outlook, yet conventional fixtures still comprised 56.15% of 2025 revenue. This coexistence underscores staggered asset-replacement cycles that keep legacy options viable for basic illumination. Metropolitan agencies deploy connected systems along priority corridors where data analytics can justify premium pricing, whereas smaller jurisdictions favor passive LED swaps with upgrade-ready nodes. The street and roadway lighting market benefits as both pathways steadily erode outdated high-intensity discharge stock. Signify's 144 million light-point footprint validates platform scalability while reinforcing vendor lock-in.
Momentum continues as standards bodies embed connectivity in future efficiency codes, redirecting capex toward digital luminaires. Vendor roadmaps show edge-AI vision sensors migrating onboard fixtures, promising adaptive dimming and situational awareness that elevate public-safety value propositions. Over the forecast horizon, smart platforms are expected to outpace conventional growth threefold, redefining service models in the wider street and roadway lighting industry.
LEDs captured 83.55% share in 2025 and will retain hegemony through 2031 as efficacy inches past 200 lm/W. Niche fluorescent and HID replacements linger primarily in industrial yards, awaiting budget cycles. Amber 590 nm packages are gaining coastal traction to safeguard nocturnal wildlife, while circadian-friendly warm whites appeal to residential precincts. The street and roadway lighting market size for LED-based systems is projected to compound at a 6.52% CAGR, supported by falling per-lumen costs and higher spectral customization.
Driver IC integration and improved thermal paths now push rated lifetimes toward 100,000 hours, reducing relamping truck rolls. Supply tightness in specialty ICs remains a bottleneck, with delivery times extending up to 52 weeks for advanced dimming controllers. Nevertheless, multiyear framework contracts and localized inventory hubs are helping global vendors buffer shocks, sustaining LED's centrality.
Complete Report Scope:
- By Lighting Type
- Conventional Lighting
- Smart / Connected Lighting
- By Light Source
- LEDs
- Fluorescent Lamps
- High-Intensity Discharge Lamps
- By Offering
- Hardware
- Lights and Bulbs
- Luminaires
- Control Systems
- Software and Services
- Hardware
- By Power Range (Wattage)
- Below 50 W
- 50 - 150 W
- Above 150 W
- By Application
- Highways
- Streets and Urban Roads
- Tunnels and Underpasses
- Parking and Public Areas
- By Connectivity Technology
- Wired (PLC, DALI, PoE)
- Wireless (Zigbee, NB-IoT, LoRa, 5G)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific commanded 36.85% of 2025 revenue and is poised for a 6.12% CAGR through 2031 on the back of large-scale urbanization in China, India, and ASEAN. Beijing's low-carbon districts embed air-quality sensors in new luminaires, while India's Smart Cities Mission is standardizing LED nodes across 100 municipalities, propelling the regional street and roadway lighting market. Local manufacturing capacity shortens lead times and underpins aggressive subsidy programs that compress payback periods below four years.
North America ranks second by value, buoyed by federal funding enclaves like the USD 982 million SS4A mechanism that earmarks lighting for crash-reduction projects. Vision Zero action plans in New York, Portland, and Los Angeles are shifting specifications toward adaptive optics that boost pedestrian visibility. Utilities' ownership of pole infrastructure, however, introduces alignment challenges that occasionally delay conversions. Still, rising electrical-safety standards and carbon accounting frameworks keep pressure on lagging jurisdictions.
Europe exhibits mature LED penetration yet continues to upgrade via smart controls driven by the EU Green Deal and EN-13201 revisions. Municipal dark-sky ordinances are fueling demand for precision optics and ultra-warm CCTs to curb light pollution, sustaining premium ASPs in the street and roadway lighting market. Innovation grants in Scandinavia and DACH markets sponsor pilot projects exploring wildlife-friendly spectra and V2I corridor lighting, providing test beds for vendors targeting export opportunities.
- Signify N.V.
- OSRAM GmbH
- Current Lighting Solutions, LLC
- Wolfspeed Inc. (Cree LED)
- Acuity Brands Inc.
- Hubbell Inc.
- Zumtobel Group AG
- Schreder S.A.
- Eaton Corporation plc (Cooper Lighting Solutions)
- Valmont Industries Inc.
- Telensa Ltd.
- Silver Spring Networks Inc.
- Wipro Lighting (Wipro Enterprises)
- Nichia Corporation
- Dialight plc
- LED Roadway Lighting Ltd.
- Kingsun Optoelectronic Co.
- Syska LED Lights Pvt Ltd.
- DCD Technologies ME FZCO
- Itron Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated LED retrofit programs
- 4.2.2 Rising deployment of connected/IoT-enabled street lights
- 4.2.3 Government carbon-reduction mandates and funding
- 4.2.4 Rapid smart-city roll-outs in emerging economies
- 4.2.5 Edge-AI adaptive dimming for wildlife-safe corridors
- 4.2.6 Vehicle-to-Infrastructure (V2I) integration for C-V2X corridors
- 4.3 Market Restraints
- 4.3.1 High upfront capex for large-scale conversions
- 4.3.2 Cyber-security and data-privacy vulnerabilities
- 4.3.3 Utility-ownership mis-alignment delaying upgrades
- 4.3.4 Supply-chain volatility in LED driver ICs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Threat of Substitutes
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Bargaining Power of Suppliers
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Lighting Type
- 5.1.1 Conventional Lighting
- 5.1.2 Smart / Connected Lighting
- 5.2 By Light Source
- 5.2.1 LEDs
- 5.2.2 Fluorescent Lamps
- 5.2.3 High-Intensity Discharge Lamps
- 5.3 By Offering
- 5.3.1 Hardware
- 5.3.1.1 Lights and Bulbs
- 5.3.1.2 Luminaires
- 5.3.1.3 Control Systems
- 5.3.2 Software and Services
- 5.3.1 Hardware
- 5.4 By Power Range (Wattage)
- 5.4.1 Below 50 W
- 5.4.2 50 - 150 W
- 5.4.3 Above 150 W
- 5.5 By Application
- 5.5.1 Highways
- 5.5.2 Streets and Urban Roads
- 5.5.3 Tunnels and Underpasses
- 5.5.4 Parking and Public Areas
- 5.6 By Connectivity Technology
- 5.6.1 Wired (PLC, DALI, PoE)
- 5.6.2 Wireless (Zigbee, NB-IoT, LoRa, 5G)
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 South Korea
- 5.7.4.4 India
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Signify N.V.
- 6.4.2 OSRAM GmbH
- 6.4.3 Current Lighting Solutions, LLC
- 6.4.4 Wolfspeed Inc. (Cree LED)
- 6.4.5 Acuity Brands Inc.
- 6.4.6 Hubbell Inc.
- 6.4.7 Zumtobel Group AG
- 6.4.8 Schreder S.A.
- 6.4.9 Eaton Corporation plc (Cooper Lighting Solutions)
- 6.4.10 Valmont Industries Inc.
- 6.4.11 Telensa Ltd.
- 6.4.12 Silver Spring Networks Inc.
- 6.4.13 Wipro Lighting (Wipro Enterprises)
- 6.4.14 Nichia Corporation
- 6.4.15 Dialight plc
- 6.4.16 LED Roadway Lighting Ltd.
- 6.4.17 Kingsun Optoelectronic Co.
- 6.4.18 Syska LED Lights Pvt Ltd.
- 6.4.19 DCD Technologies ME FZCO
- 6.4.20 Itron Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 歐洲路燈照明:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 LED路燈市場報告:按應用和地區分類(2026-2034)
 路燈燈具市場:按燈具類型、燈具類型、安裝類型、配電類型、應用、最終用戶分類,全球預測(2026-2032年)
 全球隧道照明市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球LED路燈市場報告2026年全球街道與道路照明市場報告
 街道和道路照明市場規模、佔有率和成長分析(按照明類型、安裝類型、電源、控制類型、最終用戶和地區分類)—2026-2033年產業預測北美街道照明:市場佔有率分析、行業趨勢和統計、成長預測(2025-2030 年)路燈及道路照明的全球市場規模:照明各類型,各來源,各瓦特數類型,各提供,各終端用戶產業,各地區,範圍及預測