


 |
市場調查報告書
商品編碼
2122701
汽車線束:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Automotive Wiring Harness - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
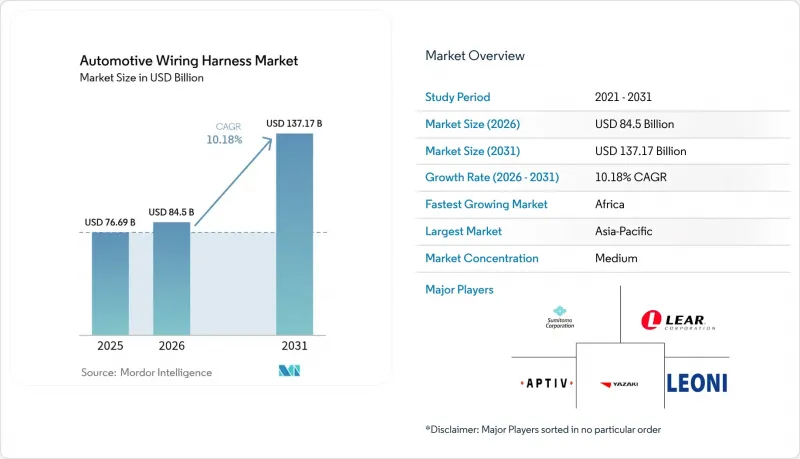
根據 Mordor Intelligence 估計,汽車線束市場在 2026 年的價值將達到 845 億美元,高於 2025 年的 766.9 億美元,預計到 2031 年將達到 1,371.7 億美元。
預計 2026 年至 2031 年的複合年成長率為 10.18%。
本報告按應用領域(點火系統、其他)、導體材料(銅、其他)、額定電壓(低壓(低於60V)、其他)、驅動類型(內燃機車輛、其他)、車輛類型(乘用車、其他)、配銷通路(OEM、其他)和地區進行細分。市場預測以價值(美元)和數量(單位)呈現。
全球汽車線束市場趨勢及洞察
高壓線束需求的激增是由電氣化所推動的。
隨著電池組電壓攀升至 800V 甚至 1000V,新型電纜組件的需求日益成長,它們不僅要滿足嚴格的電磁相容性 (EMC) 標準,還要承受更大的熱負載。許多中國品牌目前在其主傳動系統中指定使用鋁基導體,這表明材料創新如何直接轉化為電動車的成本降低。由於鋁材需要新的連接技術,供應商正以前所未有的速度投資摩擦焊接和雷射焊接設備。這帶來了一個新的視角:焊接技術可能很快就會取代銅材採購,成為一項重要的競爭障礙。
OEM廠商推廣輕量化鋁製光纖線束
汽車製造商持續追求極致輕量化,甚至在豪華車中,線束的重量可能超過20公斤。鋁導體不僅比銅導體輕約60%,還能降低銅價波動帶來的風險。雖然鋁導體的導電性較低,但多芯設計和雙金屬端子能夠將接觸電阻控制在規格範圍內,彌補了這一不足。隨著連接技術的日益成熟,一些原始設備製造商(OEM)正在推出混合導體線束,將鋁製電源線與光纖數據傳輸線相結合,這表明未來的發展方向並非單一金屬解決方案,而是混合複合材料線束。
銅和樹脂價格波動導致利潤率承壓
在傳統線束中,銅佔總組件成本的一半以上,而近期的價格波動正在擠壓供應商的毛利率。雖然大多數Line-Fit合約都包含價格轉嫁條款,但汽車製造商越來越不願意接受在生產週期中期提價。因此,供應商正透過在商品交易所進行避險或轉向鋁材等方式分散風險。這種情況凸顯出,在確保盈利,複雜的財務設計和籌資策略與核心工程技術同等重要。
細分市場分析
預計到2025年,汽車線束市場中,車身、照明和座艙舒適系統將佔最大佔有率,達到市場規模的35.35%。 LED燈、電動尾門和多區域自動空調模組的高普及率正在推動持續的需求。值得注意的是,這些提升銷售的舒適性設備也增加了車輛最終組裝的複雜性,因此汽車製造商需要預先配置的子線束,以便能夠直接安裝到儀表板和車門面板上。
預計到2031年,充電和電源系統線束將以25.44%的複合年成長率(CAGR)實現最高成長,並隨著電動車車型在展示室的增多,預計將保持15%左右的成長率。由於這些線束必須承受電池組周圍溫度的快速升高和機械振動,高等級的絕緣材料正逐漸成為主流。掌握液冷套管和超薄屏蔽技術的供應商可望獲得更高的售價。未來,高壓佈線的專業知識或可為向電池管理系統交叉銷售奠定基礎。
銅憑藉其無與倫比的導電性和百年製造經驗,仍佔據汽車線束市場約93.45%的佔有率。然而,其高密度和價格波動正迫使OEM採購部門考慮替代材料。一種新的趨勢正在引起關注:將銅數據線對和鋁電源線芯捆綁在同一條主幹線上,以在不影響訊號完整性的前提下減輕重量。
預計到2031年,鋁的複合年成長率將達到11.95%,輕鬆超過汽車線束產業的整體成長速度。耐腐蝕端子和摩擦焊接連接技術的進步緩解了以往的可靠性擔憂。由於鋁的價格比銅更穩定,財務部門擴大將其作為一種對沖工具。這種轉變表明,對於主要供應商而言,材料科學的選擇與財務風險管理策略直接相關。
區域分析
亞太地區佔了近48.40%的汽車線束市場佔有率,並擁有最高的絕對銷售成長率。中國憑藉其龐大的輕型汽車產量和強大的電動車供應鏈,在該地區扮演著核心角色;而日本和韓國則在數據和高壓應用領域貢獻了先進的研發成果。印度和東南亞各國政府為推動電氣化而採取的支持措施表明,即使全球經濟成長趨於正常化,該地區的需求仍將保持強勁。值得注意的是,多家中國汽車製造商正在向歐洲出口電動車,而歐洲市場對線束規範有著統一的要求,以滿足歐盟的監管標準,這使得亞洲供應商也能符合全球合規標準。
預計2026年至2031年間,非洲將達到11.79%的最高複合年成長率。具有競爭力的人事費用、透過與歐盟的貿易協定市場進入以及政府的工業園區計劃,正在推動線束領域的新投資。多家歐洲一級企業正將勞動密集型子組件的生產轉移到該地區,從而在其本地工廠引入自動化流程。針對電纜壓接和品質檢驗等領域的本地工人技能提升項目也正在湧現,這表明人力資本策略與區域成長密切相關。
儘管北美和歐洲的成長速度較慢,但它們仍然處於技術前沿。區域架構先導計畫主要集中在德國豪華品牌和北美電動車新創公司,慕尼黑、斯圖加特和矽谷的設計中心成為下一代線束概念的研發樞紐。這一趨勢表明,智慧財產權的創造正逐漸與勞動密集型生產脫鉤。這進一步強化了「兩極化的全球部署」格局,即研發叢集在原始設備製造商(OEM)總部附近形成,而大規模生產組裝流程則轉移到成本最優的地區。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場促進因素
- 高壓電纜需求激增,主要受電氣化推動(亞洲)
- OEM廠商推廣輕量化鋁製光纖線束
- 高階汽車向集中式區域電子電氣架構的過渡(歐盟)
- 美國、日本關於ADAS佈線冗餘的監管要求
- 加強對在地採購率的監管將促進線束的本地化生產(印度、墨西哥)。
- 透過開發自動駕駛汽車來推廣冗餘電路架構
- 市場限制因素
- 銅和樹脂價格波動導致利潤率承壓
- 由於電動車特有的熱設計和電磁相容性挑戰,檢驗成本增加。
- 設計複雜性與熟練勞動力供應不符(東協)
- 製造自動化的限制阻礙了生產力的提高
- 價值供應鏈分析
- 監管和技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 透過使用
- 點火系統
- 充電和電源系統
- 傳動系統/動力傳動系統(內燃機)
- 高壓牽引線束(xEV)
- 資訊娛樂系統、駕駛座、車載資訊系統
- ADAS和安全控制
- 車身、照明、內裝舒適性
- 按導體材料
- 銅
- 鋁
- 按額定電壓
- 低電壓(低於60V)
- 高壓(60-1000V)
- 依推進類型
- 內燃機車
- 電池式電動車
- 插電式混合動力汽車和混合動力汽車
- 按車輛類型
- 搭乘用車
- 輕型商用車
- 大型卡車和巴士
- 透過分銷管道
- OEM
- 售後市場
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東
- GCC
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
- 北美洲
第6章 競爭情勢
- Strategic Initiatives
- 市佔率分析
- 公司簡介
- Yazaki Corporation
- Sumitomo Electric Industries Ltd.
- LEONI AG
- Lear Corporation
- Motherson Wiring Harness Ltd.
- Furukawa Electric Co. Ltd.
- Fujikura Ltd.
- Kyungshin Corporation
- Draexlmaier Group
- Kromberg & Schubert
- Nexans Autoelectric
- PKC Group(Motherson)
- Coroplast Fritz Muller GmbH & Co.
- THB Group
- Prestolite Wire LLC
- 李爾揚州(中國)
- Guangdong Hivolt Wiring Harness
- BizLink Holding Inc.
- Shanghai Shenglong Automotive Harness
- Samvardhana Motherson Reydel
- Korea Electric Terminal Co.
第7章 市場機會與未來展望
According to Mordor Intelligence, automotive wiring harness market size in 2026 is estimated at USD 84.5 billion, growing from 2025 value of USD 76.69 billion with 2031 projections showing USD 137.17 billion, growing at 10.18% CAGR over 2026-2031.
This report is Segmented by Application Type (Ignition System, and More), Conductor Material (Copper, and More), Voltage Rating (Low-Voltage [less Than 60V] and More), Propulsion Type (Internal Combustion Engine Vehicles and More), Vehicle Type (Passenger Cars and More), Sales Channel (OEM and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Wiring Harness Market Trends and Insights
Electrification-Driven Surge in High-Voltage Harness Demand
Rising battery pack voltages to 800 V and even 1000 V are spurring a new class of cable assemblies that carry greater thermal loads while meeting tight electromagnetic-compatibility (EMC) targets. Many Chinese brands now specify aluminum-based conductors for main traction lines, directly linking material innovation to EV cost reduction. Because aluminum requires revised joining techniques, suppliers are investing in friction and laser welding cells at a pace unseen five years ago. An emerging inference is that welding know-how may soon overshadow raw copper sourcing as the key competitive barrier.
OEM Push for Lightweight Aluminum and Optical Harnesses
Automakers continue to chase every gram of weight saving, and wiring can account for more than 20 kg in premium cars. Aluminum conductors slash mass by roughly 60% relative to copper and also cut exposure to copper-price swings. The downside-lower conductivity-is being offset through multi-strand designs and bimetal terminals that keep contact resistance within specification. As connection technology matures, several OEMs have introduced mixed conductor looms that pair aluminum power lines with optical fibres for data, hinting that the next frontier will lie in hybrid composite bundles rather than single-metal solutions.
Margin Pressure from Volatile Copper and Resin Prices
Copper accounts for well over half of total bill-of-materials cost in a conventional loom, so recent price gyrations have compressed supplier gross margin. Although most line-fit contracts include pass-through clauses, automakers are increasingly reluctant to accept mid-cycle price increases. Suppliers are therefore hedging on commodity exchanges and diversifying into aluminum as a risk-spreading measure. The situation underscores that financial engineering and procurement sophistication are becoming as important as core engineering in safeguarding profitability.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Centralized Zonal E/E Architectures in Premium Cars
- Regulatory Mandates for ADAS Wiring Redundancy
- EV-Specific Thermal and EMC Challenges Raising Validation Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Body, Lighting, and Cabin Comfort systems command the largest share of the Automotive Wiring Harness market size in 2025, accounting for 35.35% of the market size. High LED adoption, power lift-gates, and multi-zone climate modules explain persistent demand. An interesting observation is that the same comfort features that boost volume also complicate final vehicle assembly, nudging OEMs to request pre-configured sub-looms that snap into dashboards and door panels.
Charging and power supply system harnesses show the fastest forecast CAGR expanding at an 25.44% through 2031, expanding in the mid-teens as more electric models reach showrooms. These harnesses must endure temperature spikes and mechanical vibration around battery packs, so higher-grade insulation materials are becoming mainstream. Suppliers that master liquid-cooling sleeves and low-profile shielding will likely command premium price points. Over time, expertise in high-voltage routing may provide cross-selling entry into battery management systems.
Copper retains around 93.45% of the Automotive Wiring Harness market share today, supported by unmatched conductivity and a century of process know-how. Yet its density and volatile cost profile keep pressure on OEM purchasing departments to pursue alternatives. An emerging pattern is the bundling of copper data pairs with aluminum power cores in the same trunk line, achieving weight reduction without sacrificing signal integrity.
Aluminum's forecast CAGR is 11.95% by 2031, easily outpacing the broader Automotive Wiring Harness industry trajectory. Advances in anti-corrosion terminals and friction-weld splice techniques have removed earlier reliability concerns. Because aluminum is price-stable relative to copper, finance teams increasingly model its use as a hedge. The shift indicates that material science choices now intersect directly with treasury risk management strategies inside large suppliers.
Complete Report Scope:
- By Application
- Ignition System
- Charging & Power Supply System
- Drivetrain & Powertrain (ICE)
- High-Voltage Traction Harness (xEV)
- Infotainment, Cockpit & Telematics
- ADAS & Safety Control
- Body, Lighting & Cabin Comfort
- By Conductor Material
- Copper
- Aluminum
- By Voltage Rating
- Low-Voltage (<60 V)
- High-Voltage (60-1,000 V)
- By Propulsion Type
- Internal Combustion Engine Vehicles
- Battery Electric Vehicles
- Plug-in Hybrid & Hybrid Vehicles
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy-duty Trucks & Buses
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia Pacific holds almost 48.40% Automotive Wiring Harness market share and boasts the fastest absolute revenue expansion. China anchors the region through its vast light-vehicle output and deep EV supply chains, while Japan and South Korea contribute high-grade R&D for data and high-voltage applications. Government incentives for electrification in India and Southeast Asia suggest that regional demand will remain resilient even as global growth normalises. A noteworthy development is that multiple Chinese OEMs are exporting EVs to Europe, requiring harmonised wiring specifications that meet European Union regulatory norms and thus elevating Asia-based suppliers to global compliance standards.
Africa, records the highest CAGR of 11.79% between 2026-2031. Competitive labour costs, trade-agreement access to the European Union, and government industrial-park policies together attract fresh harness investment. Several European tier-1 firms are locating high-labour-content sub-assemblies in the region, freeing up home-market plants for automated processes. Local workforce up-skilling programs in cable crimping and quality inspection are emerging, indicating that human-capital strategy is entwined with regional growth.
North America and Europe grow more modestly but remain technology front-runners. Zonal architecture pilots are concentrated in German luxury brands and North American electric start-ups, so design offices in Munich, Stuttgart, and Silicon Valley serve as nerve centres for next-generation loom concepts. This pattern implies that intellectual property creation is decoupling from labour-intensive production. This reinforces the two-speed global footprint in which R&D clusters near OEM headquarters and large-batch assembly migrate to cost-optimised regions.
- Yazaki Corporation
- Sumitomo Electric Industries Ltd.
- LEONI AG
- Lear Corporation
- Motherson Wiring Harness Ltd.
- Furukawa Electric Co. Ltd.
- Fujikura Ltd.
- Kyungshin Corporation
- Draexlmaier Group
- Kromberg & Schubert
- Nexans Autoelectric
- PKC Group (Motherson)
- Coroplast Fritz Muller GmbH & Co.
- THB Group
- Prestolite Wire LLC
- Lear Yangzhou (China)
- Guangdong Hivolt Wiring Harness
- BizLink Holding Inc.
- Shanghai Shenglong Automotive Harness
- Samvardhana Motherson Reydel
- Korea Electric Terminal Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 Electrification-Driven Surge in High-Voltage Harness Demand (Asia)
- 4.1.2 OEM Push for Lightweight Aluminum & Optical Harnesses
- 4.1.3 Shift Toward Centralized Zonal E/E Architectures in Premium Cars (EU)
- 4.1.4 Regulatory Mandates for ADAS Wiring Redundancy (US, Japan)
- 4.1.5 Rising Local Content Rules Fueling Wire-Harness Localization (India, Mexico)
- 4.1.6 Autonomous Vehicle Development Driving Redundant Circuit Architectures
- 4.2 Market Restraints
- 4.2.1 Margin Pressure From Volatile Copper & Resin Prices
- 4.2.2 EV-Specific Thermal & EMC Challenges Raising Validation Costs
- 4.2.3 Mismatch Between Design Complexity & Skilled Labor Availability (ASEAN)
- 4.2.4 Manufacturing Automation Limitations Constraining Productivity Gains
- 4.3 Value / Supply-Chain Analysis
- 4.4 Regulatory & Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Application
- 5.1.1 Ignition System
- 5.1.2 Charging & Power Supply System
- 5.1.3 Drivetrain & Powertrain (ICE)
- 5.1.4 High-Voltage Traction Harness (xEV)
- 5.1.5 Infotainment, Cockpit & Telematics
- 5.1.6 ADAS & Safety Control
- 5.1.7 Body, Lighting & Cabin Comfort
- 5.2 By Conductor Material
- 5.2.1 Copper
- 5.2.2 Aluminum
- 5.3 By Voltage Rating
- 5.3.1 Low-Voltage (<60 V)
- 5.3.2 High-Voltage (60-1,000 V)
- 5.4 By Propulsion Type
- 5.4.1 Internal Combustion Engine Vehicles
- 5.4.2 Battery Electric Vehicles
- 5.4.3 Plug-in Hybrid & Hybrid Vehicles
- 5.5 By Vehicle Type
- 5.5.1 Passenger Cars
- 5.5.2 Light Commercial Vehicles
- 5.5.3 Heavy-duty Trucks & Buses
- 5.6 By Sales Channel
- 5.6.1 OEM
- 5.6.2 Aftermarket
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Spain
- 5.7.2.5 Russia
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia Pacific
- 5.7.4 Middle East
- 5.7.4.1 GCC
- 5.7.4.2 Turkey
- 5.7.4.3 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Strategic Initiatives
- 6.2 Market Share Analysis
- 6.3 Company Profiles
- 6.3.1 Yazaki Corporation
- 6.3.2 Sumitomo Electric Industries Ltd.
- 6.3.3 LEONI AG
- 6.3.4 Lear Corporation
- 6.3.5 Motherson Wiring Harness Ltd.
- 6.3.6 Furukawa Electric Co. Ltd.
- 6.3.7 Fujikura Ltd.
- 6.3.8 Kyungshin Corporation
- 6.3.9 Draexlmaier Group
- 6.3.10 Kromberg & Schubert
- 6.3.11 Nexans Autoelectric
- 6.3.12 PKC Group (Motherson)
- 6.3.13 Coroplast Fritz Muller GmbH & Co.
- 6.3.14 THB Group
- 6.3.15 Prestolite Wire LLC
- 6.3.16 Lear Yangzhou (China)
- 6.3.17 Guangdong Hivolt Wiring Harness
- 6.3.18 BizLink Holding Inc.
- 6.3.19 Shanghai Shenglong Automotive Harness
- 6.3.20 Samvardhana Motherson Reydel
- 6.3.21 Korea Electric Terminal Co.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 汽車高壓線束市場:全球市場預測,2026-2032年汽車線束市場-2026-2032年全球市場預測汽車二次線束市場:2026-2032年全球市場預測(依線束類型、車輛類型、電壓等級、組件類型、材質與應用分類)
 汽車線束市場分析及預測(至2035年):類型、產品類型、技術、組件、應用、材料類型、製造流程、最終用戶、功能、安裝方式
 汽車線束市場機會、成長促進因素、產業趨勢分析及2026-2035年預測汽車線束系統市場分析及預測(至2035年):依類型、產品、技術、組件、應用、材料類型、最終用戶、功能及安裝類型分類
 全球汽車線束市場:按類型和應用、變速箱類型、材料類型、變速箱速度、應用、電壓、內燃機 (ICE)、車輛類型和應用、組件、類別和地區分類 - 預測至 2033 年
 汽車線束系統市場規模、佔有率和成長分析:按組件、線束類型、材質、車輛類型、銷售管道和地區分類-2026-2033年產業預測
 汽車線束市場:按組件、材質、驅動系統和地區分類
 汽車線束市場規模、佔有率和成長分析:按導體材料、驅動系統、銷售管道、應用和地區分類-2026-2033年產業預測