


 |
市場調查報告書
商品編碼
2083311
汽車線束市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Automotive Wiring Harness Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球汽車線束市場預計到 2025 年將達到 712 億美元,年複合成長率為 5.7%,到 2035 年將達到 1,231 億美元。
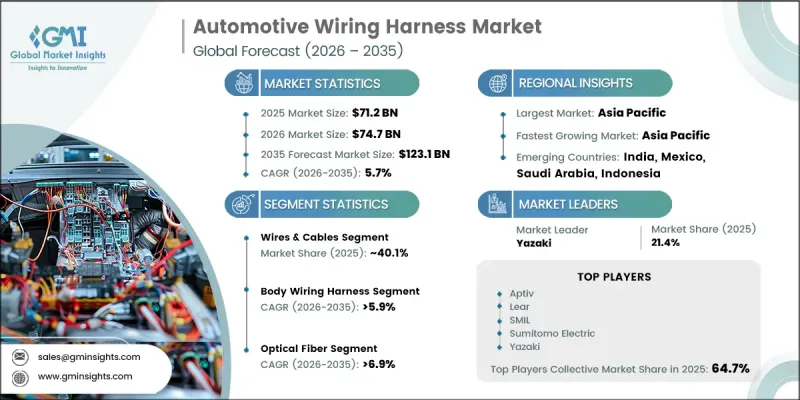
受全球向電動車 (EV) 和混合動力汽車所需的電氣架構遠比傳統內燃機汽車複雜得多。高壓電池系統、電動動力總成和車載充電組件的日益普及,顯著提升了對能夠高效傳輸高能量且損耗最小的先進線束解決方案的需求。同時,更嚴格的排放氣體法規和政府主導的電動車基礎設施投資,正加速各大汽車市場的車輛電氣化。高級駕駛輔助系統 (ADAS) 的日益整合,進一步增加了電氣系統的複雜性,因為現代汽車高度依賴感測器、攝影機、雷達和雷射雷達 (LiDAR) 技術,這些技術需要高速數據傳輸和可靠的電力分配。此外,消費者對更高安全性、互聯性和自動化程度的期望不斷提高,促使汽車製造商將更多電子系統整合到各種汽車平臺中。這些因素共同推動了汽車線束市場的長期成長前景。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 712億美元 |
| 預測金額 | 1231億美元 |
| 複合年成長率 | 5.7% |
預計到2025年,電線電纜市佔率將達到40.1%,並在2035年之前以5.8%的複合年成長率成長。該細分市場之所以能保持主導地位,是因為其在實現多個車輛系統之間的電氣連接方面發揮著至關重要的作用。電線電纜對於在關鍵汽車零件之間傳輸電力和訊號至關重要,這些零件支援諸如動力系統、照明系統、資訊娛樂系統、安全系統和連接模組等功能。隨著車輛電氣化程度的提高以及現代汽車電子化程度的增加,對高性能線束解決方案的需求持續成長。
預計到2025年,汽車線束市佔率將達到24.7%,並在2026年至2035年間以5.9%的複合年成長率成長。該細分市場在支援整車電氣功能方面發揮著至關重要的作用,這些功能包括照明、車窗、後視鏡、鎖定機構、座椅系統和雨刷控制等。消費者對更舒適、便利和安全性的需求不斷成長,推動了乘用車和商用車線束系統複雜性和應用範圍的顯著提升。車輛內外電子元件的日益整合也進一步促進了該細分市場的成長。
中國汽車線束市場佔全球64.2%的佔有率,預計2025年市場規模將達到215億美元。中國作為全球最大的汽車製造地,其地位以及電動車生產的快速擴張,有力地支撐了中國市場的成長。眾多整車廠商和零件供應商的存在,推動了對低壓和高壓線束系統的強勁需求。此外,聯網汽車技術、高階駕駛輔助系統(ADAS)和軟體定義汽車(SDV)平台的日益普及,也進一步加速了市場成長。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 車輛電氣化進程
- ADAS的廣泛應用
- 每台設備可安裝的電子設備數量增加
- 聯網汽車技術的擴展
- 產業潛在風險與挑戰
- 銅和鋁價格波動劇烈
- 勞力密集型製造程序
- 市場機遇
- 電動車的成長帶動了對高壓線束的需求。
- 軟體定義車輛(SDVS)的普及
- 汽車乙太網路和數據線束的成長
- 在地化和近岸外包計劃
- 成長促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監管指南
- 北美洲
- 美國:FMVSS電氣安全標準與NHTSA汽車電氣系統法規
- 加拿大:CMVSS汽車電氣安全法規與電動車合規框架
- 歐洲
- 德國:UNECE R100 電動車安全法規與 VDA 電氣系統標準
- 英國:英國車輛類型認證(WVTA)電氣安全法規
- 法國:歐盟 REACH 法規及報廢車輛 (ELV)法令遵循
- 義大利:ISO 26262 功能安全標準與聯合國歐洲經濟委員會網路安全法規
- 亞太地區
- 中國:GB 18384《電動車安全規程與高壓電纜標準》
- 印度:AIS-038電動車安全標準和AIS-156電池安全法規
- 日本:JASO汽車線束標準與國土交通省汽車安全法規
- 韓國:KMVSS電氣安全標準與電動車法令遵循
- 澳洲:澳洲設計規則(ADR)車輛電氣安全標準
- 拉丁美洲
- 巴西:CONTRAN的汽車電氣安全法規和INMETRO認證標準
- 墨西哥:NOM汽車電氣安全標準與車輛合規法規
- 阿根廷:國內汽車電氣安全標準與汽車合規框架
- 中東和非洲
- 阿拉伯聯合大公國:海灣合作理事會汽車安全法規與阿拉伯聯合大公國電動車合規框架
- 沙烏地阿拉伯:SASO法律規範
- 南非:《國家道路交通法》下的車輛安全標準和SABS電氣合規法規
- 北美洲
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 成本細分分析
- 專利趨勢
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 汽車生產及線束需求分析
- 全球汽車生產趨勢及產量預測(2026-2035年)
- 全球汽車產量與線束需求之間的相關性
- 依車輛類型分類的線束容量和消耗量(線束長度、重量、複雜度指數)
- 電動車產量增加對線束消耗的影響
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 層級定位矩陣:依收入、地區和創新能力分類
第5章 市場估計與預測:依組件分類,2022-2035年
- 電線電纜
- 低壓電力線(低於60V)
- 高壓輸電線路(60V以上)
- 連接器
- 終端
- 壓接端子
- 絕緣位移端子
- 其他
- 繼電器
- 電磁繼電器
- 固態繼電器
- 保險絲
- 刀片保險絲
- 高壓保險絲
- 其他
- 保護套管
- 波形導管
- 編織袖子
- 熱縮管
- 其他
- 其他
第6章 市場估算與預測:依產品分類,2022-2035年
- 引擎線束
- 內燃機線束
- 馬達管理線束
- 車身線束
- 門窗線束
- 車頂/天窗線束
- 外部車身模組線束
- 底盤線束
- HVAC線束
- 儀表板/駕駛室線束
- 電池和高壓線束
- 驅動電池線束
- 電池管理系統(BMS)線束
- 充電系統線束
- 高壓互連線束
- 照明線束
- 外部照明線束
- 車內照明線束
- 其他
第7章 市場估計與預測:依應用領域分類,2022-2035年
- ADAS和自動駕駛
- 連接與通訊
- 資訊娛樂
- 其他
第8章 市場估算與預測:依連接器類型分類,2022-2035年
- 電線連接器
- 閉型
- 非密封型
- 線對板連接器
- 閉型
- 非密封型
- 基板間連接器
- 高速數據連接器
- 高壓連接器
- 射頻/同軸連接器
- 其他
第9章 市場估算與預測:依材料類型分類,2022-2035年
- 金屬導體
- 銅
- 鋁
- 銅包鋁(CCA)
- 其他特殊金屬
- 光纖
- 塑膠光纖(POF)
- 玻璃光纖(GOF)
第10章 市場估計與預測:依促進因素分類,2022-2035年
- ICE
- 電的
- 混合
第11章 市場估價與預測:依車輛類型分類,2022-2035年
- 搭乘用車
- 轎車和掀背車
- SUV 與跨界車
- 高級轎車和豪華轎車
- 商用車輛
- 輕型商用車(LCV)
- 中型商用車(MCV)
- 重型商用車(HCV)
- 摩托車
- 摩托車
- 電動摩托車
第12章 市場估算與預測:依銷售管道分類,2022-2035年
- OEM
- 後果
第13章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 比利時
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 紐西蘭
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第14章:公司簡介
- 世界公司
- Amphenol
- Aptiv
- Fujikura
- Furukawa Electric
- Lear Corporation
- LEONI
- Molex LLC
- Sumitomo Electric
- TE Connectivity
- Yazaki Corporation
- 本地公司
- COFICAB Group
- Draxlmaier Group
- KS Terminals Inc.(KST)
- Kyungshin Corporation
- Nexans Autoelectric
- Samvardhana Motherson International(SMIL)
- Spark Minda(Minda Industries Ltd.)
- 新興企業
- BizLink Holding
- Luxshare Precision Industry
- Rosenberger Hochfrequenztechnik
The Global Automotive Wiring Harness Market was valued at USD 71.2 billion in 2025 and is estimated to grow at a CAGR of 5.7% to reach USD 123.1 billion by 2035.
The automotive wiring harness market is witnessing steady expansion driven by the global shift toward electric and hybrid vehicles, which require significantly more complex electrical architectures than conventional internal combustion engine vehicles. Increased adoption of high-voltage battery systems, electric drivetrains, and onboard charging components is substantially raising demand for advanced wiring harness solutions capable of efficient high-energy transmission with minimal losses. In parallel, tightening emission regulations and government-backed investments in electric mobility infrastructure are accelerating vehicle electrification across major automotive markets. The growing integration of advanced driver assistance systems is further increasing electrical complexity, as modern vehicles rely heavily on sensors, cameras, radar, and LiDAR technologies that require high-speed data transfer and reliable power distribution. Rising consumer expectations for enhanced safety, connectivity, and automation features are also pushing automakers to incorporate more electronic systems across vehicle platforms. Collectively, these factors are reinforcing long-term growth prospects for the automotive wiring harness market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $71.2 Billion |
| Forecast Value | $123.1 Billion |
| CAGR | 5.7% |
The wires and cables segment accounted for 40.1% share in 2025 and is expected to grow at a CAGR of 5.8% through 2035. This segment maintains its leading position due to its critical role in enabling electrical connectivity across multiple vehicle systems. Wires and cables are essential for transmitting power and signals between key automotive components, supporting functions such as propulsion, lighting, infotainment, safety systems, and connectivity modules. Increasing vehicle electrification and rising electronic content in modern automobiles are driving sustained demand for high-performance wiring solutions.
The body wiring harness segment held 24.7% in 2025 and is projected to grow at a CAGR of 5.9% during 2026-2035. This segment plays a vital role in supporting electrical functions across vehicle body systems, including lighting, windows, mirrors, locking mechanisms, seating systems, and wiper controls. Growing consumer demand for enhanced comfort, convenience, and safety features is significantly increasing the complexity and adoption of body wiring harness systems across passenger and commercial vehicles. Rising integration of electronic components across vehicle interiors and exteriors is further strengthening segment growth.
China Automotive Wiring Harness Market held 64.2% share, generating USD 21.5 billion in 2025. Market growth in the country is strongly supported by its position as the world's largest automotive manufacturing hub and the rapid expansion of electric vehicle production. The presence of many OEMs and component suppliers is driving strong demand for both low-voltage and high-voltage wiring harness systems. In addition, increasing adoption of connected vehicle technologies, advanced driver assistance systems, and software-defined vehicle platforms is further accelerating market expansion.
Major companies operating in the global automotive wiring harness market include Aptiv, Sumitomo Electric, Furukawa Electric, LEONI, Lear, SMIL, and Yazaki (reaffirmed global leadership presence across major OEM supply chains). Companies operating in the automotive wiring harness market are strengthening their market position by investing in lightweight materials, high-voltage capable designs, and advanced thermal-resistant wiring technologies to support electric vehicle platforms. Manufacturers are expanding production capacities and establishing localized manufacturing facilities to improve supply chain efficiency and reduce lead times. Strategic collaborations with automotive OEMs are enabling co-development of customized wiring architectures tailored for electric and autonomous vehicles. Firms are also focusing on automation in manufacturing processes to enhance precision, reduce costs, and improve scalability.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast Model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Product
- 2.2.4 Application
- 2.2.5 Connector type
- 2.2.6 Material type
- 2.2.7 Propulsion
- 2.2.8 Vehicle
- 2.2.9 Sales channel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising vehicle electrification
- 3.2.1.2 Increasing ADAS adoption
- 3.2.1.3 Growing electronic content per vehicle
- 3.2.1.4 Expansion of connected vehicle technologies
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Volatile copper and aluminum prices
- 3.2.2.2 Labor-intensive manufacturing process
- 3.2.3 Market opportunities
- 3.2.3.1 High-voltage harness demand from ev growth
- 3.2.3.2 Expansion of software-defined vehicles (SDVS)
- 3.2.3.3 Growth of automotive ethernet & data harnesses
- 3.2.3.4 Localization and near-shoring initiatives
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory guideline
- 3.6.1 North America
- 3.6.1.1 U.S.: FMVSS Electrical Safety Standards & NHTSA Vehicle Electrical System Regulations
- 3.6.1.2 Canada: CMVSS Vehicle Electrical Safety Regulations & EV Compliance Framework
- 3.6.2 Europe
- 3.6.2.1 Germany: UNECE R100 Electric Vehicle Safety Regulations & VDA Electrical System Standards
- 3.6.2.2 UK: UK Whole Vehicle Type Approval (WVTA) Electrical Safety Regulations
- 3.6.2.3 France: EU REACH & End-of-Life Vehicle (ELV) Compliance Regulations
- 3.6.2.4 Italy: ISO 26262 Functional Safety Standards & UNECE Cybersecurity Regulations
- 3.6.3 Asia Pacific
- 3.6.3.1 China: GB 18384 Electric Vehicle Safety Regulations & High-Voltage Cable Standards
- 3.6.3.2 India: AIS-038 EV Safety Standards & AIS-156 Battery Safety Regulations
- 3.6.3.3 Japan: JASO Automotive Wiring Standards & MLIT Vehicle Safety Regulations
- 3.6.3.4 South Korea: KMVSS Electrical Safety Standards & EV Compliance Regulations
- 3.6.3.5 Australia: Australian Design Rules (ADR) Vehicle Electrical Safety Standards
- 3.6.4 Latin America
- 3.6.4.1 Brazil: CONTRAN Vehicle Electrical Safety Regulations & INMETRO Certification Standards
- 3.6.4.2 Mexico: NOM Automotive Electrical Safety Standards & Vehicle Compliance Regulations
- 3.6.4.3 Argentina: National Vehicle Electrical Safety Standards & Automotive Compliance Framework
- 3.6.5 MEA
- 3.6.5.1 UAE: GCC Vehicle Safety Regulations & UAE EV Compliance Framework
- 3.6.5.2 Saudi Arabia: SASO Vehicle Electrical Safety Standards & EV Regulatory Framework
- 3.6.5.3 South Africa: National Road Traffic Act Vehicle Safety Standards & SABS Electrical Compliance Regulations
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Trade data analysis (Driven by Paid Research)
- 3.9.1 Import/export volume & value trends
- 3.9.2 Key trade corridors & tariff impact
- 3.10 Cost breakdown analysis
- 3.11 Patent Landscape (Driven by Primary Research)
- 3.12 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.12.1 AI-Driven Disruption of Existing Business Models
- 3.12.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.12.3 Risks, Limitations & Regulatory Considerations
- 3.13 Capacity & production landscape (Driven by Primary Research)
- 3.13.1 Installed capacity by region & key producer
- 3.13.2 Capacity utilization rates & expansion pipelines
- 3.14 Vehicle production & harness demand analysis
- 3.14.1 Global vehicle production trends & output forecasts (2026-2035)
- 3.14.2 Wiring harness demand correlation with global vehicle production volumes
- 3.14.3 Harness content & consumption per vehicle type (wiring length, weight, complexity index)
- 3.14.4 Ev production ramp-up impact on harness consumption
- 3.15 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.15.1 Base Case - Key Macro & Industry Variables Driving CAGR
- 3.15.2 Optimistic Scenarios - Favourable macro and industry tailwinds
- 3.15.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company Tier Benchmarking
- 4.6.1 Tier Classification Criteria & Qualifying Thresholds
- 4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Bn, Units)
- 5.1 Key trends
- 5.2 Wires & cables
- 5.2.1 Low-voltage wires (<60V)
- 5.2.2 High-voltage wires (>60V)
- 5.3 Connectors
- 5.4 Terminals
- 5.4.1 Crimp terminals
- 5.4.2 Insulation displacement terminals
- 5.4.3 Others
- 5.5 Relays
- 5.5.1 Electromagnetic relays
- 5.5.2 Solid-state relays
- 5.6 Fuses
- 5.6.1 Blade fuses
- 5.6.2 High-voltage fuses
- 5.6.3 Others
- 5.7 Protective sleeves & conduits
- 5.7.1 Corrugated conduits
- 5.7.2 Braided sleeves
- 5.7.3 Heat shrink tubing
- 5.7.4 Others
- 5.8 Others
Chapter 6 Market Estimates & Forecast, By Product, 2022 - 2035 ($Bn, Units)
- 6.1 Key trends
- 6.2 Engine wiring harness
- 6.2.1 ICE engine harness
- 6.2.2 Electric motor management harness
- 6.3 Body wiring harness
- 6.3.1 Door & window harness
- 6.3.2 Roof & sunroof harness
- 6.3.3 Exterior body module harness
- 6.4 Chassis wiring harness
- 6.5 HVAC wiring harness
- 6.6 Dashboard/cabin wiring harness
- 6.7 Battery & high-voltage wiring harness
- 6.7.1 Traction battery harness
- 6.7.2 Battery management system (BMS) harness
- 6.7.3 Charging system harness
- 6.7.4 HV inter-connected harness
- 6.8 Lighting wiring harness
- 6.8.1 Exterior lighting harness
- 6.8.2 Interior lighting harness
- 6.9 Others
Chapter 7 Market Estimates & Forecast, By Application, 2022 - 2035 ($Bn, Units)
- 7.1 Key trends
- 7.2 ADAS & autonomous driving
- 7.3 Connectivity & communication
- 7.4 Infotainment & entertainment
- 7.5 Others
Chapter 8 Market Estimates & Forecast, By Connector Type, 2022 - 2035 ($Bn, Units)
- 8.1 Key trends
- 8.2 Wire-to-wire connectors
- 8.2.1 Sealed
- 8.2.2 Unsealed
- 8.3 Wire-to-board connectors
- 8.3.1 Sealed
- 8.3.2 Unsealed
- 8.4 Board-to-board connectors
- 8.5 High-speed data connectors
- 8.6 High-voltage connectors
- 8.7 RF/coaxial connectors
- 8.8 Others
Chapter 9 Market Estimates & Forecast, By Material Type, 2022 - 2035 ($Bn, Units)
- 9.1 Key trends
- 9.2 Metallic conductors
- 9.2.1 Copper
- 9.2.2 Aluminum
- 9.2.3 Copper-clad aluminum (CCA)
- 9.2.4 Other specialty metals
- 9.3 Optical fiber
- 9.3.1 Plastic optical fiber (POF)
- 9.3.2 Glass optical fiber (GOF)
Chapter 10 Market Estimates & Forecast, By Propulsion, 2022 - 2035 ($Bn, Units)
- 10.1 Key trends
- 10.2 ICE
- 10.3 Electric
- 10.4 Hybrid
Chapter 11 Market Estimates & Forecast, By Vehicle, 2022 - 2035 ($Bn, Units)
- 11.1 Key trends
- 11.2 Passenger cars
- 11.2.1 Sedans & hatchbacks
- 11.2.2 SUVs & crossovers
- 11.2.3 Premium & luxury vehicles
- 11.3 Commercial vehicles
- 11.3.1 Light commercial vehicles (LCV)
- 11.3.2 Medium commercial vehicles (MCV)
- 11.3.3 Heavy commercial vehicles (HCV)
- 11.4 Two-wheelers
- 11.4.1 Motorcycles
- 11.4.2 Electric two-wheelers
Chapter 12 Market Estimates & Forecast, By Sales Channel, 2022 - 2035 ($Bn, Units)
- 12.1 Key trends
- 12.2 OEM
- 12.3 Aftermath
Chapter 13 Market Estimates & Forecast, By Region, 2022 - 2035 ($Bn, Units)
- 13.1 Key trends
- 13.2 North America
- 13.2.1 US
- 13.2.2 Canada
- 13.3 Europe
- 13.3.1 Germany
- 13.3.2 UK
- 13.3.3 France
- 13.3.4 Italy
- 13.3.5 Spain
- 13.3.6 Russia
- 13.3.7 Netherlands
- 13.3.8 Belgium
- 13.4 Asia Pacific
- 13.4.1 China
- 13.4.2 India
- 13.4.3 Japan
- 13.4.4 Australia
- 13.4.5 South Korea
- 13.4.6 New Zealand
- 13.5 Latin America
- 13.5.1 Brazil
- 13.5.2 Mexico
- 13.5.3 Argentina
- 13.6 MEA
- 13.6.1 South Africa
- 13.6.2 Saudi Arabia
- 13.6.3 UAE
Chapter 14 Company Profiles
- 14.1 Global Players
- 14.1.1 Amphenol
- 14.1.2 Aptiv
- 14.1.3 Fujikura
- 14.1.4 Furukawa Electric
- 14.1.5 Lear Corporation
- 14.1.6 LEONI
- 14.1.7 Molex LLC
- 14.1.8 Sumitomo Electric
- 14.1.9 TE Connectivity
- 14.1.10 Yazaki Corporation
- 14.2 Regional Players
- 14.2.1 COFICAB Group
- 14.2.2 Draxlmaier Group
- 14.2.3 K.S. Terminals Inc. (KST)
- 14.2.4 Kyungshin Corporation
- 14.2.5 Nexans Autoelectric
- 14.2.6 Samvardhana Motherson International (SMIL)
- 14.2.7 Spark Minda (Minda Industries Ltd.)
- 14.3 Emerging Players
- 14.3.1 BizLink Holding
- 14.3.2 Luxshare Precision Industry
- 14.3.3 Rosenberger Hochfrequenztechnik

 汽車高壓線束市場:全球市場預測,2026-2032年
 汽車線束:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)汽車線束市場-2026-2032年全球市場預測汽車二次線束市場:2026-2032年全球市場預測(依線束類型、車輛類型、電壓等級、組件類型、材質與應用分類)
 汽車線束市場分析及預測(至2035年):類型、產品類型、技術、組件、應用、材料類型、製造流程、最終用戶、功能、安裝方式汽車線束系統市場分析及預測(至2035年):依類型、產品、技術、組件、應用、材料類型、最終用戶、功能及安裝類型分類
 全球汽車線束市場:按類型和應用、變速箱類型、材料類型、變速箱速度、應用、電壓、內燃機 (ICE)、車輛類型和應用、組件、類別和地區分類 - 預測至 2033 年
 汽車線束系統市場規模、佔有率和成長分析:按組件、線束類型、材質、車輛類型、銷售管道和地區分類-2026-2033年產業預測
 汽車線束市場:按組件、材質、驅動系統和地區分類
 汽車線束市場規模、佔有率和成長分析:按導體材料、驅動系統、銷售管道、應用和地區分類-2026-2033年產業預測