


 |
市場調查報告書
商品編碼
2122567
工業幫浦:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Industrial Pump - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
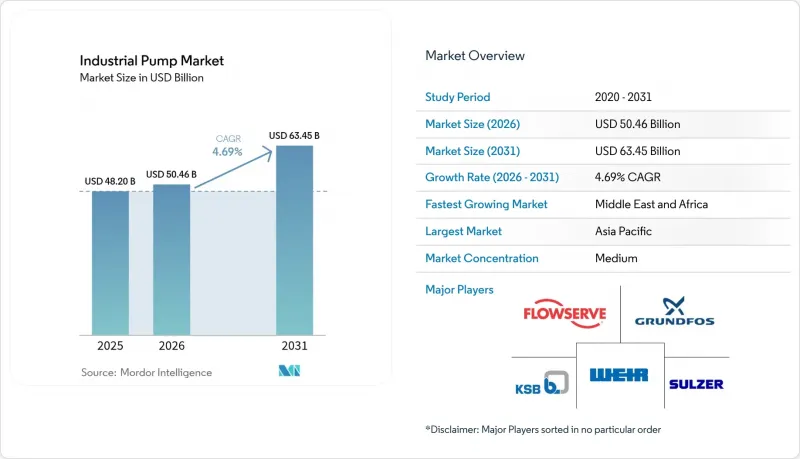
據 Mordor Intelligence 稱,2025 年工業泵浦市場價值為 482 億美元,預計到 2031 年將達到 634.5 億美元,而 2026 年為 504.6 億美元,預測期(2026-2031 年)的複合年成長率為 4.69%。
本報告按泵類型(離心泵、往復泵、旋轉泵等)、動力源(電力、柴油、太陽能等)、終端用戶行業(石油和天然氣、供水和污水處理、化工和石化、發電、採礦、食品和飲料等)、安裝類型(潛水式、地上式)和地區(北美、南美、歐洲、亞太、中東和非洲)進行分類。
全球工業泵市場趨勢與洞察
全球在用水和污水處理方面的支出正在增加。
2024 年和 2025 年初公佈的創紀錄市政預算,導致對大容量離心式和潛水式污水泵的競標增加。美國環保署 (EPA) 估計,長期維修需求將超過 7,440 億美元,推動了多階段升級改造項目,例如蘇城耗資 4.65 億美元的社區設施和卡羅來納州費爾角耗資 2.39 億美元的南區污水處理廠。強制性高階處理措施提高了人們對高壓逆滲透處理管線的興趣,蘇爾壽的垂直多級系統是埃及 Al-Mahsama 污水再生計畫的基礎。供水事業擴大採用無線感測器,將振動和溫度數據傳輸到雲端控制面板,從而縮短關鍵設備的平均維修時間。採購框架顯示出在總擁有成本 (TCO) 計算中優先考慮節能設計的趨勢,促使買家選擇完全符合歐盟 MEI 標準的高效率馬達。此外,加強監督義務擴大了售後市場收入來源,為OEM廠商的持續服務合約奠定了基礎。
擴大中東和非洲(MEA)地區的石化產品產能
海灣國家的生產商正推動下游產業多元化發展,並簽署了裂解裝置、聚合物生產設施和天然氣處理管線的EPC(設計、採購、施工)合約。這些項目總合需要數千台耐腐蝕幫浦。卡達拉斯拉凡聚合物綜合體(預算60億美元)包含一套年產208萬噸乙烷的裂解裝置,計劃於2027年運作。沙烏地阿拉伯耗資110億美元的阿米拉爾計畫新增了165萬噸乙烯產能,並與SATORP煉油廠整合,由此引發了對符合API 610標準、能夠承受400°F(約204°C)排放溫度的泵浦的需求激增。採購競標中包含的在地採購條款進一步獎勵了國際原始設備製造商(OEM)在當地進行泵殼加工和最終組裝。終端用戶優先考慮採用變頻驅動裝置以降電力消耗,並鼓勵採用智慧馬達控制系統,以符合區域能源效率目標。
鋼鐵和銅價的波動推高了總擁有成本。
2024年,受供不應求擔憂的影響,銅價突破每噸1萬美元,逼近1.1萬美元,導致銅含量高的定子和繞組生產商的原料成本上漲3.5%至4.2%。此外,為實現碳中和鋼鐵生產,鋼廠將與氫基生產相關的額外「綠色溢價」轉嫁給消費者,也加劇了市場的不確定性。為因應這一局面,製造商加強了避險策略,重新設計外殼以節約材料,並在供應合約中引入了動態定價條款。同時,終端用戶推遲了可選的更換計劃,延長了設備的平均使用壽命,並抑制了工業泵市場的短期出貨量。
細分市場分析
2025年,離心泵佔工業泵市場總銷量的61.85%,憑藉其在供水、化學品輸送和暖通空調迴路中久經考驗的成本績效效益,為工業泵市場奠定了基礎。由於市政運作週期中的平均檢修週期通常為三年,因此該細分市場在售後市場銷售量強勁。然而,由於高黏度漿料輸送的特殊需求,市場佔有率的成長正轉向螺桿泵,預計到2031年,螺桿泵的複合年成長率將達到7.45%。螺桿泵在石化和採礦等優先考慮低剪切輸送的工業泵市場中,市場佔有率正在擴大。同時,往復泵和隔膜泵仍處於細分市場,分別在高壓注入和衛生生產領域發揮重要作用。基於物聯網的維修已在現有離心式幫浦組中廣泛應用,實現了振動分析,從而進行預測性維護,並將計劃外停機時間減少了高達30%。
螺桿幫浦製造商大力投資耐磨轉子塗層,即使在磨蝕性環境中也能將運作週期延長至 8,000 小時以上。旋轉齒輪幫浦和蠕動幫浦解決了電池材料生產線中新的微量計量難題,凸顯了終端應用領域創新的廣度。基於感測器遙測資料建構的數位孿生模型使操作人員能夠模擬整個流體域的空化風險,從而改進製程控制以保護葉輪。供應商繼續優先採用模組化盒式密封,簡化維護並減少備件庫存。隨著監管機構日益關注能源強度,提高泵殼蝸殼和擴散葉片的效率已成為整個工業泵市場所有類型泵的競爭優勢。
預計到2025年,電動驅動組件將佔據77.95%的主導市場。這主要得益於已開發國家電網的普及以及變頻驅動帶來的效率提升。格雷科QUANTM平台記錄的現場數據顯示,得益於橫向磁通拓撲結構,電機效率最高可達85%,這印證了電動驅動在全生命週期成本方面的優勢。同時,在非洲和南亞農村灌溉計畫的推動下,太陽能解決方案以11.1%的複合年成長率快速成長,成為工業泵浦產業成長最快的細分市場。其安裝成本從76.23歐元(89.13美元)到1219.59歐元(1425.95美元)不等,使其具有極具競爭力的平準化成本,尤其考慮到柴油發電機組的燃料和物流成本。
在電力系統韌性仍存在不確定性的油田壓裂和緊急雨水排放領域,柴油引擎組仍具有重要的戰略意義。在功率密度和點火安全性至關重要的危險區域和移動設備中,液壓和氣壓驅動裝置繼續被應用。結合太陽能電池陣列和鋰離子儲能系統的混合微電網解決方案已在印尼的幾個礦場進入試點測試階段,實現了無需柴油輔助的全天候運作。在現有電動車車隊中引入變頻驅動器 (VFD) 後,在連續海水淡化應用中,能源成本降低了高達 20%。總體而言,電力結構反映了終端用戶的實際情況,但預計在整個預測期內,電動驅動裝置在工業泵浦市場的主導地位將持續存在。
區域分析
亞太地區憑藉著數十年的工業基礎擴張、大規模的城市基礎設施維修以及政策主導的製造業本地化,佔據了市場主導地位,預計到2025年將佔全球銷售額的44.85%。福建省新建的乙烯裂解裝置和澳洲的大規模海水淡化計畫推動了對高效多級泵浦的需求。中國對污水回用的支持以及印度針對化學產品的生產連結獎勵計畫計劃(PLI)持續增加國內外泵製造商的訂單。更嚴格的電力消耗強度和碳足跡法規促使營運商採用變頻驅動裝置(VFD),從而提升了工業泵市場對高效產品線的需求。
中東和非洲地區複合年成長率最高,達6.05%,主要得益於沙烏地阿拉伯、卡達和阿拉伯聯合大公國在石化領域總合170億美元的投資。海水淡化項目,例如NEOM公司日處理量100萬立方米的海水淡化項目,需要耐氯化物應力腐蝕的高壓雙相鋼泵。非洲採礦業的擴張,尤其是在尚比亞和剛果民主共和國,增加了耐磨漿料泵的訂單。在地採購框架鼓勵原始設備製造商(OEM)在阿曼和南非建立服務基地,縮短了檢修時間並增強了品牌忠誠度。在北美,受水利基礎設施立法的推動,設備更換週期趨於穩定,加州、德克薩斯州和佛羅裡達州佔據了離心式幫浦和立式渦輪泵更換競標的大部分佔有率。能源政策獎勵促進了氫電解技術的早期應用,從而為耐腐蝕循環泵創造了利基訂單。歐洲嚴格的MEI法規刺激了對超高效設計的需求,並促使工廠業主重新評估總體擁有成本(TCO)指標。儘管拉丁美洲市場規模較小,但智利和秘魯對農業灌溉泵浦和採礦相關應用的需求穩步成長。在所有地區,包含預測性維護的數位化服務提案都成為競標評估的決定性因素,進一步塑造了工業泵浦市場的競爭格局。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 全球在水和污水處理方面的支出正在增加。
- 擴大中東和非洲(MEA)的石化產品產能
- 亞太全部區域工業基礎建設的快速發展
- 綠色氫氣電解槽浦的需求日益成長
- 一種能夠產生售後市場收入的預測性維護物聯網服務模式。
- 市場限制因素
- 鋼鐵和銅價的波動推高了總擁有成本。
- 更嚴格的泵浦效率指令正在減緩資本投資週期。
- 向乾旱地區無動力重力式微灌系統過渡
- 價值鏈分析
- 技術展望
- 監理情勢
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 泵浦類型
- 離心式幫浦
- 往復式
- 旋轉式
- 隔膜
- 齲齒進展
- 其他
- 透過電源
- 電的
- 柴油引擎
- 太陽的
- 油壓
- 氣壓
- 按最終用戶行業分類
- 石油和天然氣
- 供水和污水處理
- 化工/石油化工
- 發電
- 礦業
- 食品/飲料
- 製藥
- 紙漿和造紙
- 其他
- 按安裝類型
- 水下類型
- 地面類型
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 台灣
- 其他亞太國家
- 中東和非洲
- 中東
- 土耳其
- 以色列
- 海灣合作理事會國家
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Flowserve Corporation
- Grundfos Holding A/S
- Xylem Inc.
- Sulzer Ltd.
- KSB SE & Co. KGaA
- ITT Inc.
- Ebara Corporation
- The Weir Group PLC
- Schlumberger NV(REDA Pump)
- Baker Hughes Company
- SPX FLOW Inc.
- Wilo SE
- Dover Corporation
- Pentair plc
- Franklin Electric Co. Inc.
- Tsurumi Manufacturing Co. Ltd.
- Kirloskar Brothers Ltd.
- Atlas Copco AB
- Ruhrpumpen Group
- Zoeller Company
- Roto Pumps Ltd.
- Gardner Denver LLC(Ingersoll Rand)
- ClydeUnion Pumps(Celeros Flow Tech)
- LEWA GmbH
- Graco Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the industrial pump market size was valued at USD 48.2 billion in 2025 and estimated to grow from USD 50.46 billion in 2026 to reach USD 63.45 billion by 2031, at a CAGR of 4.69% during the forecast period (2026-2031).
This report is Segmented by Pump Type (Centrifugal, Reciprocating, Rotary, and More), Power Source (Electric, Diesel, Solar, and More), End-User Industry (Oil and Gas, Water and Waste-Water, Chemicals and Petrochemicals, Power Generation, Mining, Food and Beverage, and More), Pump Orientation (Submersible, and Surface), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa).
Global Industrial Pump Market Trends and Insights
Rising Water and Wastewater Treatment Spending Globally
Record municipal budgets released in 2024 and early 2025 translated into larger tender volumes for high-capacity centrifugal and submersible sewage pumps. The US Environmental Protection Agency estimated long-term rehabilitation needs above USD 744 billion, prompting multi-phase upgrades such as Sioux City's USD 465 million regional facility and Cape Fear's USD 239 million Southside plant. Advanced treatment mandates drove interest in high-pressure reverse-osmosis trains, with Sulzer's vertical multistage systems underpinning Egypt's Al Mahsama drainage reclamation project. Utilities are increasingly embedding wireless sensors that stream vibration and temperature data into cloud dashboards, shortening mean-time-to-repair on critical units. Procurement frameworks began weighting total-cost-of-ownership calculations that favor energy-efficient designs, nudging buyers toward premium efficiency motors that comfortably clear EU MEI thresholds. Heightened monitoring obligations also expanded aftermarket revenue pools, anchoring recurring service contracts for OEMs.
Expansion of Petrochemical Capacity in MEA
Gulf producers pushed downstream diversification agendas, awarding EPC contracts for crackers, polymer units, and gas-processing trains that collectively require thousands of corrosion-resistant pumps. Qatar's Ras Laffan polymers complex, budgeted at USD 6 billion, incorporated a 2,080 KTA ethane cracker slated for 2027 on-stream dates. Saudi Arabia's USD 11 billion Amiral project added 1.65 million tons of ethylene nameplate capacity integrated with SATORP's refinery, multiplying demand for API 610 compliant pumps that withstand 400°F discharge temperatures. Local-content clauses inside procurement tenders intensified incentives for international OEMs to localize casing machining and final assembly. End-users prioritized variable-frequency drives to curb power draw, reinforcing adoption of smart motor controls that align with regional energy-efficiency ambitions.
Volatility in Steel and Copper Prices Inflating TCO
Copper cleared USD 10,000 per metric ton in 2024 and flirted with USD 11,000 amid looming supply deficits, hiking producer input costs by 3.5%-4.2% on copper-intensive stators and windings. Carbon-neutral steel initiatives added further unpredictability as mills passed on green-premium surcharges linked to hydrogen-based production. Manufacturers responded by tightening hedging programs, redesigning casings for material thrift, and introducing dynamic price clauses into supply contracts. End-users, meanwhile, deferred discretionary replacements, stretching the mean equipment life and tempering near-term shipment volumes in the industrial pump market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Industrial Infrastructure Build-out Across Asia-Pacific
- Demand for Corrosion-Resistant Pumps in Green-Hydrogen Electrolyzers
- Stricter Pump-Efficiency Directives Delaying Cap-ex Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Centrifugal units retained 61.85% of 2025 revenue, anchoring the industrial pump market through their proven cost-performance balance in water supply, chemical transfer, and HVAC loops. The segment generated steady aftermarket volumes, given typical mean-time-between-overhauls of three years in municipal duty cycles. However, specialty demands in viscous slurry handling shifted incremental share toward progressing cavity designs, which are projected to clock 7.45% CAGR through 2031. The progressing cavity cohort captured a rising slice of the industrial pump market size for petrochemical and mining customers that prize low-shear conveyance. Meanwhile, reciprocating and diaphragm pumps preserved critical roles in high-pressure injection and sanitary production, respectively, albeit with niche footprints. IoT retrofits became common even on legacy centrifugal sets, enabling predictive vibration analytics that cut unscheduled downtime by up to 30%.
Progressing cavity manufacturers invested heavily in wear-resistant rotor coatings to extend service intervals beyond 8,000 hours under abrasive duty. Rotary gear and peristaltic pumps addressed emerging micro-dosing tasks within battery-materials manufacturing lines, underscoring the breadth of end-use innovation. Digital twins built from sensor telemetry allowed operators to simulate cavitation risk across the hydraulic envelope, driving process-control refinements that protect impellers. Suppliers continued to emphasize modular cartridge seals that simplify maintenance and shrink spare inventory. With regulatory spotlight fixed on energy intensity, efficiency upgrades in casing volutes and diffuser vanes became a competitive must-have across all pump types in the broader industrial pump market.
Electric-driven assemblies held a commanding 77.95% share in 2025, benefitting from near-universal grid access in industrialized economies and the incremental efficiency yields of variable-frequency drives. Field data logged by Graco's QUANTM platform demonstrated up to 85% motor efficiency thanks to transverse-flux topology, reinforcing the narrative of electricity-based lifecycle cost advantage. Solar-powered solutions, however, emerged as the fastest expanding slice of the industrial pump industry, advancing at an 11.1% CAGR on the back of rural irrigation projects in Africa and South Asia. Installation costs ranging from EUR 76.23 (USD 89.13) to EUR 1,219.59 (USD 1,425.95) translated to competitive levelized costs, particularly once fuel-logistics premiums on diesel sets were factored in.
Diesel-engine packages retained strategic relevance for oilfield fracturing and emergency stormwater evacuation, where grid resilience remained questionable. Hydraulic and pneumatic drives continued to serve hazardous-area placements and mobile plant equipment that prized power density and ignition safety. Hybrid microgrid solutions that pair PV arrays with lithium-ion storage entered the pilot stage at several Indonesian mines, offering 24/7 uptime without diesel supplementation. VFD retrofits on existing electric fleets shaved energy bills by up to 20% in continuous-duty desalination applications. Altogether, the power-source mix illustrated end-user pragmatism, but electric leadership in the industrial pump market is expected to persist through the forecast horizon.
Complete Report Scope:
- By Pump Type
- Centrifugal
- Reciprocating
- Rotary
- Diaphragm
- Progressing Cavity
- Others
- By Power Source
- Electric
- Diesel
- Solar
- Hydraulic
- Pneumatic
- By End-user Industry
- Oil and Gas
- Water and Waste-water
- Chemicals and Petrochemicals
- Power Generation
- Mining
- Food and Beverage
- Pharmaceuticals
- Pulp and Paper
- Others
- By Pump Orientation
- Submersible
- Surface
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Taiwan
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Turkey
- Israel
- GCC Countries
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific dominated with 44.85% revenue in 2025 after decades of industrial build-out, extensive municipal upgrades, and policy-driven manufacturing localization. New ethylene cracker complexes in Fujian and large-scale desalination schemes in Australia magnified the procurement of high-efficiency multistage pumps. China's stimulus for wastewater reuse and India's Production Linked Incentive program for chemicals continued to channel orders toward both global and domestic pump manufacturers. Regulatory pushes around electricity intensity and carbon footprints incentivized operators to retrofit VFDs, nudging market volume toward premium-efficiency product lines within the industrial pump market.
The Middle East and Africa posted the fastest 6.05% CAGR, propelled by USD 17 billion in combined petrochemical investments across Saudi Arabia, Qatar, and the United Arab Emirates. Desalination, such as NEOM's 1 million m3/day seawater project, demanded high-pressure duplex-steel pumps tolerant to chloride stress-corrosion. African mining expansions in Zambia and the Democratic Republic of Congo increased orders for abrasion-resistant slurry units. Local content frameworks pushed OEMs to open service hubs in Oman and South Africa, shortening turnaround times on overhauls and reinforcing brand loyalty. North America experienced a steady replacement cycle driven by water infrastructure bills, with California, Texas, and Florida aggregating the bulk of tenders for replacement centrifugal and vertical turbine pumps. Energy policy incentives supported early adoption of hydrogen electrolysis, sparking niche orders for corrosion-resistant circulation pumps. Europe's stringent MEI regulations stimulated demand for ultra-high-efficiency designs and encouraged plant owners to reassess total-cost-of-ownership metrics. Latin America, though smaller, witnessed steady uptake in agricultural irrigation pumps and mining-related demand in Chile and Peru. Across all regions, digital service propositions featuring predictive maintenance became a decisive factor in bid evaluations, further shaping competitive standings in the industrial pump market.
- Flowserve Corporation
- Grundfos Holding A/S
- Xylem Inc.
- Sulzer Ltd.
- KSB SE & Co. KGaA
- ITT Inc.
- Ebara Corporation
- The Weir Group PLC
- Schlumberger NV (REDA Pump)
- Baker Hughes Company
- SPX FLOW Inc.
- Wilo SE
- Dover Corporation
- Pentair plc
- Franklin Electric Co. Inc.
- Tsurumi Manufacturing Co. Ltd.
- Kirloskar Brothers Ltd.
- Atlas Copco AB
- Ruhrpumpen Group
- Zoeller Company
- Roto Pumps Ltd.
- Gardner Denver LLC (Ingersoll Rand)
- ClydeUnion Pumps (Celeros Flow Tech)
- LEWA GmbH
- Graco Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising water and waste-water treatment spending globally
- 4.2.2 Expansion of petrochemical capacity in MEA
- 4.2.3 Rapid industrial infrastructure build-out across Asia-Pacific
- 4.2.4 Demand for corrosion-resistant pumps in green-hydrogen electrolyzers
- 4.2.5 Predictive-maintenance IoT service models unlocking aftermarket revenue
- 4.3 Market Restraints
- 4.3.1 Volatility in steel and copper prices inflating TCO
- 4.3.2 Stricter pump-efficiency directives delaying cap-ex cycles
- 4.3.3 Shift to motor-less gravity micro-irrigation systems in arid economies
- 4.4 Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Pump Type
- 5.1.1 Centrifugal
- 5.1.2 Reciprocating
- 5.1.3 Rotary
- 5.1.4 Diaphragm
- 5.1.5 Progressing Cavity
- 5.1.6 Others
- 5.2 By Power Source
- 5.2.1 Electric
- 5.2.2 Diesel
- 5.2.3 Solar
- 5.2.4 Hydraulic
- 5.2.5 Pneumatic
- 5.3 By End-user Industry
- 5.3.1 Oil and Gas
- 5.3.2 Water and Waste-water
- 5.3.3 Chemicals and Petrochemicals
- 5.3.4 Power Generation
- 5.3.5 Mining
- 5.3.6 Food and Beverage
- 5.3.7 Pharmaceuticals
- 5.3.8 Pulp and Paper
- 5.3.9 Others
- 5.4 By Pump Orientation
- 5.4.1 Submersible
- 5.4.2 Surface
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Taiwan
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Turkey
- 5.5.5.1.2 Israel
- 5.5.5.1.3 GCC Countries
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Flowserve Corporation
- 6.4.2 Grundfos Holding A/S
- 6.4.3 Xylem Inc.
- 6.4.4 Sulzer Ltd.
- 6.4.5 KSB SE & Co. KGaA
- 6.4.6 ITT Inc.
- 6.4.7 Ebara Corporation
- 6.4.8 The Weir Group PLC
- 6.4.9 Schlumberger NV (REDA Pump)
- 6.4.10 Baker Hughes Company
- 6.4.11 SPX FLOW Inc.
- 6.4.12 Wilo SE
- 6.4.13 Dover Corporation
- 6.4.14 Pentair plc
- 6.4.15 Franklin Electric Co. Inc.
- 6.4.16 Tsurumi Manufacturing Co. Ltd.
- 6.4.17 Kirloskar Brothers Ltd.
- 6.4.18 Atlas Copco AB
- 6.4.19 Ruhrpumpen Group
- 6.4.20 Zoeller Company
- 6.4.21 Roto Pumps Ltd.
- 6.4.22 Gardner Denver LLC (Ingersoll Rand)
- 6.4.23 ClydeUnion Pumps (Celeros Flow Tech)
- 6.4.24 LEWA GmbH
- 6.4.25 Graco Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球工業泵浦控制面板市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026-2030年全球瀝青泵市場
 印度工業泵:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 活塞幫浦市場分析與預測(至2035年):類型、產品、技術、組件、應用、材質、最終用戶、功能、安裝配置、解決方案液壓軸向活塞泵市場分析及預測(至2035年):類型、產品、技術、組件、應用、最終用戶、功能、安裝類型、設備、解決方案工業泵浦市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。
 工業泵浦市場-2026-2032年全球市場預測
 2026年全球工程幫浦市場報告
 2026-2030年全球工業幫浦租賃市場
 商用幫浦市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、地區和競爭格局分類,2021-2031年