


 |
市場調查報告書
商品編碼
2122510
雲端監控:市場佔有率分析、產業趨勢和統計數據、成長預測(2026-2031)Cloud Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
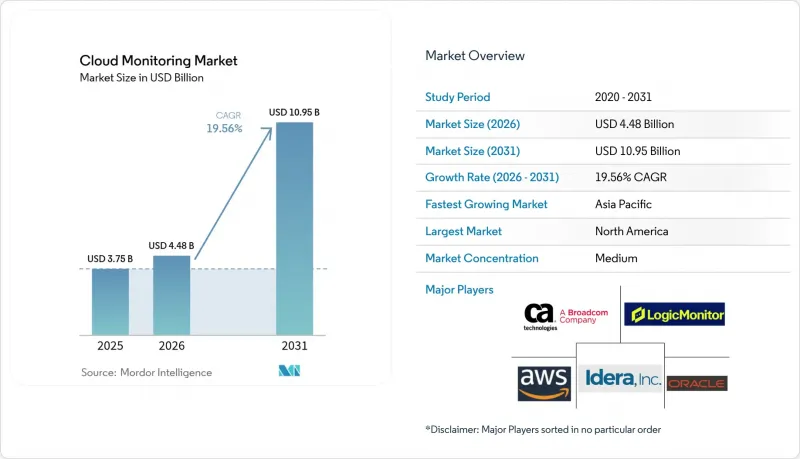
根據 Mordor Intelligence 預測,雲端監控市場規模將從 2025 年的 37.5 億美元成長到 2026 年的 44.8 億美元,然後在 2031 年達到 109.5 億美元,2026 年至 2031 年的複合年成長率為 19.56%。
本報告按雲端服務模型(IaaS、SaaS、PaaS)、組件(解決方案和服務)、部署類型(公共雲端、私有雲端、混合/多重雲端)、組織規模(中小企業和大型企業)、最終用戶行業(銀行、金融服務和保險、零售和電子商務、IT和電信、醫療保健和生命科學、政府和公共部門、製造業等)以及地區進行分類。
全球雲端監控市場趨勢與洞察
加速採用多重雲端和混合雲端
多重雲端部署已進入轉折點,預計到 2024 年,43% 的金融服務公司將把工作負載分佈在兩個或多個超大規模資料中心業者上。由於每個雲端服務供應商都導出自己的指標,維運團隊面臨遙測資料分散和盲點的問題。因此,能夠標準化來自 AWS、Azure 和 Google Cloud 資料的統一平台正在取代單雲監控工具。 OpenTelemetry 代理商的採用率激增,這得益於其廠商中立的指標功能,能夠實現對整個環境的全面覆蓋。此外,當同一事務同時涉及本地和雲端節點時,企業需要一種能夠展現成本、效能和合規性之間關聯的視圖。這些壓力正促使混合雲端可觀測性從“可選”升級為“必備功能”,雲端可觀測性市場也朝著更深入的端到端視角發展。
DevOps/SRE 文化與即時可觀測性
站點可靠性工程 (SRE) 已成為大型企業的主流做法,平均每小時可降低超過 100 萬美元的停機成本。該團隊現在將「黃金訊號」和服務等級目標整合到 CI/CD 管線中,以便在部署到生產環境之前識別缺陷。與孤立的工具鏈相比,全端可視性可將停機時間減少 79%。人工智慧驅動的異常檢測透過從日誌和追蹤中發現事件的徵兆,對人工工作起到補充作用。更快的回饋循環也提高了開發人員的生產力,使可觀測性成為直接的業務促進因素。因此,雲端可觀測性市場正受惠於預算分配從傳統 IT 維運部門轉變為工程團隊的轉變。
容器化、無伺服器架構中可見性的局限性
容器生命週期僅為幾秒,無伺服器函數無需代理即可啟動,這造成了傳統監控工具無法填補的監控盲點。 Kubernetes 會產生海量元資料,而暴力收集會產生儲存成本。一種解決方案是將分散式追蹤(用於追蹤跨微服務的請求路徑)與低開銷的基於 eBPF 的檢測相結合。 OpenTelemetry 至關重要,但其實現仍然複雜,這減緩了資源受限的中小型企業採用它的速度。在承包用的檢測方案成熟之前,短期環境中的可觀測性差距將拖累雲可觀測性市場的複合年成長率 (CAGR)。
細分市場分析
到2025年,SaaS平台將佔總營收的47.80%,反映出市場對無需基礎設施開銷的承包部署方案有著強勁的需求。 PaaS解決方案是成長最快的細分市場,年複合成長率高達28.45%,因為使用者希望在無需管理資料擷取器的情況下獲得深入的程式碼層級洞察。 IaaS工具在混合環境中仍然發揮著至關重要的作用,因為這些環境需要在受監管資料附近部署本地資料擷取器。隨著產業向託管服務轉型,SaaS領域的雲端可觀測性市場預計將在2026年至2031年間成長至29.2億美元。
PaaS 的發展勢頭反映了平台工程團隊將可觀測性整合到其內部開發者入口網站中。領先的技術供應商正在將追蹤、混沌測試和 KPI 儀表板直接整合到其建置管道中,從而減輕認知負擔。結合 OpenTelemetry 的自動化檢測功能,這種協同效應加速了價值實現。因此,雲端可觀測性市場近三分之一的新訂單來自專注於 AI 模式可觀測性和成本分析的 PaaS 交易。
到2025年,包含資料湖、關聯引擎和使用者體驗分析的解決方案套件將佔總收入的61.30%。由於企業難以招募到足夠的可觀測性工程師,服務諮詢、客戶導入和託管可觀測性服務正以18.85%的複合年成長率成長。對整合商的需求主要來自受監管行業,因為這些行業的測量必須符合法規結構。
該供應商的藍圖現已納入諮詢服務、認證培訓和快速入門包,以縮短價值驗證 (PoV) 週期。 LogicMonitor 已獲得 8 億美元資金籌措用於服務擴展,這表明專業知識是關鍵的競爭優勢。隨著框架的演進,經常性服務合約在整體雲端可觀測性市場的收入佔有率將不斷增加,並進一步深化合作夥伴生態系統。
區域分析
到2025年,北美將佔總收入的40.60%,這反映了該地區數十年來DevOps技術的成熟以及在人工智慧領域的大量投資。金融機構報告稱,由於系統宕機,每年平均損失1,044萬美元,凸顯了採用高級工具的必要性。儘管圍繞著「主權雲」的討論有所降溫,但由於隱私法規的限制,對資料居住功能的需求依然強勁。 2027年後,隨著更新換代週期趨於飽和,成長速度將放緩至10%左右,但由於人工智慧可觀測性的提升,預計許可擴張仍將持續。
亞太地區正經歷最快的成長,複合年成長率高達20.85%,這主要得益於雲端優先型新創公司和政府主導的數位化措施。預計到2028年,印度的公共雲端支出將達到255億美元。新加坡和印尼透過減少停機時間實現了高投資回報率,實際投資回報率超過114%。在中國(雲端市場規模達6.192兆元),阿里雲佔了43%的市場佔有率,在地化儀錶板和本土資料湖正在推廣。
在歐洲,由於GDPR和即將訂定的人工智慧法案,資料保護要求日益嚴格,導致雲端可觀測性市場年複合成長率約為15.5%。Accenture調查顯示,37%的公司已投資於主權雲,44%的公司計劃在未來兩年內進一步投資。供應商正與本地託管服務提供者合作,以確保歐盟境內日誌管道的安全。隨著氣候變遷報告和績效指標的融合,能源儀錶板的應用也日益廣泛。這些區域性特徵共同推動雲端可觀測性市場朝向多元化、合規性強的部署方向發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 多重雲端和混合雲端的採用正在加速。
- 對 DevOps/SRE 文化和即時可觀測性的需要
- AI/ML 工作負載的爆炸性成長需要 GPU 等級的監控。
- 財務營運中的課責以及最佳化成本效益的壓力。
- 用於雲碳報告的永續性儀表板
- 強制性主權雲端和資料本地化
- 市場限制因素
- 容器化無伺服器堆疊的低可見性
- 全端可觀測性平台的整體擁有成本不斷上升
- 可觀測性工程技能差距
- 超大規模資料中心業者API 速率限制限制了詳細的遙測資料取得。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型分類的雲端服務模型
- IaaS
- PaaS
- SaaS
- 按組件
- 解決方案
- 服務
- 部署模式
- 公共雲端
- 私有雲端
- 混合/多重雲端
- 按組織規模
- SME
- 大公司
- 按最終用戶行業分類
- BFSI
- 零售與電子商務
- 資訊科技/通訊
- 醫療保健和生命科學
- 政府/公共部門
- 製造業
- 其他(媒體、能源、教育)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 亞太其他地區
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- AWS
- Microsoft
- Google Cloud
- IBM
- Oracle
- Datadog
- Dynatrace
- New Relic
- Broadcom(CA Tech/AppDynamics)
- LogicMonitor
- Splunk
- SolarWinds
- PagerDuty
- Cisco ThousandEyes
- Grafana Labs
- Elastic
- Zenoss
- ScienceLogic
- Idera
第7章 市場機會與未來展望
According to Mordor Intelligence, the cloud monitoring market size is expected to grow from USD 3.75 billion in 2025 to USD 4.48 billion in 2026 and is forecast to reach USD 10.95 billion by 2031 at 19.56% CAGR over 2026-2031.
This report is Segmented by Cloud Service Model (IaaS, Saas, Paas), Component (Solution and Services), Deployment Mode (Public Cloud, Private Cloud, and Hybrid/Multi-Cloud), Organization Size (SMEs and Large Enterprises), End-User Industry (BFSI, Retail and E-Commerce, IT and Telecommunications, Healthcare and Life Sciences, Government and Public Sector, Manufacturing, and Others), and Geography.
Global Cloud Monitoring Market Trends and Insights
Accelerated Multi-Cloud and Hybrid-Cloud Adoption
Multi-cloud usage crossed a tipping point, with 43% of financial-services firms already distributing workloads across two or more hyperscalers in 2024. Each provider exports unique metrics, so operations teams face telemetry sprawl and blind spots. Unified platforms that normalise data across AWS, Azure, and Google Cloud are therefore replacing single-cloud monitors. Adoption of OpenTelemetry agents rose sharply because vendor-neutral instrumentation eases estate-wide coverage. Organisations also need correlated cost, performance, and compliance views when the same transaction spans on-premises and cloud nodes. These pressures elevate hybrid-cloud observability from optional to indispensable capability, pushing the cloud observability market toward deeper end-to-end context.
DevOps/SRE Culture and Real-Time Observability
Site Reliability Engineering is mainstreamed in large enterprises, cutting mean outage costs that exceed USD 1 million per hour. Teams now embed golden signals and service-level objectives into CI/CD pipelines so that defects surface before production rollouts. Full-stack insight lowers downtime by 79% versus siloed toolchains. AI-driven anomaly detection augments humans by surfacing precursors to incidents across logs and traces. Faster feedback loops also boost developer productivity, turning observability into a direct business enabler. The cloud observability market, therefore, benefits from budgets shifting left toward engineering teams rather than traditional IT operations.
Limited Visibility in Containerised, Serverless Stacks
Containers may live for seconds, while serverless functions spin up without agents, leaving gaps that legacy monitors cannot fill. Kubernetes adds torrent-level metadata, so brute-force collection inflates storage bills. Distributed tracing that stitches request paths across microservices, combined with eBPF-based low-overhead instrumentation, is emerging as the remedy. OpenTelemetry is pivotal yet still complex to deploy, explaining slower adoption among resource-constrained SMEs. Until turnkey instrumentation matures, observability gaps in ephemeral environments will drag on the cloud observability market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- AI/ML Workload Explosion Requiring GPU-Level Monitoring
- FinOps Accountability and Cost-to-Value Optimisation Pressure
- Rising TCO of Full-Stack Observability Platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SaaS platforms anchored 47.80% of 2025 revenue, underscoring demand for turnkey deployments that remove infrastructure overhead. PaaS solutions shape the fastest lane, growing 28.45% CAGR as users crave deeper code-level insight without managing collectors. IaaS tools retain relevance for hybrid estates that need on-premises collectors close to regulated data. The cloud observability market size for SaaS is forecast to widen by USD 2.92 billion between 2026 and 2031 as lagging industries migrate to managed services.
PaaS momentum reflects platform-engineering teams embedding observability into internal developer portals. Big-tech vendors integrate tracing, chaos testing, and KPI dashboards directly into build pipelines, reducing cognitive load. Combined with OpenTelemetry auto-instrumentation, this synergy accelerates time to value. Consequently, the cloud observability market records almost one-third of net-new bookings from PaaS deals targeting AI model observability and cost analytics.
Solution suites captured 61.30% revenue in 2025, covering data lakes, correlation engines, and UX analytics. Services consulting, onboarding, and managed observability grow 18.85% CAGR as enterprises struggle to hire observability engineers. Integrator demand is highest in regulated verticals where instrumentation must map to control frameworks.
Vendor roadmaps now bundle advisory hours, certified training, and quick-start packs that shorten proof-of-value cycles. LogicMonitor's USD 800 million funding earmarked for services expansion signals how professional expertise becomes a key moat. As frameworks evolve, recurring service contracts will comprise a larger slice of the overall cloud observability market revenue, deepening partner ecosystems.
Complete Report Scope:
- By Cloud Service Model
- IaaS
- PaaS
- SaaS
- By Component
- Solution
- Services
- By Deployment Mode
- Public Cloud
- Private Cloud
- Hybrid/Multi-Cloud
- By Organisation Size
- SMEs
- Large Enterprises
- By End-User Industry
- BFSI
- Retail and e-Commerce
- IT and Telecommunications
- Healthcare and Life Sciences
- Government and Public Sector
- Manufacturing
- Others (Media, Energy, Education)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America commanded 40.60% of 2025 revenue, reflecting decades-long DevOps maturity and heavy AI investment. Financial institutions cite median outage losses of USD 10.44 million per year, justifying premium tooling. Sovereign-cloud talk is muted, yet privacy laws still nudge data residency features. Growth moderates to low teens after 2027 as replacement cycles saturate, but AI observability upgrades sustain license expansion.
Asia Pacific is the fastest mover at 20.85% CAGR, propelled by cloud-first start-ups and government digital drives. India's public cloud outlay could reach USD 25.5 billion by 2028. Observability ROI tops 114% in Singapore and Indonesia, showcasing high payoff for downtime reduction. China's 6.192 trillion-yuan cloud sector, led by Alibaba Cloud's 43% hold, fuels local-language dashboards and in-country data lakes.
Europe records mid-teens CAGR as GDPR and upcoming AI Act cement data-protection demands. Accenture notes 37% of enterprises investing in sovereign cloud, with 44% planning more within two years. Vendors partner with regional hosts to ensure EU-located logging pipelines. Energy dashboards gain traction as climate reporting merges with performance metrics. These regional nuances collectively propel the cloud observability market toward diverse compliance-aware deployments.
- AWS
- Microsoft
- Google Cloud
- IBM
- Oracle
- Datadog
- Dynatrace
- New Relic
- Broadcom (CA Tech/AppDynamics)
- LogicMonitor
- Splunk
- SolarWinds
- PagerDuty
- Cisco ThousandEyes
- Grafana Labs
- Elastic
- Zenoss
- ScienceLogic
- Idera
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated multi-cloud and hybrid-cloud adoption
- 4.2.2 DevOps/SRE culture and need for real-time observability
- 4.2.3 AI/ML workload explosion requiring GPU-level monitoring
- 4.2.4 FinOps accountability and cost-to-value optimisation pressure
- 4.2.5 Sustainability dashboards for cloud-carbon reporting
- 4.2.6 Sovereign-cloud and data-localisation mandates
- 4.3 Market Restraints
- 4.3.1 Limited visibility in containerised, serverless stacks
- 4.3.2 Rising TCO of full-stack observability platforms
- 4.3.3 Skills gap for observability engineering
- 4.3.4 Hyperscaler API-rate limits throttling deep telemetry
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry Intensity
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cloud Service Model
- 5.1.1 IaaS
- 5.1.2 PaaS
- 5.1.3 SaaS
- 5.2 By Component
- 5.2.1 Solution
- 5.2.2 Services
- 5.3 By Deployment Mode
- 5.3.1 Public Cloud
- 5.3.2 Private Cloud
- 5.3.3 Hybrid/Multi-Cloud
- 5.4 By Organisation Size
- 5.4.1 SMEs
- 5.4.2 Large Enterprises
- 5.5 By End-User Industry
- 5.5.1 BFSI
- 5.5.2 Retail and e-Commerce
- 5.5.3 IT and Telecommunications
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Government and Public Sector
- 5.5.6 Manufacturing
- 5.5.7 Others (Media, Energy, Education)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AWS
- 6.4.2 Microsoft
- 6.4.3 Google Cloud
- 6.4.4 IBM
- 6.4.5 Oracle
- 6.4.6 Datadog
- 6.4.7 Dynatrace
- 6.4.8 New Relic
- 6.4.9 Broadcom (CA Tech/AppDynamics)
- 6.4.10 LogicMonitor
- 6.4.11 Splunk
- 6.4.12 SolarWinds
- 6.4.13 PagerDuty
- 6.4.14 Cisco ThousandEyes
- 6.4.15 Grafana Labs
- 6.4.16 Elastic
- 6.4.17 Zenoss
- 6.4.18 ScienceLogic
- 6.4.19 Idera
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 網站和伺服器監控服務市場:全球市場預測,2026-2032年
 監控即服務 (MaaS) 市場規模、佔有率和成長分析:按系統類型、部署方式、企業規模、最終用戶產業和地區分類-2026-2033 年產業預測
 雲端監控市場預測至 2034 年—按組件、部署模式、企業規模、最終用戶和地區分類的全球分析雲端監控市場:按組件、服務模型、監控類型、部署模式、組織規模和最終用戶分類-2026-2032年全球市場預測
 雲端監控市場規模、佔有率和趨勢分析報告:按類型、服務模式、企業規模、最終用途、地區和細分市場預測(2026-2033 年)
 API可觀測性和測試軟體:市場佔有率分析、產業趨勢和統計數據以及成長預測(2026-2031年)
 2026年全球全端可觀測性服務市場報告
 雲端監控市場分析及預測(至 2035 年):類型、產品類型、服務、技術、元件、應用、部署模式、最終使用者、解決方案2026年全球雲端監控市場報告
 全球雲端監控市場規模、佔有率、趨勢和成長分析報告(2026-2034年)