


 |
市場調查報告書
商品編碼
2122500
物聯網分析:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)IoT Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
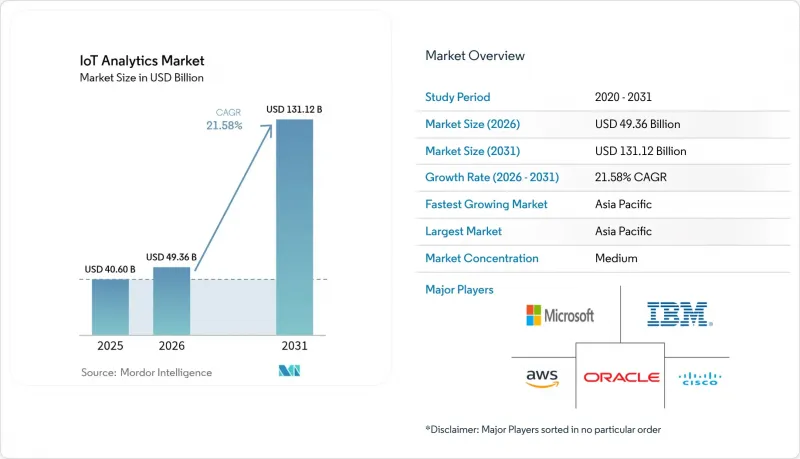
據 Mordor Intelligence 稱,物聯網分析市場在 2025 年的價值為 406 億美元,預計到 2031 年將達到 1311.2 億美元,而 2026 年為 493.6 億美元,預測期(2026-2031 年)的複合年成長率為 21.58%。
本報告按組件(解決方案和服務)、部署模式(本地部署和雲端部署)、組織規模(大型企業和中小企業)、應用(預測性維護、資產性能管理、能源管理等)、最終用戶行業(製造業、能源和公共產業、運輸和物流、零售和電子商務等)以及地區進行分類。
全球物聯網分析市場趨勢與洞察
物聯網設備數量迅速成長,產生Exabyte級數據。
連網設備數量呈現爆炸性成長,預計2025年,全球物聯網終端每年將產生超過175Zetta位元組的資料。工廠級感測器陣列每天已發送Terabyte的數據,迫使企業在邊緣部署分析引擎,以避免回程傳輸傳至雲端的延遲。採用這種「邊緣優先」模式的製造商,其營運效率比純雲端環境提高了30%。資料量的激增,涵蓋結構化遙測資料、非結構化影片和日誌文件,正推動企業投資於能夠同時處理各種有效載荷的多模態分析框架。
雲端原生分析平台正逐漸被企業接受。
微軟 Azure IoT Operations 等可擴展的付費使用制服務使企業能夠每天處理數十億條訊息,同時將基礎設施支出降低高達 60%。零信任架構和內建威脅分析功能可降低安全隱患,進而加速製造業和物流業全面採用雲端技術。儘管受嚴格監管的行業仍然傾向於採用雲端和本地混合處理模式,但隨著服務供應商不斷擴展其合規工具包,雲端轉型勢頭依然強勁。
資料隱私和跨境合規的複雜性
GDPR 對用戶同意、資料最小化和本地化施加了嚴格的規定,違規可能面臨相當於全球營業額 4% 的罰款。不同的國家法律迫使企業維護多個區域資料存儲,導致專案預算增加高達 25%。跨境即時分析需要整合策略感知路由以滿足主權要求,這減緩了企業採用該技術的速度。
細分市場分析
解決方案領域將持續引領市場發展,預計到2025年將佔總營收的67.95%。物聯網分析解決方案市場預計將穩定擴張,而隨著企業對專業管理服務的需求不斷成長,服務領域的複合年成長率預計將達到23.12%。對協定映射、邊緣協定堆疊調優和多重雲端整合等領域的專業服務需求正在不斷成長。
在人才短缺和架構日益複雜的背景下,利用外部合作夥伴正受到越來越多的關注。託管服務合約通常將軟體、基礎設施和基於結果的服務等級協定 (SLA) 打包提供,從而將風險轉移給服務提供者。安全分析這一細分領域的發展,則是由與連網裝置相關的不斷擴大的攻擊面所驅動的。
到 2025 年,本地部署將佔 64.62% 的佔有率,這反映了其可控性、延遲和監管要求等因素。然而,隨著超大規模資料中心業者資料中心將資料擷取管道與無伺服器分析引擎結合,雲端實例正以 23.30% 的複合年成長率成長。混合架構將時間敏感型工作負載路由到邊緣節點,同時將聚合資料傳送到雲端進行批次 AI 處理。
微軟和亞馬遜是可組合解決方案領域的行業領導者,使企業能夠在幾分鐘內啟動數位孿生和大規模模型訓練。供應鏈的波動和能源價格的波動凸顯了彈性運算的需求,進一步加速了雲端運算的普及。
區域分析
亞太地區受惠於「中國製造2025」和印度「智慧城市計畫」等政府項目,預計到2025年將佔全球收入的35.86%。該地區的複合年成長率預計為22.84%,這清晰地展現了工業數位化、5G部署和邊緣人工智慧先導計畫的規模。中國工廠正在實施基於視覺的品管,印度市政當局正在利用感測器網路來管理廢棄物和交通。
北美緊隨其後,這得益於其成熟的雲端基礎設施和對人工智慧的早期應用。在強大的創業投資資金和學術研究支持下,各公司正在將串流分析整合到其數位化營運中心。該地區持續作為自動駕駛和精密農業計畫的試驗場。
在歐洲,ESG合規透過提供即時排放監測,正推動經濟穩定成長。歐洲綠色交易下的各項措施正引領公共產業和製造業走向數據驅動的效率提升。隨著電信業者擴大NB-IoT和5G覆蓋範圍,拉丁美洲和中東等新興市場正蓬勃發展,為物流、石油和公共安全等領域的新部署提供了可能。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 物聯網設備的激增正在產生Exabyte級數據。
- 雲端原生分析平台正被企業廣泛接受。
- 資產密集型產業對預測性維護的需求
- 邊緣AI加速器,可在邊緣端實現不到一秒的分析速度。
- 整合孤立物聯網資料流的企業資料架構架構
- 基於ESG的強制性永續監測
- 市場限制因素
- 資料隱私和跨境合規的複雜性
- 物聯網資料科學人才短缺
- 工業協議的碎片化阻礙了互通性
- 高頻感測器遙測頻寬成本不斷上漲
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資分析
- 評估宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 按組件
- 解決方案
- 網管
- 安全分析
- 即時串流分析
- 資料管理和儲存分析
- 視覺化和儀錶板
- 服務
- 專業服務
- 託管服務
- 解決方案
- 不同的發展
- 現場
- 雲
- 按組織規模
- 大公司
- 中小企業
- 透過使用
- 預測性保護
- 資產績效管理
- 能源管理
- 供應鍊和物流最佳化
- 其他用途
- 按最終用戶行業分類
- 製造業
- 能源公用事業
- 運輸/物流
- 零售與電子商務
- 醫療保健和生命科學
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- Amazon Web Services, Inc.
- IBM Corporation
- Google LLC
- Cisco Systems, Inc.
- Oracle Corporation
- SAP SE
- Dell Technologies Inc.
- The Hewlett Packard Enterprise Company
- Teradata Corporation
- Salesforce, Inc.
- Accenture plc
- PTC Inc.
- Hitachi Vantara LLC
- Cloudera, Inc.
- Software AG
- SAS Institute Inc.
- Splunk Inc.
- C3.ai, Inc.
- Uptake Technologies Inc.
- GE Digital
- QlikTech International AB
第7章 市場機會與未來展望
According to Mordor Intelligence, the IoT analytics market size was valued at USD 40.60 billion in 2025 and estimated to grow from USD 49.36 billion in 2026 to reach USD 131.12 billion by 2031, at a CAGR of 21.58% during the forecast period (2026-2031).
This report is Segmented by Component (Solutions and Services), Deployment (On-Premise and Cloud), Organization Size (Large Enterprises and Small and Medium Enterprises (SMEs)), Application (Predictive Maintenance, Asset Performance Management, Energy Management, and More), End-User Industry (Manufacturing, Energy and Utilities, Transportation and Logistics, Retail and E-Commerce, and More), and Geography.
Global IoT Analytics Market Trends and Insights
Proliferation of IoT Devices Generating Exabyte-Scale Data
Connected-device counts are rising sharply, with global IoT endpoints expected to produce more than 175 zettabytes of data annually by 2025. Plant-level sensor arrays already emit terabytes each day, forcing enterprises to deploy analytics engines at the edge to avoid cloud-backhaul delays. Manufacturers adopting this edge-first model record 30% higher operational efficiency versus cloud-only setups. The data surge spans structured telemetry, unstructured video, and log files, prompting investment in multimodal analytic frameworks that can handle diverse payloads concurrently.
Cloud-Native Analytics Platforms Gaining Enterprise Acceptance
Scalable, pay-as-you-go services such as Microsoft Azure IoT Operations allow firms to ingest billions of daily messages while cutting infrastructure outlays by up to 60%. Zero-trust architectures and built-in threat analytics lessen security concerns, accelerating full-cloud adoption in manufacturing and logistics. Highly regulated verticals continue to blend cloud and local processing, but migration momentum remains strong as providers extend compliance toolkits.
Data-Privacy and Cross-Border Compliance Complexity
GDPR imposes stringent consent, minimization, and localization rules; non-compliance can cost 4% of global turnover. Divergent national laws force firms to maintain multiple regional data stores, inflating project budgets by up to 25%. Real-time analytics crossing borders must incorporate policy-aware routing to satisfy sovereignty mandates, slowing enterprise rollouts.
Other drivers and restraints analyzed in the detailed report include:
- Predictive-Maintenance Demand Across Asset-Intensive Industries
- Edge-AI Accelerators Enabling Sub-Second Analytics
- Shortage of IoT Data-Science Talent Pool
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions continued to dominate, accounting for 67.95% revenue in 2025. The IoT analytics market size for solutions is forecast to increase steadily, yet the services category is set to expand faster at 23.12% CAGR as firms seek managed expertise. Professional services are in high demand for protocol mapping, edge-stack tuning, and multi-cloud integration.
The talent shortfall and rising architectural complexity make external partners attractive. Managed-service contracts often bundle software, infrastructure, and outcome-based SLAs, shifting risk to providers. Security-analytics sub-segments are buoyed by expanding attack surfaces tied to connected devices.
On-premise installations held 64.62% share in 2025, reflecting control, latency, and regulatory needs. Yet cloud instances are growing at 23.30% CAGR as hyperscalers couple ingestion pipelines with serverless analytic engines. Hybrid designs route time-critical workloads to edge nodes while sending aggregated data to the cloud for batch AI.
Microsoft and Amazon lead with composable offerings, enabling enterprises to spin up digital twins and large-scale model training within minutes. Supply-chain volatility and energy-price swings underline the need for elastic compute, further pushing cloud uptake.
Complete Report Scope:
- By Component
- Solutions
- Network Management
- Security Analytics
- Real-time Streaming Analytics
- Data Management and Storage Analytics
- Visualization and Dashboard
- Services
- Professional Services
- Managed Services
- Solutions
- By Deployment
- On-premise
- Cloud
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Application
- Predictive Maintenance
- Asset Performance Management
- Energy Management
- Supply-Chain and Logistics Optimisation
- Other Applications
- By End-User Industry
- Manufacturing
- Energy and Utilities
- Transportation and Logistics
- Retail and E-Commerce
- Healthcare and Life Sciences
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific delivered 35.86% of 2025 revenue, benefiting from government programs such as "Made in China 2025" and India's Smart Cities Mission. Regional CAGR of 22.84% underscores the scale of industrial digitization, 5G rollout, and edge-AI pilots. Chinese factories deploy vision-based quality control, while Indian municipalities apply sensor networks to manage waste and traffic.
North America follows closely, with mature cloud infrastructure and early AI adoption. Enterprises integrate streaming analytics with digital-operations centers, aided by robust venture funding and university research pipelines. The region remains a test-bed for autonomous-mobility and precision-agriculture projects.
Europe posts steady growth as ESG compliance drives real-time emissions monitoring. Initiatives under the European Green Deal push utilities and manufacturers toward data-driven efficiency. Emerging markets in Latin America and the Middle East gain momentum as telecom operators extend NB-IoT and 5G coverage, enabling greenfield deployments in logistics, oil, and public safety.
- Microsoft Corporation
- Amazon Web Services, Inc.
- IBM Corporation
- Google LLC
- Cisco Systems, Inc.
- Oracle Corporation
- SAP SE
- Dell Technologies Inc.
- The Hewlett Packard Enterprise Company
- Teradata Corporation
- Salesforce, Inc.
- Accenture plc
- PTC Inc.
- Hitachi Vantara LLC
- Cloudera, Inc.
- Software AG
- SAS Institute Inc.
- Splunk Inc.
- C3.ai, Inc.
- Uptake Technologies Inc.
- GE Digital
- QlikTech International AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of IoT devices generating exabyte-scale data
- 4.2.2 Cloud-native analytics platforms gaining enterprise acceptance
- 4.2.3 Predictive-maintenance demand across asset-intensive industries
- 4.2.4 Edge-AI accelerators enabling sub-second analytics at the edge
- 4.2.5 Enterprise data-fabric architectures unifying siloed IoT streams
- 4.2.6 ESG-driven sustainability monitoring mandates
- 4.3 Market Restraints
- 4.3.1 Data-privacy and cross-border compliance complexity
- 4.3.2 Shortage of IoT data-science talent pool
- 4.3.3 Industrial-protocol fragmentation hindering interoperability
- 4.3.4 Rising telemetry bandwidth costs for high-frequency sensors
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Network Management
- 5.1.1.2 Security Analytics
- 5.1.1.3 Real-time Streaming Analytics
- 5.1.1.4 Data Management and Storage Analytics
- 5.1.1.5 Visualization and Dashboard
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Solutions
- 5.2 By Deployment
- 5.2.1 On-premise
- 5.2.2 Cloud
- 5.3 By Organisation Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By Application
- 5.4.1 Predictive Maintenance
- 5.4.2 Asset Performance Management
- 5.4.3 Energy Management
- 5.4.4 Supply-Chain and Logistics Optimisation
- 5.4.5 Other Applications
- 5.5 By End-User Industry
- 5.5.1 Manufacturing
- 5.5.2 Energy and Utilities
- 5.5.3 Transportation and Logistics
- 5.5.4 Retail and E-Commerce
- 5.5.5 Healthcare and Life Sciences
- 5.5.6 Other End-User Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia and New Zealand
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Amazon Web Services, Inc.
- 6.4.3 IBM Corporation
- 6.4.4 Google LLC
- 6.4.5 Cisco Systems, Inc.
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Dell Technologies Inc.
- 6.4.9 The Hewlett Packard Enterprise Company
- 6.4.10 Teradata Corporation
- 6.4.11 Salesforce, Inc.
- 6.4.12 Accenture plc
- 6.4.13 PTC Inc.
- 6.4.14 Hitachi Vantara LLC
- 6.4.15 Cloudera, Inc.
- 6.4.16 Software AG
- 6.4.17 SAS Institute Inc.
- 6.4.18 Splunk Inc.
- 6.4.19 C3.ai, Inc.
- 6.4.20 Uptake Technologies Inc.
- 6.4.21 GE Digital
- 6.4.22 QlikTech International AB
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 自動化倉庫管理系統市場預測至2034年-按部署類型、產品/服務、服務類型、技術、倉庫類型、應用、最終使用者和地區分類的全球分析
 物聯網分析市場-2026-2032年全球市場預測
 供應鏈執行(SCE):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031)
 物聯網 (AoT) 市場規模、佔有率和成長分析:按組件、組織規模、技術、部署模式、應用類型、行業和地區分類 - 2026-2033 年行業預測
 物聯網分析市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034 年預測智慧數位貨架分析平台市場:按組件、部署模式、組織規模、分析類型和最終用戶產業分類,全球預測(2026-2032年)
 物聯網分析市場規模、佔有率和成長分析(按類型、組件、組織規模、部署模式、應用、最終用戶產業和地區分類)-2026-2033年產業預測
 物聯網分析市場-全球產業規模、佔有率、趨勢、機會和預測,按分析類型、服務類型、最終用戶、地區和競爭細分,2020-2030 年預測
 全球物聯網分析市場規模研究與預測,依組件、部署、類型、應用和區域預測,2025-2035
 全球物聯網分析市場,2024-2028