


 |
市場調查報告書
商品編碼
2122228
圖形處理器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Graphic Processors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
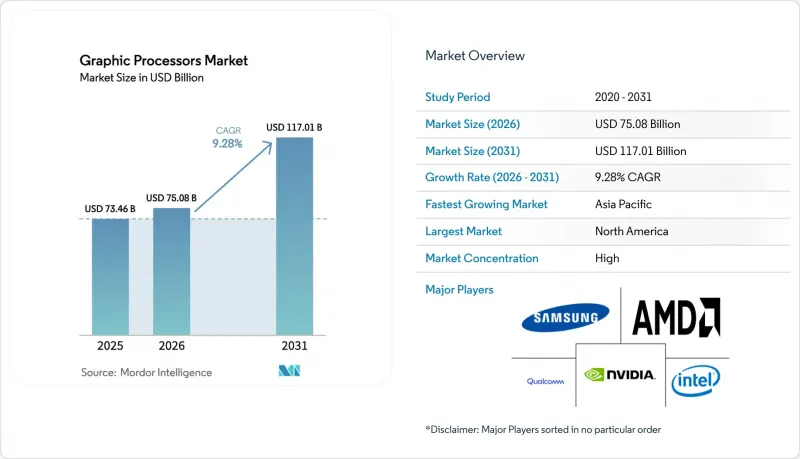
根據 Mordor Intelligence 預測,圖形處理器市場規模將從 2025 年的 734.6 億美元和 2026 年的 750.8 億美元成長到 2031 年的 1,170.1 億美元,2026 年至 2031 年的複合年成長率為 9.28%。
本報告按GPU類型(專用、整合、混合、外部)、部署模式(本地部署、雲端服務)、裝置平台(智慧型手機、平板電腦、遊戲PC和遊戲主機等)、終端用戶產業(家用電子電器、IT和電信、其他)、GPU架構(x86、ARM、RISC-V、專有架構)和地區進行細分。市場預測以美元(USD)計價。
全球圖形處理器市場趨勢與洞察
AAA級遊戲和即時射線追蹤。
即時射線追蹤已成為一項基本要求,領先的廠商將高達一半的晶片面積分配給光線三角形相交計算單元,以確保在 4K 解析度下達到每秒 60 幀的輸出。隨著 2025 年主機遊戲的升級和第二代射線追蹤核心的推出,最低效能要求進一步提高,推動獨立 GPU 的藍圖在 2027 年實現原生 8K 渲染。電競工作室正在採用路徑追蹤進行全局光照,以減輕美術人員的工作量,但這會使運算需求比光柵化管線高出三倍,從而擴大了 400-700 美元價位段的中端市場。訂閱制雲端遊戲平台現在為每個並髮用戶分配 1.2 個 GPU(2024 年為 0.8 個 GPU),以保持低於 50 毫秒的延遲,導致超大規模 GPU 池的高階產品供應緊張。到 2025 年,高階智慧型手機將配備混合射線追蹤模組,旗艦機型的 GPU搭載率將年增 18%。
人工智慧/深度學習工作負載激增
到2025年,訓練前緣模型所需的浮點運算次數將超過10^25,由16,384個加速器通過400 Gb/s的互連網路連接的集群能夠在90天內完成處理。推理過程正從批次轉向即時串流處理,針對INT8和FP16最佳化的Tensor Core將取代通用向量單元,成為首選。醫院正在50到100個地點部署聯邦學習框架,每個地點所需的GPU數量從2個增加到8個,以實現隱私保護的診斷。汽車製造商正在整合吞吐量為每秒200兆次運算的車載模組,以支援空中下載(OTA)更新,這將使組件成本增加800到1200美元,同時增強高階細分功能。量化交易部門透過基於 GPU 的強化學習,將策略開發週期從六個月縮短到三週,預計到 2025 年,這將使圖形處理器市場的採用率提高 22%。
先進節點(5奈米以下)的供應瓶頸
即使到了2025年,5奈米及以下製程的晶圓代工產能依然緊張。台積電將其N3製程晶圓開工量的60%分配給了智慧型手機處理器,導致大批量GPU訂單的前置作業時間延長至26週。三星3奈米製程的良率徘徊在70%左右,低於成本競爭力的閾值,迫使其轉向5奈米製程,而5奈米製程的每瓦性能降低了20%。英特爾位於亞利桑那州的工廠量產推遲了六個月,這延緩了美國設計公司獲得國內產能的進程,並延長了對台灣製造的依賴。擴大雙源供應需要12-18個月的聯合過程開發,限制了短期內供應來源的多元化。晶圓價格上漲8%進一步加劇了利潤率的壓力,抑制了圖形處理器市場的快速擴張。
細分市場分析
到2025年,獨立顯示卡仍將佔據圖形處理器市場40.22%的佔有率,這主要得益於熱插拔資料中心顯示卡簡化了維護流程。混合加速器預計將以9.83%的複合年成長率成長,這主要受統一記憶體需求的驅動,統一記憶體可以消除PCIe瓶頸,並將系統功耗降低25-30%。整合式顯示卡繼續主導筆記型電腦市場,因為散熱設計限制是影響因素之一;而外置顯示卡盒則面向尋求臨時效能提升的行動裝置使用者。然而,由於Thunderbolt頻寬的上限,它們的利用率通常只能達到70-80%。
基於晶片組的混合產品將 3nm CPU 核心與 5nm GPU 模組結合,在保持競爭力吞吐量的同時,兼顧良率和成本。獨立推理板整合了稀疏引擎,在不增加面積下,可將變壓器模型中的有效吞吐量提升高達 60%。在外部 GPU 生態系統中,廠商正在探索採用專用連接器來克服 Thunderbolt 5 的限制。
預計到2025年,本地部署將佔圖形處理器市場收入的72.91%,因為對延遲敏感且具有自主性的工作負載仍然依賴本地叢集。受按秒收費模式的推動,雲端即服務(Cloud-as-a-Service)預計將以10.02%的年成長率成長,這種模式鼓勵深度學習實驗和突發容量利用。金融和醫療保健營運商出於合規性考慮,在本地進行關鍵培訓,同時將尖峰負載分配到託管資料中心,從而推動了對混合編配的需求。
現貨GPU價格在不同地區之間波動高達50%至80%,工作負載調度器正在調整作業以最佳化成本。硬體更新週期從3.2年延長至4.5年,反映了謹慎的資本投資和軟體效率的提升。預留容量合約可提供35%至45%的折扣,但當新一代晶片上市時,客戶將面臨產品世代鎖定的風險。
區域分析
到2025年,北美將佔全球銷售額的37.81%,這主要得益於維吉尼亞、奧勒岡州和德克薩斯州超大規模資料中心的擴張。這些地區的高階產品出貨量佔全球一半以上。亞太地區預計將以11.52%的複合年成長率成長,這主要得益於中國和印度政府主導的人工智慧項目,這些項目優先發展國產晶片和在地化模型訓練。在歐洲,能源成本上漲導致營運支出增加18%至22%,延緩了圖形處理器市場的更新換代,並導致成長較為溫和。
在中東,各國正投資打造人工智慧禁區,其中阿拉伯聯合大公國和沙烏地阿拉伯運作了超過1萬個加速器叢集,用於建構阿拉伯語大規模語言模式(LLM)。非洲和南美洲的智慧型手機GPU普及率總合不到5%,而巴西、奈及利亞和南非的智慧型手機GPU搭載率卻成長了25%至30%,這主要得益於電信業者擴大了貸款業務。
在中國,受高頻寬互連法規的影響,進口量下降了12%,促使阿里巴巴旗下的「T-Head」和「Biren」轉向國內研發,目標是在2025年底前達到NVIDIA A100性能的70-80%。日本已撥款23億美元建造國家人工智慧叢集,該集群將配備15,000個GPU,用於訓練語言模型,而無需依賴美國雲端服務。印度的半導體獎勵計畫已獲得18億美元的投資承諾,但其前端晶圓廠仍需三年才能投入運作。德國和法國聯合資助了一個GPU研發項目,但其產品在能源效率方面比商用產品落後18-24個月。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- AAA級遊戲和即時射線追蹤。
- 人工智慧/深度學習工作負載的激增
- 雲端遊戲和GPU即服務的擴展
- 晶片組和先進封裝技術的突破性進展
- 政府主導的百萬兆級超級運算計劃
- 用於汽車應用的 Arm/RISC-V 客製化 GPU
- 市場限制因素
- 尖端節點(5奈米以下)的供應瓶頸
- 平均售價(ASP)過高阻礙了其廣泛應用。
- 高階GPU出口限制
- 引入熱圍護結構(功率超過 600 瓦)的限制
- 產業價值鏈分析
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 按GPU類型
- 專用(獨立)GPU
- 整合顯示卡
- 混合型GPU(APU)
- 外置顯示卡(eGPU機箱)
- 按部署模式
- 現場
- Cloud-as-a-service
- 按設備平台
- 智慧型手機
- 藥片
- 遊戲電腦和遊戲主機
- 工作站
- 資料中心伺服器
- 汽車資訊娛樂系統與高級駕駛輔助系統
- 按最終用戶行業分類
- 家用電子產品
- IT/通訊
- 媒體與娛樂
- 車
- 國防與資訊
- 醫療保健和生命科學
- GPU架構
- 基於 x86 的 GPU
- 基於ARM的GPU
- 基於 RISC-V 的 GPU
- 專有規範/其他ISA
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- NVIDIA Corporation
- Advanced Micro Devices, Inc.
- Intel Corporation
- Samsung Electronics Co., Ltd.
- Qualcomm Incorporated
- Apple Inc.
- Arm Ltd.
- Imagination Technologies Limited
- MediaTek Inc.
- VIA Technologies, Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- IBM Corporation
- Sony Group Corporation
- Graphcore Limited
- Tenstorrent Inc.
- ZOTAC Technology Limited
- Micro-Star International Co., Ltd.
- ASUSTeK Computer Inc.
- Giga-Byte Technology Co., Ltd.
- EVGA Corporation
- Blaize, Inc.
- Cerebras Systems Inc.
- Alibaba Group Holding Limited(T-Head)
第7章 市場機會與未來展望
According to Mordor Intelligence, the graphic processors market size is projected to expand from USD 73.46 billion in 2025 and USD 75.08 billion in 2026 to USD 117.01 billion by 2031, registering a CAGR of 9.28% between 2026 to 2031.
This report is Segmented by GPU Type (Dedicated, Integrated, Hybrid, and External), Deployment Model (On-Premise, and Cloud-As-A-Service), Device Platform (Smartphones, Tablets, Gaming PCs and Consoles, and More), End-User Industry (Consumer Electronics, IT and Telecom, and More), GPU Architecture (x86, ARM, RISC-V, and Proprietary), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Graphic Processors Market Trends and Insights
Surging Demand for AAA Gaming and Real-Time Ray Tracing
Real-time ray tracing has become a baseline expectation, leading vendors to devote up to half of the die area to ray-triangle intersection units that sustain 60 frames-per-second output at 4K resolution. Console refreshes in 2025 injected second-generation ray-tracing cores, lifting the performance floor and pushing discrete GPU roadmaps toward native 8K rendering by 2027. Esports studios are adopting path-traced global illumination to curb artist workloads, tripling compute requirements over raster pipelines and expanding the mid-tier segment priced between USD 400 and USD 700. Subscription cloud gaming platforms now reserve 1.2 GPUs per concurrent user to preserve sub-50-millisecond latency, up from 0.8 in 2024, tightening high-end supply for hyperscale GPU pools. Premium smartphones integrated hybrid ray-tracing blocks in 2025, lifting flagship handset GPU attach rates by 18% year over year.
Proliferation of AI/Deep Learning Workloads
Frontier model training exceeded 10^25 floating-point operations in 2025, prompting clusters with 16,384 accelerators linked via 400 Gb/s fabrics to complete runs within 90 days. Inference is moving from batch to real-time streams, favoring tensor cores optimized for INT8 and FP16 over generic vector units. Hospitals deployed federated learning frameworks across 50-100 sites, raising per-site GPU needs from 2 to 8 units for privacy-preserving diagnostics. Automakers fitted on-vehicle modules with 200-tera-operations-per-second throughput to support over-the-air updates, adding USD 800-USD 1,200 to bill-of-materials and reinforcing premium-trim segmentation. Quantitative trading desks cut strategy development cycles from 6 months to 3 weeks through GPU-based reinforcement learning, triggering 22% deployment growth in 2025 in the graphic processors market.
Advanced-Node Supply Bottlenecks (<=5 nm)
Foundry capacity at 5 nm and below remained tight in 2025, as TSMC allocated 60% of N3 wafer starts to smartphone processors, pushing GPU lead times to 26 weeks for volume orders. Samsung's 3 nm yields hovered near 70%, below cost-competitive thresholds, forcing fallback to 5 nm nodes at 20% lower performance per watt. Intel's Arizona ramp slipped six months, delaying domestic capacity for U.S. designers and prolonging reliance on Taiwan fabrication. Dual-sourcing expansions require 12-18 months of process-co-development, limiting near-term diversification. Wafer price inflation of 8% compounded margin compression and curbed aggressive expansion in the graphic processors market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Cloud Gaming and GPU-as-a-Service
- Chiplet and Advanced Packaging Breakthroughs
- High ASPs Limiting Mainstream Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dedicated discrete boards retained a 40.22% stake in 2025 in the graphic processors market, driven by hot-swappable data center cards that simplify maintenance windows. Hybrid accelerators are forecast to grow at a 9.83% CAGR amid demand for unified memory that eliminates PCIe bottlenecks and cuts system power by 25-30%. Integrated GPUs continue to dominate thermally constrained laptops, whereas external enclosures target mobile creatives seeking episodic boosts but are hampered by Thunderbolt bandwidth ceilings that cap utilization at 70-80%.
Chiplet-based hybrids combine 3 nm CPU cores with 5 nm GPU tiles, balancing yield and cost while sustaining competitive throughput. Discrete inference boards introduced sparsity engines that raise effective throughput by up to 60% on transformer models without area penalties. External GPU ecosystems are exploring proprietary connectors to overcome Thunderbolt 5 constraints.
The on-premise segment captured 72.91% of 2025 revenue in the graphic processors market, as latency-sensitive or sovereign workloads remained tethered to local clusters. Cloud-as-a-service is projected to grow 10.02% annually, driven by second-based billing that attracts deep learning experimentation and burst capacity. Financial and healthcare operators keep primary training on site for compliance but burst peak loads to co-located regions, creating hybrid orchestration demand.
Spot GPU prices have varied by 50-80% across zones, prompting workload schedulers to migrate jobs to optimize costs. Lengthening hardware refresh cycles from 3.2 to 4.5 years reflects cautious capital expenditure and software-side efficiency gains. Reserved-capacity contracts offer 35-45% discounts but expose clients to generation-lock-in risk as new silicon lands.
Complete Report Scope:
- By GPU Type
- Dedicated (Discrete) GPUs
- Integrated GPUs
- Hybrid GPUs (APUs)
- External GPUs (eGPU Enclosures)
- By Deployment Model
- On-Premise
- Cloud-as-a-service
- By Device Platform
- Smartphones
- Tablets
- Gaming PCs and Consoles
- Workstations
- Data-center Servers
- Automotive Infotainment and ADAS
- By End-User Industry
- Consumer Electronics
- IT and Telecom
- Media and Entertainment
- Automotive
- Defense and Intelligence
- Healthcare and Life Sciences
- By GPU Architecture
- x86-based GPUs
- ARM-based GPUs
- RISC-V-based GPUs
- Proprietary/Other ISAs
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America contributed 37.81% of 2025 revenue, driven by hyperscale build-outs in Virginia, Oregon, and Texas, which accounted for over half of global high-end shipments. Asia-Pacific is projected to expand at an 11.52% CAGR, underpinned by sovereign-AI programs in China and India that prioritize domestic silicon and localized model training. Europe registered moderate growth, as energy tariffs inflated operating expenses by 18-22%, prompting delays in refreshes in the graphic processors market.
Middle East investments established AI-free zones, where the United Arab Emirates and Saudi Arabia commissioned clusters of more than 10,000 accelerators to build Arabic LLMs. Africa and South America contributed under 5% combined, though smartphone GPU attachment in Brazil, Nigeria, and South Africa rose 25-30% with carrier financing expansion.
China's imports fell 12% after high-bandwidth interconnect restrictions, prompting domestic efforts at Alibaba's T-Head and Biren to achieve 70-80% of NVIDIA A100 performance by late-2025. Japan allocated USD 2.3 billion to national AI clusters totaling 15,000 GPUs to train language models without relying on U.S. cloud services. India's semiconductor incentive attracted USD 1.8 billion commitments, though front-end fabs remain three years out. Germany and France co-funded GPU R&D projects but trailed commercial offerings by 18-24 months in power efficiency.
- NVIDIA Corporation
- Advanced Micro Devices, Inc.
- Intel Corporation
- Samsung Electronics Co., Ltd.
- Qualcomm Incorporated
- Apple Inc.
- Arm Ltd.
- Imagination Technologies Limited
- MediaTek Inc.
- VIA Technologies, Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- IBM Corporation
- Sony Group Corporation
- Graphcore Limited
- Tenstorrent Inc.
- ZOTAC Technology Limited
- Micro-Star International Co., Ltd.
- ASUSTeK Computer Inc.
- Giga-Byte Technology Co., Ltd.
- EVGA Corporation
- Blaize, Inc.
- Cerebras Systems Inc.
- Alibaba Group Holding Limited (T-Head)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand For AAA Gaming and Real-Time Ray Tracing
- 4.2.2 Proliferation Of AI/Deep Learning Workloads
- 4.2.3 Expansion Of Cloud Gaming and GPU-As-A-Service
- 4.2.4 Chiplet and Advanced Packaging Breakthroughs
- 4.2.5 Govt-Backed Exascale Supercomputing Programs
- 4.2.6 Arm/Risc-V Automotive-Grade Custom GPUs
- 4.3 Market Restraints
- 4.3.1 Advanced-Node Supply Bottlenecks (Less than or Equal to 5 Nm)
- 4.3.2 High ASPs Limiting Mainstream Adoption
- 4.3.3 Export Controls On High-End GPUs
- 4.3.4 Thermal Envelope (Greater than 600 W) Deployment Limits
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By GPU Type
- 5.1.1 Dedicated (Discrete) GPUs
- 5.1.2 Integrated GPUs
- 5.1.3 Hybrid GPUs (APUs)
- 5.1.4 External GPUs (eGPU Enclosures)
- 5.2 By Deployment Model
- 5.2.1 On-Premise
- 5.2.2 Cloud-as-a-service
- 5.3 By Device Platform
- 5.3.1 Smartphones
- 5.3.2 Tablets
- 5.3.3 Gaming PCs and Consoles
- 5.3.4 Workstations
- 5.3.5 Data-center Servers
- 5.3.6 Automotive Infotainment and ADAS
- 5.4 By End-User Industry
- 5.4.1 Consumer Electronics
- 5.4.2 IT and Telecom
- 5.4.3 Media and Entertainment
- 5.4.4 Automotive
- 5.4.5 Defense and Intelligence
- 5.4.6 Healthcare and Life Sciences
- 5.5 By GPU Architecture
- 5.5.1 x86-based GPUs
- 5.5.2 ARM-based GPUs
- 5.5.3 RISC-V-based GPUs
- 5.5.4 Proprietary/Other ISAs
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 NVIDIA Corporation
- 6.4.2 Advanced Micro Devices, Inc.
- 6.4.3 Intel Corporation
- 6.4.4 Samsung Electronics Co., Ltd.
- 6.4.5 Qualcomm Incorporated
- 6.4.6 Apple Inc.
- 6.4.7 Arm Ltd.
- 6.4.8 Imagination Technologies Limited
- 6.4.9 MediaTek Inc.
- 6.4.10 VIA Technologies, Inc.
- 6.4.11 Taiwan Semiconductor Manufacturing Company Limited
- 6.4.12 IBM Corporation
- 6.4.13 Sony Group Corporation
- 6.4.14 Graphcore Limited
- 6.4.15 Tenstorrent Inc.
- 6.4.16 ZOTAC Technology Limited
- 6.4.17 Micro-Star International Co., Ltd.
- 6.4.18 ASUSTeK Computer Inc.
- 6.4.19 Giga-Byte Technology Co., Ltd.
- 6.4.20 EVGA Corporation
- 6.4.21 Blaize, Inc.
- 6.4.22 Cerebras Systems Inc.
- 6.4.23 Alibaba Group Holding Limited (T-Head)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 2026年人工智慧圖形處理器(GPU)全球市場報告2026年深度學習圖形處理器(GPU)全球市場報告2026年全球混合圖形處理器(GPU)市場報告
 全球圖形處理器(GPU)市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 GPU(影像處理)市場:按產品類型、記憶體類型、散熱方式、部署方式、應用和最終用戶分類 - 全球市場預測(2026-2032 年)
 GPU代工廠:市佔率分析、產業趨勢與統計、成長預測(2026-2031年)GPU網路:市佔率分析、產業趨勢與統計、成長預測(2026-2031年)GPU軟體:市佔率分析、產業趨勢與統計、成長預測(2026-2031年)機架式GPU:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)CAD/CAM GPU:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)