


 |
市場調查報告書
商品編碼
2121915
鈮:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Niobium - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
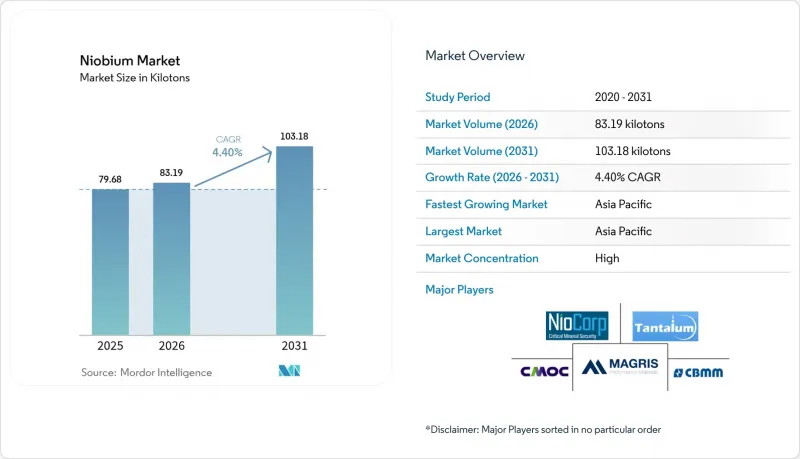
根據 Mordor Intelligence 預測,鈮市場規模將從 2025 年的 79.68 千噸成長到 2026 年的 83.19 千噸,到 2031 年將達到 103.18 千噸,2026 年至 2031 年的複合成長率為 4.4%。
本報告依產狀(碳酸岩及相關礦物、鈮鐵礦和鉭鐵礦)、類型(鈮鐵礦、氧化鈮等)、應用(鋼鐵、高溫合金、超導性磁體和電容器等)、最終用戶業(建築、汽車和造船、航太和國防等)以及地區(亞太地區、北美、歐洲、南美洲、中東和非洲)進行分類。
全球鈮市場趨勢與洞察
建設產業中高強度、高抗張強度鋼(HSLA)的應用日益廣泛
為增強抗震性能,建築規範的修訂要求更高的強度重量比。含鈮量為0.02%至0.05%的高強高抗張強度(HSLA)鋼,其強度比傳統鋼材增加20%至30%,同時也能減少鋼材用量。中國2024年抗震標準明確要求高樓工程使用鈮微量合金鋼,印尼和墨西哥也考慮類似的修訂。雖然材料成本僅增加5%至8%,但結構鋼用量可減少高達20%,促使工程公司將鈮規範納入長期基礎設施規劃。隨著亞洲和非洲新一輪都市化浪潮的加速,建築需求佔鈮總消費量的49%以上,鞏固了鈮市場的穩定基礎。監管方面的進展將使 HSLA 的採用在未來 10 年內幾乎不可逆轉。
促進汽車和造船業的減重
更嚴格的燃油效率目標和海事排放氣體法規正在推動積極的減重策略。鈮增強型先進高強度鋼目前已應用於超過60%的高階車型,並且隨著汽車製造商在電池帶來的重量增加與碰撞安全性之間尋求平衡,這種鋼材的應用範圍正在擴展到大眾市場車型平台。在造船領域,鈮增強型低溫高強度低合金鋼板在-162 度C的低溫下即可滿足液化天然氣裝運船隻的斷裂韌性要求,從而支持韓國和卡達的船隊現代化改造。商用卡車和鐵路車輛製造商也同樣採用鈮增強樑和底盤零件,在無需重大設計變更的情況下提高裝載效率。這種跨交通運輸領域的應用循環使鈮市場能夠跨多個產業產生協同效應,而不僅依賴單一產業。
急性暴露引起的健康與環境問題
由於鈮礦石通常含有釷和鈾,因此採礦過程中必須進行嚴格的輻射監測。巴西監管機構現在要求在續簽許可證時進行基準地下水調查和同位素測繪,這使得合規成本增加了15%至25%。關於原住民領土的爭議進一步延緩了新開發案的核准,加拿大「火環」地區也面臨類似的社區參與挑戰。雖然目前尚未有工業暴露水平下出現慢性中毒病例的報告,但公眾對風險的擔憂可能會影響投資決策,並阻礙供應側的靈活性。
細分市場分析
到2025年,碳酸岩礦床將佔全球鈮供應量的95.85%,預計到2031年將以4.43%的複合年成長率成長,從而支撐鈮市場的成長。巴西的阿拉沙礦是生產鐵鈮的典範,其營運成本具有競爭力,生產的粗粒燒綠石具有較低的剝採比,有利於選礦。
目前,探勘投資主要集中在格陵蘭島和坦尚尼亞地表下的碳酸岩蘊藏量,但尚未發現規模與阿拉沙礦相當的礦藏,這進一步加劇了現有供應集中的趨勢。可預測的礦物成分和數十年的冶金技術經驗確保了穩定的加工量,這構成了長期供應合約的基礎,並鞏固了鈮市場的價格穩定。日本和德國的戰略儲備公司繼續青睞碳酸岩原料,因為其雜質組成穩定,有助於簡化合金廠的品管。
預計到2025年,鈮鐵合金的出貨量將佔全球出貨量的92.75%,並將以4.35%的複合年成長率持續成長至2031年。這反映了全球粗鋼需求的成長趨勢。通常含鈮量為65%的中間合金可無縫整合到鹼性氧氣轉爐煉鋼製程中,使熔煉廠技術人員能夠精確控制晶粒尺寸和析出動力學。儘管氧化鈮目前的市場佔有率較小,但由於其在電池和介電陶瓷領域的應用日益廣泛,需求正在成長。 CBMM的專用氧化鈮生產線計畫在2030年實現年產4萬噸的目標。
真空級金屬和特殊合金粉末廣泛應用於航太引擎、核磁共振磁體、量子元件等領域,儘管交易量較低,但其單價仍然很高。隨著積層製造技術的普及,球形C-103粉末的需求量可能超過塊狀板材和棒材,進而推動加工商收入來源多元化。因此,儘管鈮鐵仍將是銷售量主力,但高純度衍生產品可能會影響鈮產業的整體利潤率趨勢。
區域分析
預計到2025年,亞太地區將佔全球鈮總出貨量的60.10%,並在2031年之前以4.71%的複合年成長率成長,從而佔據鈮市場最大的區域佔有率。中國龐大的鋼鐵產量和不斷完善的抗震標準支撐了鈮的大宗需求,而採用鈮矽合金的航太計畫正在擴大其在下一代推進系統中的應用。
北美經濟成長的關鍵在於兩大主題:交通工具的脫碳以及國防主導的高超音速技術發展。美國環保署(EPA)日益嚴格的燃油效率法規以及各州的零排放強制令,迫使汽車製造商採用富鈮鋼來減輕底盤重量,並平衡日益沉重的電池系統的重量。儘管加拿大尼奧貝克礦供應了全球約8-10%的鈮,但美國決策者仍將透過埃爾克溪計畫實現鈮源多元化作為一項戰略挑戰,以減少對巴西進口的依賴。
在歐洲,人們正努力透過擴建氫氣管道來實現淨零排放目標,而這些管道需要使用鈮尖API X70級鋼材。此外,由於汽車二氧化碳排放法規日益嚴格,汽車沖壓件中也持續採用高抗張強度鋼。德國汽車產業叢集透過添加鈮鐵合金,實現了車身本體組件的輕量化。同時,挪威的礦產策略已將鈮列為國內探勘的優先領域,並修訂了相關許可法規。該地區也正在支持歐洲核子研究中心(CERN)加速器升級所需的鈮錫超導性的基礎研究,從而在更廣泛的鈮市場中維持著一個以研究主導的細分市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 建設產業對高強度低合金鋼的應用日益廣泛
- 促進汽車和造船業的減重
- 氫氣和液化天然氣運輸管道的建設
- 鈮摻雜鋰離子電池的大規模生產
- 利用積層製造技術製造鈮合金,用於航太領域
- 市場限制因素
- 巴西的供應和定價權集中
- 急性暴露引起的健康與環境問題
- ESG可追溯性合規成本
- 波特五力模型
- 技術概述/生產分析
- 價格趨勢
第5章 市場規模與成長預測
- 按產狀
- 碳酸岩及相關礦物
- 鈮鉭鐵礦
- 按類型
- 費羅尼奧布
- 氧化鈮
- 鈮金屬
- 用於真空的鈮合金
- 透過使用
- 鋼
- 超合金
- 超導性磁鐵和電容器
- 電池
- 其他
- 按最終用戶行業分類
- 建造
- 汽車和造船業
- 航太/國防
- 石油和天然氣
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 俄羅斯
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Admat Inc.
- American Elements
- Australian Strategic Materials Ltd
- CBMM
- Changsha South Tantalum Niobium Co. Ltd
- CMOC
- Grandview Materials
- Magris Performance Materials
- NioCorp Development Ltd
- Titanex GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the niobium market size is expected to grow from 79.68 kilotons in 2025 to 83.19 kilotons in 2026 and is forecast to reach 103.18 kilotons by 2031 at 4.4% CAGR over 2026-2031.
This report is Segmented by Occurrence (Carbonatites and Associates and Columbite-Tantalite), Type (Ferroniobium, Niobium Oxide, and More), Application (Steel, Super-Alloys, Superconducting Magnets and Capacitors, and More), End-User Industry (Construction, Automotive and Shipbuilding, Aerospace and Defense, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Niobium Market Trends and Insights
Rising HSLA Steel Adoption in Construction
Building-code revisions now mandate higher strength-to-weight ratios for seismic resilience, and HSLA steels containing 0.02-0.05% niobium deliver 20-30% strength gains over conventional grades while cutting tonnage requirements. China's 2024 seismic standards explicitly cite niobium-microalloyed steels for high-rise projects, and similar updates are under review in Indonesia and Mexico. Because material cost premiums remain 5-8% yet structural steel volumes fall by up to 20%, engineering firms are embedding niobium specifications across long-term infrastructure plans. As new urbanization waves in Asia and Africa accelerate, construction demand anchors more than 49% of overall niobium consumption, reinforcing a stable baseline for the niobium market. Regulatory momentum makes HSLA adoption essentially irreversible within a decade horizon.
Lightweighting Push in Automotive and Shipbuilding
Stricter fuel-economy targets and maritime emission limits foster aggressive mass-reduction strategies. Advanced high-strength steels incorporating niobium now appear in over 60% of premium-segment vehicles and are migrating into mass-market platforms as OEMs balance crashworthiness with battery-induced weight penalties. In shipbuilding, cryogenic-grade HSLA plate with niobium additions satisfies LNG-carrier requirements for fracture toughness at -162 °C, supporting fleet renewal across South Korea and Qatar. Commercial trucking and railcar builders likewise gravitate toward niobium-enhanced beam and chassis components, improving payload efficiency without major design overhauls. The cross-modal adoption cycle positions the niobium market for multi-industry synergies rather than single-sector dependency.
Acute-exposure Health and Environmental Concerns
Niobium ores often coexist with thorium and uranium, necessitating strict radiological surveillance during mining. Regulatory authorities in Brazil now require groundwater baselines and isotopic mapping before license renewals, adding 15-25% to compliance costs. Indigenous-territory debates further delay greenfield approvals, and similar community-engagement hurdles appear in Canada's Ring of Fire region. While no chronic-toxicity cases have been documented at industrial exposure levels, public perception risks can influence capex decisions, tempering supply-side agility.
Other drivers and restraints analyzed in the detailed report include:
- Pipeline Build-out for Hydrogen and LNG Transmission
- Niobium-doped Li-ion Batteries Scale-up
- ESG Traceability Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carbonatite-hosted deposits held 95.85% of the 2025 global supply and are set to expand at a 4.43% CAGR through 2031, underpinning the niobium market size growth trajectory. Brazil's Araxa mine exemplifies low-strip ratios and coarse-grained pyrochlore that simplify beneficiation, yielding ferroniobium at competitive opex levels.
Exploration spending now targets undercover carbonatites in Greenland and Tanzania; however, no discovery approaches Araxa's scale, reinforcing existing supply concentration. Predictable mineralogy and decades of metallurgical know-how translate into steady throughput, anchoring long-term delivery contracts and reinforcing the niobium market's pricing stability. Strategic stockpilers in Japan and Germany continue to favor carbonatite feed due to consistent impurity profiles that streamline alloy-shop quality control.
Ferroniobium accounted for 92.75% of 2025 shipments and is forecast to post a 4.35% CAGR through 2031, mirroring global crude-steel demand patterns. The master alloy, usually containing 65% niobium, integrates seamlessly into basic-oxygen furnace practices, enabling melt-shop engineers to fine-tune grain size and precipitation kinetics. Niobium oxide, while representing a minor share today, is pacing up on the back of battery and dielectric-ceramic uptake; CBMM's dedicated oxide line targets 40,000 tons annual capacity by 2030.
Vacuum-grade metal and specialty alloy powders feed aerospace engines, MRI magnets, and quantum devices, commanding premium unit values in spite of small tonnages. As additive manufacturing spreads, demand for spherical C-103 powder is likely to outpace bulk plate and bar, diversifying revenue streams for converters. Consequently, ferroniobium will remain the volume anchor, but high-purity derivatives will shape margin dynamics across the niobium industry.
Complete Report Scope:
- By Occurrence
- Carbonatites and Associates
- Columbite-Tantalite
- By Type
- Ferroniobium
- Niobium Oxide
- Niobium Metal
- Vacuum-grade Nb Alloys
- By Application
- Steel
- Super-alloys
- Superconducting Magnets and Capacitors
- Batteries
- Other Applications
- By End-user Industry
- Construction
- Automotive and Shipbuilding
- Aerospace and Defense
- Oil and Gas
- Other End-users
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Russia
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 60.10% of 2025 global volume and is forecast to grow at a 4.71% CAGR to 2031, securing the largest regional slice of the niobium market. China's gargantuan steel output and evolving seismic codes sustain bulk demand, while aerospace programs exploring niobium-silicon alloys extend uptake into next-generation propulsion systems.
North America's growth hinges on dual themes: decarbonization of transport fleets and defense-driven hypersonic development. Tightened EPA fuel-economy rules and state-level zero-emission mandates push OEMs toward niobium-enriched steels for chassis mass reduction, counterbalancing heavier battery systems. Canada's Niobec mine supplies roughly 8-10% of global output, but U.S. policymakers continue to view diversification via Elk Creek as a strategic imperative to curb reliance on Brazilian imports.
Europe targets net-zero targets by expanding hydrogen pipelines that demand niobium-microalloyed API X70 grades, and stringent vehicle CO2 limits sustain high-strength steel penetration in automotive stamping. Germany's auto clusters integrate ferroniobium additions to deliver lighter body-in-white assemblies, while Norway's mineral strategy lists niobium as a priority for domestic exploration under revised permitting rules. The region also supports fundamental research into niobium-tin superconductors for CERN's accelerator upgrades, sustaining a research-driven niche inside the broader niobium market.
- Admat Inc.
- American Elements
- Australian Strategic Materials Ltd
- CBMM
- Changsha South Tantalum Niobium Co. Ltd
- CMOC
- Grandview Materials
- Magris Performance Materials
- NioCorp Development Ltd
- Titanex GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising HSLA Steel Adoption in Construction
- 4.2.2 Lightweighting Push in Automotive and Shipbuilding
- 4.2.3 Pipeline Build-Out for Hydrogen and LNG Transmission
- 4.2.4 Niobium-Doped Li-Ion Batteries Scale-Up
- 4.2.5 Additive-Manufactured Nb Alloys for Aerospace
- 4.3 Market Restraints
- 4.3.1 Supply Concentration in Brazil and Pricing Power
- 4.3.2 Acute-Exposure Health and Environmental Concerns
- 4.3.3 ESG Traceability Compliance Costs
- 4.4 Porter's Five Forces
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Degree of Competition
- 4.5 Technological Snapshot/ Production Analysis
- 4.6 Price Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Occurrence
- 5.1.1 Carbonatites and Associates
- 5.1.2 Columbite-Tantalite
- 5.2 By Type
- 5.2.1 Ferroniobium
- 5.2.2 Niobium Oxide
- 5.2.3 Niobium Metal
- 5.2.4 Vacuum-grade Nb Alloys
- 5.3 By Application
- 5.3.1 Steel
- 5.3.2 Super-alloys
- 5.3.3 Superconducting Magnets and Capacitors
- 5.3.4 Batteries
- 5.3.5 Other Applications
- 5.4 By End-user Industry
- 5.4.1 Construction
- 5.4.2 Automotive and Shipbuilding
- 5.4.3 Aerospace and Defense
- 5.4.4 Oil and Gas
- 5.4.5 Other End-users
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Russia
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Admat Inc.
- 6.4.2 American Elements
- 6.4.3 Australian Strategic Materials Ltd
- 6.4.4 CBMM
- 6.4.5 Changsha South Tantalum Niobium Co. Ltd
- 6.4.6 CMOC
- 6.4.7 Grandview Materials
- 6.4.8 Magris Performance Materials
- 6.4.9 NioCorp Development Ltd
- 6.4.10 Titanex GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 高純度鈮金屬市場規模:依產品類型、終端用戶產業、地區及預測分類。
 五氧化二鈮市場-2026-2032年全球市場預測
 鈮棒市場規模、佔有率和成長分析:按產品類型、形狀和規格、應用領域、終端用戶產業和地區分類-2026-2033年產業預測
 五氧化二鈮:市場佔有率分析、產業趨勢與統計、成長預測(2025-2031)
 四甲基庚二酮鈮市場規模、佔有率和成長分析:按產品等級/純度、應用/製程技術、最終用途、最終用途產業和地區分類 - 產業預測,2026-2033年2026-2034年全球五氧化二鈮市場規模、佔有率、趨勢和成長分析報告鈮及鈮合金市場按類型、應用、終端用戶產業、形態、等級及生產方法分類-2026-2032年全球預測
 五氧化二鈮市場規模、佔有率及成長分析(按等級、應用和地區)-產業預測,2025-2032
 全球五氧化二鈮市場
 2032 年鈮市場預測:按類型、純度等級、通路、應用、最終用戶和地區進行的全球分析