


 |
市場調查報告書
商品編碼
2121466
文件管理系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Document Management Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
文檔管理系統市場預計將從 2025 年的 104.8 億美元和 2026 年的 118.1 億美元成長到 2031 年的 213.9 億美元,2026 年至 2031 年的複合年成長率為 12.61%。
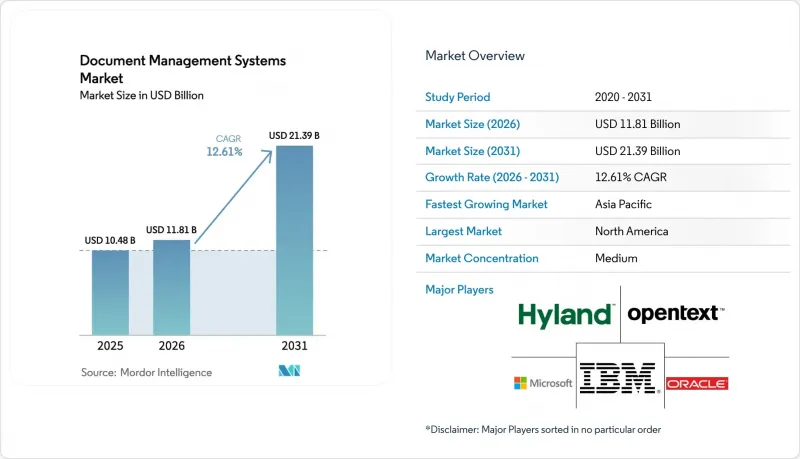
本報告按組件(軟體和服務)、部署模式(雲端和本地部署)、最終用戶產業(銀行和金融服務、製造和建築業及其他)以及地區(北美、南美、歐洲、亞太、中東和非洲)進行細分。市場預測以美元計價。
全球文件管理系統市場趨勢及洞察
快速過渡到無紙化社會
政府法規正以遠超自願永續發展努力的速度加速數位化進程。美國國家檔案館要求所有聯邦機構在2026年12月前完成永久保存記錄的數位化。日本數位廳已指示所有都道府縣在2025年4月前實施無紙化工作流程,導致採購量激增35%。Canon在2025年透過其雲端掃描服務處理180億頁文件,比2024年成長22%。這清晰地表明,大量模擬內容正湧入儲存庫。雖然採集量的增加降低了儲存成本,但也增加了元資料標記所需的工作量。這種權衡促使人們傾向於使用人工智慧驅動的自動分類,而非手動索引。因此,各公司優先考慮整合式機器學習增強器的平台,這些平台既能顯著降低營運成本,又能滿足合規要求。
整合到協作套件中的雲端原生DMS平台
超大規模資料中心業者現在正繞過耗時的採購流程,直接將儲存庫整合到其協作工具中。微軟於 2024 年 3 月發布了 SharePoint Embedded,到 2025 年 1 月,已有超過 200 家獨立軟體供應商 (ISV) 採用了該服務。 Box 於 2025 年 6 月增強了與 Google Workspace 的整合,使試點公司的版本控制錯誤減少了 40%。捆綁式解決方案的價格通常高出 15-20%,以確保互通性,這迫使僅提供文件管理系統 (DMS) 的供應商在特定行業領域的專業化競爭上展開角逐,而不是在通用功能上競爭。
使用者對受監管的後勤部門營運變革存在強烈的抵觸情緒。
德勤的一項調查顯示,38%的金融服務合規負責人對數位簽章的證據效力持懷疑態度,仍堅持列印並手動審核提交的文件。在公證強制執行的大陸法系國家,混合流程仍然普遍存在,導致變革管理專案週期延長至兩年,每家公司的培訓預算也從50萬增加到200萬美元。這種阻力正在延緩投資回報的實現,並阻礙雲端遷移的腳步。
細分市場分析
由於遷移的複雜性、人工智慧調優的需求以及超越內部技能的合規策略的開發,服務市場正以17.21%的複合年成長率擴張。 KnowledgeLake在六週內將4.5億份聯邦文件遷移到SharePoint Online,並在此過程中即時重新映射了保留策略。安永和Adobe透過結合諮詢服務和電子簽章軟體包,僅用12週就提供了符合巴塞爾協議III的審計追蹤。到2025年,軟體授權將佔據66.12%的市場。軟體仍然至關重要,但在超大規模資料中心業者的價格壓力下,授權費用正以每年10-15%的速度下降。
隨著買家對承包解決方案的需求日益成長,擁有強大諮詢部門的供應商,例如 IBM、Hyland 和 OpenText,正在確保其收入來源的穩定性。同樣,對於缺乏全天候 IT 支援的中型企業而言,託管服務也極具吸引力。 DocuWare 的雲端服務透過捆綁備份和修補程式,將整體擁有成本 (TCO) 降低了 30%。因此,文件管理系統服務市場的成長速度超過了授權收入的成長速度,從而重塑了供應商的經營模式。
區域分析
2025年,北美地區佔總收入的37.53%,這主要得益於美國聯邦政府設定的數位化最後期限以及加拿大要求所有聯邦機構在2027年3月前遷移到雲端儲存庫的指令。雖然Microsoft 365的高採用率正在加速其普及,但隨著企業延長平台的生命週期並專注於人工智慧附加元件而非替代方案,成長速度正在放緩。
預計到2031年,亞太地區將以每年18.43%的速度成長。印度的「數位印度」計畫在其2025-2026財政年度預算中累計149.03億印度盧比(約18億美元)用於電子政府。中國的「數位管治道府縣”,預計訂單將增加35%。澳洲修訂後的《隱私權法》規定,資料外洩發生後必須在72小時內通知相關機構,這迫使各組織實施即時審計追蹤。
歐洲、中東和非洲的資料治理現況參差不齊,受到GDPR和在地化法規的影響。歐盟資料管治法強制要求供應商營運區域資料中心。德國網路安全機構建議關鍵基礎設施採用本地部署或混合部署模式。海灣國家的智慧城市項目,例如杜拜智慧城市2030,將資料儲存庫整合到電子政府服務中。南非的《個人資訊保護法》(POPIA)正在推動銀行和電信業者採用基於使用者許可的資料存檔方式。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 快速過渡到無紙化社會
- 整合到協作套件中的雲端原生文件管理系統平台
- 人工智慧顯著提升了搜尋功能和自動分類準確率。
- 嚴格的資料主權法規正在推動對這些法規的遵守。
- 行業專用模板的興起正在縮短引進週期。
- 由生成式人工智慧助理實現的上下文感知內容創作工作流程。
- 市場限制因素
- 使用者對受監管的後勤部門營運變革存在強烈的抵觸情緒。
- 由於元資料管理不善,導致電子證據揭示(E-Discovery)成本高昂。
- 勒索軟體攻擊DMS後,網路保險費上漲。
- 對供應商鎖定的擔憂延緩了從傳統企業內容管理 (ECM) 系統向新系統的過渡。
- 產業價值/價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 價格分析
- 產業生態系分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按組件
- 軟體
- 服務
- 部署模式
- 雲
- 現場
- 按最終用戶行業分類
- 銀行和金融服務
- 製造業/建築業
- 教育
- 衛生保健
- 零售
- 法律
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 肯亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software Inc.
- Oracle Corporation
- Box Inc.
- Adobe Inc.
- Laserfiche
- M-Files Corp.
- Alfresco(Hyland)
- Dropbox Business
- Zoho Corporation
- DocStar(Epicor)
- AODocs
- LogicalDOC Srl
- Agiloft Inc.
- Synergis Technologies
- Everteam
- FileHold Systems
- PaperSave
- DocuWare GmbH
- Newgen Software Technologies
- Canon Inc.
- Xerox Holdings Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the document management systems market size is projected to expand from USD 10.48 billion in 2025 and USD 11.81 billion in 2026 to USD 21.39 billion by 2031, registering a CAGR of 12.61% between 2026 to 2031.
This report is Segmented by Component (Software, and Services), Deployment Mode (Cloud, and On-Premise), End-User Industry (Banking and Financial Services, Manufacturing and Construction, and More), and Geography (North America, South America, Europe, Asia Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Document Management Systems Market Trends and Insights
Rapid Shift Toward Paper-Free Processes
Government mandates are accelerating digital conversion far faster than voluntary sustainability initiatives. The U.S. National Archives requires every federal agency to digitize permanent records by December 2026. Japan's Digital Agency ordered all prefectures to adopt paperless workflows by April 2025, triggering a 35% jump in procurements. Canon processed 18 billion pages through its cloud-scanning service in 2025, up 22% from 2024, illustrating the flood of analog content entering repositories. Rising capture volumes trim storage costs but inflate metadata-tagging labor, a trade-off that favors AI-driven auto-classification over manual indexing. Enterprises therefore prioritize platforms with built-in machine-learning enrichers that satisfy compliance while slashing operating expense.
Cloud-Native DMS Platforms Bundled Inside Collaboration Suites
Hyperscalers now embed repositories directly in collaboration tools, bypassing lengthy procurement. Microsoft launched SharePoint Embedded in March 2024; by January 2025, more than 200 ISVs had adopted the service. Box deepened integration with Google Workspace in June 2025, and pilot clients recorded 40% fewer version-control errors. Bundled offerings command 15-20% price premiums because they deliver seamless interoperability, forcing pure-play vendors to compete on vertical depth rather than horizontal features.
Persistent User-Change Resistance in Regulated Back-Office Functions
Deloitte found that 38% of financial-services compliance staff still print filings for manual review, doubting the evidentiary strength of digital signatures. Civil-law jurisdictions that require notarized deeds maintain hybrid processes, prolonging change-management programs to two years and inflating training budgets to USD 0.5-2 million per enterprise. Resistance delays ROI and moderates cloud-migration momentum.
Other drivers and restraints analyzed in the detailed report include:
- Surge in AI-Enhanced Search and Auto-Classification Accuracy
- Strict Data-Sovereignty Rules Driving Compliant Roll-Outs
- High E-Discovery Costs From Poor Metadata Hygiene
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services are growing at a 17.21% CAGR because migration complexity, AI tuning, and compliance mapping outstrip in-house skills. KnowledgeLake migrated 450 million federal documents to SharePoint Online in six weeks, remapping retention policies on the fly. EY and Adobe deliver Basel III audit trails in only 12 weeks through a bundled advisory and e-signature package. Software licenses held a 66.12% market share in 2025. Software remains indispensable, yet license fees fall 10-15% annually under hyperscaler price pressure.
As buyers seek turnkey outcomes, vendors with strong consulting arms, such as IBM, Hyland, and OpenText, capture stickier revenue. Managed services likewise appeal to mid-market firms lacking 24-hour IT coverage; DocuWare's cloud service bundles backup and patching to cut the total cost of ownership by 30%. Consequently, the document management systems market size for services is expanding faster than license revenue and reshaping vendor business models.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-Premise
- By End-User Industry
- Banking and Financial Services
- Manufacturing and Construction
- Education
- Healthcare
- Retail
- Legal
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America delivered 37.53% of 2025 revenue, helped by U.S. federal digitization deadlines and a Canadian directive that all federal departments move to cloud repositories by March 2027. High Microsoft 365 penetration speeds deployment, yet growth moderates as enterprises stretch platform life cycles and focus on AI add-ons rather than replacements.
Asia Pacific will grow at 18.43% through 2031. India's Digital India program earmarked INR 14,903 crore (USD 1.8 billion) for e-governance in its 2025-2026 budget. China's Digital Silk Road funds state-enterprise deployments to standardize cross-border trade documents. Japan mandated paperless prefectures by April 2025, spurring a 35% order increase. Australia's amended Privacy Act requires breach notification within 72 hours, pushing organizations toward real-time audit trails.
Europe, the Middle East, and Africa form a patchwork shaped by GDPR and localization rules. The EU Data Governance Act obliges vendors to run regional data centers. Germany's cybersecurity agency advises on-premise or hybrid deployments for critical infrastructure. Gulf smart-city programs such as Dubai Smart 2030 embed repositories into e-government services. South Africa's POPIA drives banks and telecoms toward consent-managed archives.
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software Inc.
- Oracle Corporation
- Box Inc.
- Adobe Inc.
- Laserfiche
- M-Files Corp.
- Alfresco (Hyland)
- Dropbox Business
- Zoho Corporation
- DocStar (Epicor)
- AODocs
- LogicalDOC Srl
- Agiloft Inc.
- Synergis Technologies
- Everteam
- FileHold Systems
- PaperSave
- DocuWare GmbH
- Newgen Software Technologies
- Canon Inc.
- Xerox Holdings Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Shift Toward Paper-Free Processes
- 4.2.2 Cloud-Native DMS Platforms Bundled Inside Collaboration Suites
- 4.2.3 Surge in AI-Enhanced Search and Auto-Classification Accuracy
- 4.2.4 Strict Data-Sovereignty Rules Driving Compliant Roll-Outs
- 4.2.5 Rise of Industry-Specific Templates Shortening Deployment Cycles
- 4.2.6 Generative-AI Copilots Unlocking Content-in-Context Workflows
- 4.3 Market Restraints
- 4.3.1 Persistent User-Change Resistance in Regulated Back-Office Functions
- 4.3.2 High E-Discovery Costs From Poor Metadata Hygiene
- 4.3.3 Cyber-Insurance Premiums Rising After DMS-Centred Ransomware Events
- 4.3.4 Vendor Lock-In Concerns Slowing Migration From Legacy ECMs
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Pricing Analysis
- 4.9 Industry Ecosystem Analysis
- 4.10 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By End-User Industry
- 5.3.1 Banking and Financial Services
- 5.3.2 Manufacturing and Construction
- 5.3.3 Education
- 5.3.4 Healthcare
- 5.3.5 Retail
- 5.3.6 Legal
- 5.3.7 Other End-User Industries
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 South Korea
- 5.4.4.4 India
- 5.4.4.5 Australia
- 5.4.4.6 New Zealand
- 5.4.4.7 Rest of Asia Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Kenya
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software Inc.
- 6.4.5 Oracle Corporation
- 6.4.6 Box Inc.
- 6.4.7 Adobe Inc.
- 6.4.8 Laserfiche
- 6.4.9 M-Files Corp.
- 6.4.10 Alfresco (Hyland)
- 6.4.11 Dropbox Business
- 6.4.12 Zoho Corporation
- 6.4.13 DocStar (Epicor)
- 6.4.14 AODocs
- 6.4.15 LogicalDOC Srl
- 6.4.16 Agiloft Inc.
- 6.4.17 Synergis Technologies
- 6.4.18 Everteam
- 6.4.19 FileHold Systems
- 6.4.20 PaperSave
- 6.4.21 DocuWare GmbH
- 6.4.22 Newgen Software Technologies
- 6.4.23 Canon Inc.
- 6.4.24 Xerox Holdings Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 企業員工檔案管理工具市場分析與預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能、解決方案
 文件管理系統市場規模、市場佔有率、全球產業分析、區域趨勢、成長率及2026-2034年預測。
 企業文件管理系統市場:依組件、部署類型、文件類型、組織規模與產業分類-2026-2032年全球市場預測
 人力資源文件管理與電子簽章:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)
 文件自動化軟體市場預測至2034年-按元件、部署模式、文件類型、應用、最終使用者和地區分類的全球分析
 2026年全球通訊與協作服務市場報告財務文件管理解決方案市場預測至2034年-按文件功能、文件類型、技術、部署模式和最終使用者分類的全球分析
 2026-2030年全球文件管理系統市場
 文件管理系統市場報告:按交付方式、部署方式、組織機構、應用領域和地區分類(2026-2034 年)全球文件管理系統市場規模、佔有率、趨勢和成長分析報告(2026-2034年)