


 |
市場調查報告書
商品編碼
2121334
1,4-丁二醇:市佔率分析、產業趨勢與統計、成長預測(2026-2031)1,4 Butanediol - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,1,4-丁二醇的市場規模在 2026 年估計為 266 萬噸,預計到 2031 年將達到 318 萬噸,在預測期(2026-2031 年)內以 3.64% 的複合年成長率成長。
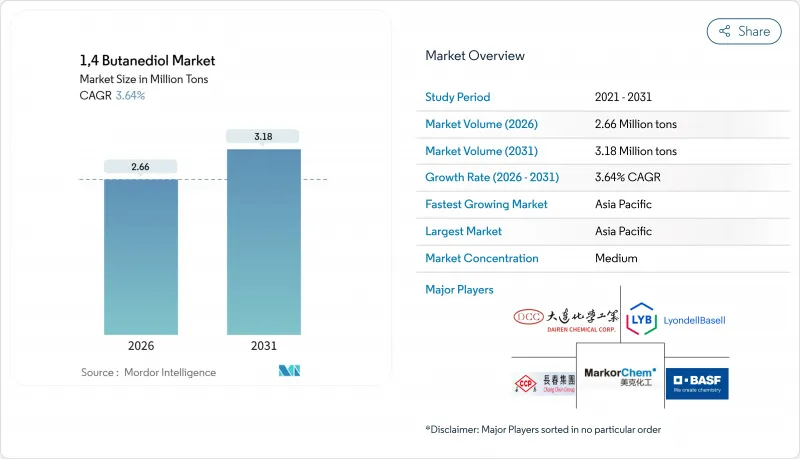
本報告按生產流程(萊普法、戴維法、丁二烯基法、環氧丙烷基法等)、衍生性商品(四氫呋喃(THF)等)、終端用戶產業(汽車、電氣電子、醫療製藥等)和地區(亞太、北美、歐洲、南美、中東和非洲)進行細分。市場預測以噸為單位。
全球1,4-丁二醇市場趨勢及洞察
對四氫呋喃和氨綸纖維的需求不斷成長
四氫呋喃 (THF) 仍然是聚四亞甲基醚二醇 (PTMEG) 的關鍵原料,而 PTMEG 是氨綸的柔軟成分。BASF在全球營運五家 PolyTHF 工廠,並預計到 2025 年,亞太地區工業紡織品技術級產品的銷售量將實現兩位數成長。曉星科技 (Hyosung) 已在其 2025 年推出的「regen BIO」氨綸產品中添加了生物基丁二醇 (bio-BDO),並在歐洲和北美服裝市場實現了 10-15% 的價格溢價。由於服裝產品的庫存補充週期恢復正常的速度快於耐用消費品的需求,THF 可以起到緩衝宏觀經濟衝擊的作用。除了紡織業,PTMEG 的需求範圍也在不斷擴大,例如被用於生產醫用導管和汽車內飾薄膜等熱塑性聚氨酯 (TPU) 產品。
減輕電動車連接器重量的需求正在推動 PBT 的應用。
高壓電動車 (EV) 平台需要阻燃、耐水解且尺寸穩定的連接器外殼。由 BDO 合成的 PBT 符合這些要求,並正在 400-800 V 架構中取代 PA 6,6。BASF的「Ultradur」牌號產品已通過 UL 94 V-0 測試,並已獲得歐洲和中國多家 OEM 製造商的採用決定,預計將於 2025 年前投入使用。 5G 基地台安裝和資料中心建設的不斷增加正在推動對用於高溫斷路器外殼的 PBT 的需求,進一步鞏固了其 3.79% 的預期複合年成長率。
職業安全與健康問題
1,4-丁二醇對眼睛、皮膚和呼吸系統有刺激性,長期接觸會抑制中樞神經系統。歐洲化學品管理局 (ECHA) 和美國政府工業衛生學家協會 (ACGIH) 已製定了接觸閾值,鼓勵企業投資建造封閉式運輸系統和蒸氣回收系統。遵守相關法規可能會使每噸營運成本增加 50 至 100 美元,資金充足的生產商將從中受益。 2024 年至 2025 年間,新疆和山西的幾家工廠因通風系統維修而暫時停產,導致該地區供應暫時短缺。
細分市場分析
即使到了2025年,乙炔化學品的萊普法仍將佔總產量的50.18%,這反映了數十年來基礎設施的累積。這些基礎設施將確保依賴萊普法裝置的1,4-丁二醇市場規模在2031年之前保持強勁。然而,在碳排放獎勵導致煤基原料專案獲利能力下降的背景下,生物發酵法的產量正以每年7.52%的速度成長。 Genomatica公司的GENO技術為BASF的一體化生產和曉鬆的越南工廠提供支持,證明發酵技術可以擴展到5萬噸級的生產線,並將生命週期排放量減少90%。由於變動成本高昂且擁有者有限,環氧丙烷和丁二烯的生產路徑仍屬於小眾市場。
目前,製程經濟性取決於碳計量。即將於歐洲實施的《工業排放指令》修正案將收緊乙炔工廠揮發性有機化合物(VOC)排放的限制,從而增加合規成本;而生物法製程則可避免乙炔處理相關的風險。中國在2060年實現碳中和的承諾正迫使地方政府遏制煤製乙炔設施的擴張,儘管萊普公司擁有穩固的業務基礎,但其市場佔有率正在逐步下降。
區域分析
預計到2025年,亞太地區將佔全球乙炔產量的76.12%,並在2031年之前以3.94%的複合年成長率成長。新疆、山西和內蒙古等地的乙炔生產叢集利用中國煤炭生產乙炔,滿足了該地區的大部分需求,但更嚴格的能源強度和安全審計導致了間歇性停產。曉星集團在越南投資10億美元的乙炔生產計畫表明,東南亞正在進入高階低碳供應市場,這未來可能會削弱中國在乙炔出口領域的主導地位。印度的需求正以兩位數的速度成長,這主要得益於其紡織和汽車產業的擴張,但由於國內產能不足,印度依賴從韓國和中東進口乙炔。
在北美和歐洲,生物基丁二醇(bio-BDO)產能正在擴大,以應對碳邊境調節措施(CBAM)和範圍3目標帶來的處罰。BASF、Qore和Novamont三家公司已總合,計劃在2024年至2026年間將其發酵基丁二醇產能每年提高10萬噸以上。當地需求正轉向高附加價值的TPU、PBT和醫藥中間體,這為生產商提供了抵禦原料價格波動的緩衝。
沙烏地阿拉伯的Sipchem公司運作一座年產能5萬噸的工廠,該工廠採用低成本乙烷,主要針對聚氨酯和溶劑市場。巴西的汽車和紡織業是南美聚氨酯消費的主要驅動力,但物流和外匯障礙阻礙了新的投資。非洲的需求仍處於起步階段,主要集中在南非的聚氨酯塗料領域,但基礎設施不足仍是一大障礙。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對四氫呋喃和氨綸纖維的需求不斷成長
- 電動車對更輕型連接器的需求推動了 PBT(聚苯乙烯泡沫)的採用。
- 聚氨酯的應用範圍不斷擴大
- 政府對生物基丁二醇生產能力的補貼
- 中國內陸地區煤製乙炔成本效益高的一體化工藝
- 市場限制因素
- 職業安全與健康方面的擔憂
- 原料(乙炔、丁二烯、丙烯)價格波動較大。
- 碳關稅增加了煤炭衍生的BDO的出口成本。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 透過生產過程
- 萊佩方法
- 戴維工藝
- 丁二烯基工藝
- 以環氧丙烷為原料的工藝
- 生物發酵途徑
- 導數
- 四氫呋喃(THF)
- 聚丁烯對苯二甲酸酯(PBT)
- γ-丁內酯(GBL)
- 聚氨酯(PU)
- 其他衍生性商品
- 按最終用戶行業分類
- 車
- 紡織品
- 電氣和電子設備
- 醫療和藥品
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Ashland
- BASF
- Chang Chun Group
- CJ CHEILJEDANG CORP.
- DCC
- Genomatica, Inc.
- Grupa Azoty
- Henan Kaixiang Fine Chemical Co. Ltd
- Jiangsu Hailun Petrochemical Co. Ltd
- LyondellBasell Industries Holdings BV
- Markor Chemicals Group Co. Ltd
- Mitsubishi Chemical Group Corporation
- NAN YA PLASTICS CORPORATION
- Novamont SpA
- Shandong Yuanli Science And Technology Co. Ltd
- Shanxi Sanwei Group Co. Ltd
- Sinochem Internation Corporation
- Sipchem Company
- SK Geocentric Co., Ltd.
- Xinjiang Blue Ridge Tunhe Sci.& Tech. Co., Ltd.
- Xinjiang Tianye(Group)Co. Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the 1,4 butanediol market size is estimated at 2.66 million tons in 2026, and is expected to reach 3.18 million tons by 2031, at a CAGR of 3.64% during the forecast period (2026-2031).
This report is Segmented by Production Process (Reppe, Davy, Butadiene-Based, Propylene Oxide-Based, and More), Derivative (Tetrahydrofuran (THF) and More), End-User Industry (Automotive, Electrical & Electronics, Healthcare & Pharmaceuticals, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East & Africa). Market Forecasts are Provided in Terms of Volume (tons).
Global 1,4 Butanediol Market Trends and Insights
Rising Demand for THF and Spandex Fibers
Tetrahydrofuran remains the gateway molecule to polytetramethylene ether glycol, the soft segment in spandex. BASF operates five PolyTHF plants worldwide and reported double-digit volume growth in Asia-Pacific technical-textile grades during 2025. Hyosung integrated bio-BDO into its regen BIO spandex, launched in 2025, and is realizing 10-15% price premiums in European and North American apparel markets. Apparel restocking cycles normalize faster than durable-goods demand, giving THF a buffer against macro shocks. Beyond textiles, PTMEG grades flow into thermoplastic polyurethane (TPU) used in medical tubing and automotive interior films, broadening the demand base.
Light-Weighting of EV Connectors Spurring PBT Uptake
High-voltage electric-vehicle platforms require connector housings with flame-retardant, hydrolysis-resistant, and dimensional stability. PBT synthesized from BDO meets these criteria and is displacing PA 6,6 in 400-800 V architectures. BASF's Ultradur grades passed UL 94 V-0 testing and secured design wins at several European and Chinese OEMs in 2025. Rising 5 G base-station installations and data-center construction intensify PBT demand for high-temperature circuit-breaker housings, reinforcing its 3.79% CAGR outlook.
Occupational Health and Safety Concerns
1,4 Butanediol is an eye, skin, and respiratory irritant, and prolonged exposure depresses the central nervous system. The European Chemicals Agency and ACGIH enforce exposure thresholds, prompting investments in closed-loop transfer systems and vapor recovery. Compliance can add USD 50 to USD 100 per ton to operating costs, favoring well-capitalized producers. Several Xinjiang and Shanxi plants halted operations in 2024-2025 for ventilation retrofits, temporarily tightening regional supply.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Polyurethane Applications
- Government Subsidies for Bio-BDO Capacity
- Volatile Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reppe acetylene chemistry retained 50.18% of total output in 2025, reflecting decades of brownfield infrastructure. The installed base ensures that the 1,4 Butanediol market size tied to Reppe plants remains substantial through 2031. Even so, bio-fermentation grows 7.52% annually, propelled by carbon incentives that tilt project economics away from coal feedstocks. Genomatica's GENO technology underpins BASF's Verbund output and Hyosung's Vietnam complex, proving that fermentation can scale to 50,000-ton trains with 90% lower life-cycle emissions. Propylene-oxide and butadiene routes stay niche because of higher variable costs and limited license holders.
Process economics now hinge on carbon accounting. Europe's forthcoming Industrial Emissions Directive revision tightens VOC limits on acetylene plants, lifting compliance costs, while bio-routes sidestep acetylene-handling hazards. China's 2060 carbon-neutrality pledge pressures regional authorities to curb coal-to-acetylene expansions, gradually eroding Reppe's share despite its entrenched footprint.
Complete Report Scope:
- By Production Process
- Reppe Process
- Davy Process
- Butadiene-Based Process
- Propylene Oxide-Based Process
- Bio-fermentation Route
- By Derivative
- Tetrahydrofuran (THF)
- Polybutylene Terephthalate (PBT)
- Gamma-Butyrolactone (GBL)
- Polyurethane (PU)
- Other Derivatives
- By End-user Industry
- Automotive
- Textile
- Electrical and Electronics
- Healthcare and Pharmaceuticals
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 76.12% of global volume in 2025 and is set to grow at a 3.94% CAGR through 2031. China's coal-to-acetylene clusters in Xinjiang, Shanxi, and Inner Mongolia supply most regional needs but face tightening energy-intensity and safety audits, creating intermittent outages. Hyosung's USD 1 billion Vietnam complex marks Southeast Asia's entry into premium low-carbon supply and will eventually relieve Chinese export dominance. India's demand is climbing at double digits on the back of textile and automotive expansions, but lacks domestic capacity, relying on Korean and Middle-East imports.
North America and Europe, both regions, advance bio-BDO capacity to hedge CBAM penalties and Scope 3 targets. BASF, Qore, and Novamont collectively added more than 100,000 tpa of fermentation output between 2024 and 2026. Local demand tilts toward high-value TPU, PBT, and pharmaceutical intermediates, giving producers a margin buffer against feedstock volatility.
Saudi Arabia's Sipchem operates a 50,000 tpa unit integrated with low-cost ethane, targeting polyurethane and solvent markets. Brazil drives South American consumption across automotive and textile channels, yet logistical and currency hurdles slow new investment. Africa's demand is nascent, centered in South African polyurethane coatings, but infrastructure gaps remain a hurdle.
- Ashland
- BASF
- Chang Chun Group
- CJ CHEILJEDANG CORP.
- DCC
- Genomatica, Inc.
- Grupa Azoty
- Henan Kaixiang Fine Chemical Co. Ltd
- Jiangsu Hailun Petrochemical Co. Ltd
- LyondellBasell Industries Holdings B.V.
- Markor Chemicals Group Co. Ltd
- Mitsubishi Chemical Group Corporation
- NAN YA PLASTICS CORPORATION
- Novamont SpA
- Shandong Yuanli Science And Technology Co. Ltd
- Shanxi Sanwei Group Co. Ltd
- Sinochem Internation Corporation
- Sipchem Company
- SK Geocentric Co., Ltd.
- Xinjiang Blue Ridge Tunhe Sci.&Tech. Co., Ltd.
- Xinjiang Tianye (Group) Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for THF and spandex fibres
- 4.2.2 Light-weighting of EV connectors spurring PBT uptake
- 4.2.3 Expansion of polyurethane applications
- 4.2.4 Government subsidies for bio-BDO capacity
- 4.2.5 Cost-advantaged coal-to-acetylene integrations in inland China
- 4.3 Market Restraints
- 4.3.1 Occupational health and safety concerns
- 4.3.2 Volatile feedstock (acetylene, butadiene, propylene) prices
- 4.3.3 Carbon-border taxes raising cost of coal-based BDO exports
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Production Process
- 5.1.1 Reppe Process
- 5.1.2 Davy Process
- 5.1.3 Butadiene-Based Process
- 5.1.4 Propylene Oxide-Based Process
- 5.1.5 Bio-fermentation Route
- 5.2 By Derivative
- 5.2.1 Tetrahydrofuran (THF)
- 5.2.2 Polybutylene Terephthalate (PBT)
- 5.2.3 Gamma-Butyrolactone (GBL)
- 5.2.4 Polyurethane (PU)
- 5.2.5 Other Derivatives
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Textile
- 5.3.3 Electrical and Electronics
- 5.3.4 Healthcare and Pharmaceuticals
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information,Products and Services, and Recent Developments)}
- 6.4.1 Ashland
- 6.4.2 BASF
- 6.4.3 Chang Chun Group
- 6.4.4 CJ CHEILJEDANG CORP.
- 6.4.5 DCC
- 6.4.6 Genomatica, Inc.
- 6.4.7 Grupa Azoty
- 6.4.8 Henan Kaixiang Fine Chemical Co. Ltd
- 6.4.9 Jiangsu Hailun Petrochemical Co. Ltd
- 6.4.10 LyondellBasell Industries Holdings B.V.
- 6.4.11 Markor Chemicals Group Co. Ltd
- 6.4.12 Mitsubishi Chemical Group Corporation
- 6.4.13 NAN YA PLASTICS CORPORATION
- 6.4.14 Novamont SpA
- 6.4.15 Shandong Yuanli Science And Technology Co. Ltd
- 6.4.16 Shanxi Sanwei Group Co. Ltd
- 6.4.17 Sinochem Internation Corporation
- 6.4.18 Sipchem Company
- 6.4.19 SK Geocentric Co., Ltd.
- 6.4.20 Xinjiang Blue Ridge Tunhe Sci.&Tech. Co., Ltd.
- 6.4.21 Xinjiang Tianye (Group) Co. Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Advancements in Bio-Based Production Technologies

 生物基1,4-丁二醇:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)
 1,4-丁二醇市場:2026-2032年全球市場預測(依產品類型、製造流程、通路、應用及最終用途產業分類)
 1,4-丁二醇市場報告:按類型、衍生物、最終用途產業和地區分類(2026-2034 年)
 2026-2030年全球γ-丁內酯市場
 1,4-丁二醇全球市場規模、佔有率、趨勢和成長分析報告(2026-2034)2,3-丁二醇全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 丁二醇產能、產量、市場規模、平均價格及預測(2018-2034 年)
 1,4-丁二醇全球市場報告,2026年
 γ-戊內酯:全球市場佔有率和排名、總收入和需求預測(2025-2031 年)
 2,3-丁二醇的全球市場