


 |
市場調查報告書
商品編碼
2120712
雲端服務代理(CSB):市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Cloud Services Brokerage (CSB) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
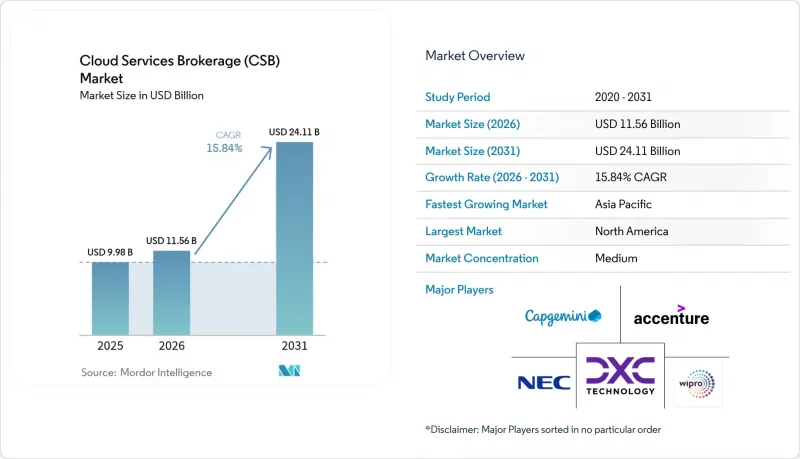
據估計,到 2026 年,雲端服務代理市場價值將達到 115.6 億美元,從 2025 年的 99.8 億美元成長到 2031 年的 241.1 億美元。
預計 2026 年至 2031 年的複合年成長率為 15.84%。
本報告按平台(內部和外部仲介仲介)、部署模式(公共雲端、私有雲端、混合雲端)、企業規模(中小企業和大型企業)、最終用戶行業(IT和電信、銀行、金融服務和保險、零售和消費品等)以及地區進行分類。
全球雲端服務經紀 (CSB) 市場趨勢與洞察
混合雲和多重雲端的採用率正在激增。
混合雲和多重雲端策略如今已成為資訊長 (CIO)藍圖的主導,預計到 2025 年,92% 的企業將採用多重雲端架構。由此產生的環境激增需要仲介平台將不同的環境整合到統一的策略域中,同時保護企業免受供應商鎖定。金融服務公司在這方面處於領先地位,因為資料居住法規限制了它們完全遷移到公共雲端。 Oracle 和 Google Cloud 之間的直接互連展示了服務仲介如何實現低延遲的跨雲端資料流,而無需經過開放的網際網路。容器的激增增加了複雜性,要求服務代理程式 (CSB) 提供高級 Kubernetes編配功能,以使 DevOps 團隊擺脫特定於主機的腳本編寫負擔。隨著邊緣工作負載的加入,仲介在本地、公有雲和邊緣節點之間提供統一的管治架構,最大限度地減少了技能差距和營運風險。
加速企業雲端支出
預計2025年,終端用戶雲端支出將達7,234億美元,較2024年成長21.20%。帳單的激增使財務長們面臨預算超支的風險,因此,財務營運(FinOps)專業知識已成為董事會層面的必備條件。 CSB平台現已整合機器學習演算法,用於預測使用量激增並觸發自動資源調整。銀行業的情況清楚地顯示了這一情況的緊迫性。儘管他們僅使用了49%的承諾雲端支出,但仍計劃進一步擴大預算分配,以運作需要高階GPU的AI模型。如果沒有仲介主導的風險管理措施,許多首席財務官擔心會出現“賬單衝擊”,即一個範圍不明確的資料科學項目就可能在短短幾個月內耗盡一整年的支出上限。
安全和合規問題
責任分擔模式令許多風險負責人感到困惑,尤其是在《數位服務法案》對雲端服務提供者施加新的通知和執行規則之後。雲端仲介必須支援跨所有連線提供者的細粒度存取控制、地理圍籬和防篡改稽核日誌。實施此類高級措施會增加研發成本並延長銷售週期,因為買家會要求徹底滲透測試的證據。身分管理仍然是最具挑戰性的環節。雲端服務經紀商必須在保持最小權限預設值的同時,聯合 Azure AD、AWS IAM 和 Google Identity 的憑證。
細分市場分析
受廠商中立性和成熟功能集的推動,外部仲介輔助平台預計到2025年將佔據雲端服務仲介市場50.60%的佔有率。同時,內部仲介輔助平台預計將以18.45%的複合年成長率成長,這反映了經營團隊致力於將雲端管治原生整合到企業DevOps流程中的努力。隨著財富500強銀行和電信公司推出與ServiceNow、Jira和CI/CD堆疊整合的客製化門戶,預計到2031年,與內部平台相關的雲端服務仲介市場規模將成長一倍以上。
這種快速的內部成長得益於平台負責人數量的增加以及策略性收購,例如IBM以64億美元收購HashiCorp,後者為Terraform和Vault提供了整合自動化功能。此外,內部CSB從長遠來看可以降低許可成本,並使安全團隊能夠在程式碼層級整合組織特定的控制措施。外部供應商透過提供更快的價值實現速度和持續更新的市場整合,仍然佔據重要地位,並將自身定位為舊有系統、本地系統和仲介環境整合管理的「仲介」。
在超大規模資料中心業者雲端服務商不斷擴展可用區的推動下,公共雲端服務在2025年仍將佔據雲端服務仲介市場53.20%的佔有率。然而,隨著財務長權衡資料傳輸成本與合規要求,混合雲端的採用率正以20.05%的複合年成長率快速成長。歐盟的主權雲端計畫正促使買家將目光轉向那些將受監管資料保留在本地,並僅將分析處理靈活擴展到公共雲端容量的架構。微軟的「歐盟主權雲」顯然正是瞄準了這個趨勢。
隨著製造商希望在工廠現場處理對延遲敏感的工作負載,邊緣運算正進一步推動混合部署。目前,仲介正在將本地 Kubernetes叢集與雲端後端整合,以實現一鍵式工作負載遷移。隨著 5G 私有網路的日益普及,CSB主機除了管理傳統的 IaaS 資源外,預計還將管理本地 MEC 節點——這是僅處理公共雲端的仲介無法提供的功能。
區域分析
北美地區憑藉其較早的雲端運算成熟度和強大的合作夥伴生態系統,預計到2025年將繼續佔據全球整體收入的43.30%。金融服務和醫療保健機構主導雲端運算的普及,它們被能夠簡化《薩班斯-奧克斯利法案》和《健康保險流通與責任法案》(HIPAA) 報告流程的仲介所吸引。儘管由於半導體短缺導致區域機架成本持續上漲,仲介正透過最佳化工作負載部署到成本更低的區域來減輕其影響。隨著聯邦機構和國防相關企業對國內資料儲存保障的需求日益成長,圍繞「主權雲端」的討論愈演愈烈,迫使仲介獲得FedRAMP高級合規認證。
亞太地區是成長最快的地區,預計到2031年複合年成長率將達到18.22%。隨著從印度到日本的各國政府推行「雲端優先」政策,雲端運算預計將使該地區的GDP成長0.25%至2.23%。日本的Sakura Internet等雲端服務供應商正在將國內雲端服務與仲介功能結合,這吸引了那些關注跨境資料傳輸法規的企業的目光。同時,台灣和韓國的半導體製造群正在為本地資料中心部署確保零件供應,從而抵消地緣政治風險。
歐洲在監管方面處於領先地位。歐盟資料法和GAIA-X為資料可攜性和主權設定了嚴格的目標。微軟的主權藍圖和Oracle的歐盟合規雲預示著一種針對仲介疊加層最佳化的服務環境即將到來。中東、非洲和南美洲仍是新興市場,但潛力巨大。阿拉伯聯合大公國、沙烏地阿拉伯和巴西的國家數位經濟計畫正在資助超大規模資料中心業者的區域擴張,隨著連接差距的縮小,仲介的蓬勃發展也將迎來豐收。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 混合雲端和多重雲端的採用率正在激增。
- 加速企業雲端支出
- 統一成本與管治的必要性
- 超大規模資料中心業者市場的聯合銷售蓬勃發展
- CSB 中的 AI 驅動 FinOps
- 主權雲合規層
- 市場限制因素
- 安全和合規問題
- 中小企業對CSB的價值認知不足。
- 原生超大規模資料中心業者工具正在蠶食 CSB 的市場佔有率。
- 費用降低給利潤率帶來了壓力。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按平台
- 實施內部仲介功能
- 外部仲介整合功能
- 按部署模式
- 公共雲端
- 私有雲端
- 混合雲端
- 按公司規模
- 小型企業
- 大公司
- 按最終用戶行業分類
- IT/通訊
- 銀行業、金融服務業及保險業
- 零售和消費品
- 醫療保健和生命科學
- 政府/公共部門
- 製造業
- 媒體與娛樂
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 南美洲其他地區
- 歐洲
- 德國
- 英國
- 法國
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture
- IBM
- Wipro
- Capgemini
- DXC Technology
- NEC
- NTT Data
- Cognizant
- Jamcracker
- VMware
- Flexera(RightScale)
- Ingram Micro Cloud
- Arrow Electronics(CloudBlue)
- AppDirect
- Pax8
- Cloudmore
- Boomi
- DoubleHorn
- TietoEVRY
- Tech Mahindra
第7章 市場機會與未來展望
According to Mordor Intelligence, cloud services brokerage market size in 2026 is estimated at USD 11.56 billion, growing from 2025 value of USD 9.98 billion with 2031 projections showing USD 24.11 billion, growing at 15.84% CAGR over 2026-2031.
This report is Segmented by Platform (Internal Brokerage Enablement and External Brokerage Enablement ), Deployment Model (Public Cloud, Private Cloud, and Hybrid Cloud), Enterprise (Small and Medium-Sized Enterprises and Large Enterprises), End-User Industry (IT and Telecommunications, Banking, Financial Services and Insurance, Retail and Consumer Goods, and More), and Geography.
Global Cloud Services Brokerage (CSB) Market Trends and Insights
Hybrid and Multi-Cloud Adoption Surge
Hybrid and multi-cloud strategies now dominate CIO roadmaps, with 92% of enterprises expected to pursue multi-cloud architectures by 2025. The resulting sprawl demands brokerage platforms that stitch disparate environments into unified policy domains while shielding organizations from vendor lock-in. Financial services firms stand at the forefront because data-residency mandates bar outright public-cloud migration. Oracle's direct interconnect with Google Cloud demonstrates how service brokers enable low-latency cross-cloud data flows without traversing the open internet. Container proliferation compounds complexity, pushing CSBs to deliver deep Kubernetes orchestration so DevOps teams avoid juggling console-specific scripts. With edge workloads entering the mix, a broker offers one governance fabric spanning on-prem, public, and edge nodes, minimizing skills gaps and operational risk.
Enterprise Cloud-Spend Acceleration
End-user cloud spending is on track to hit USD 723.4 billion in 2025, a 21.20% jump over 2024 levels. Bigger invoices expose finance leaders to budget overruns, turning FinOps insight into a board-level mandate. CSB platforms now embed machine-learning algorithms that forecast consumption spikes and trigger automated right-sizing. Banks showcase the urgency: despite using only 49% of their committed cloud outlays, they plan to boost allocations further to run AI models requiring premium GPUs. Without broker-led guardrails, many CFOs fear "bill shock," where a single poorly scoped data-science project can wipe out annual spend thresholds within months.
Security and Compliance Concerns
Shared-responsibility models confuse many risk officers, especially when the Digital Services Act imposes fresh notice-and-action rules on cloud operators. Brokers must therefore support granular access controls, geo-fencing, and tamper-proof audit logs across every connected provider. Implementing such depth raises R&D costs and lengthens sales cycles as buyers demand exhaustive penetration-test evidence. Identity management remains the hardest element: CSBs must federate credentials across Azure AD, AWS IAM, and Google Identity while preserving least-privilege defaults.
Other drivers and restraints analyzed in the detailed report include:
- Need for Centralized Cost and Governance
- Hyperscaler Marketplace Co-Sell Boom
- Low SME Awareness of CSB Value
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
External Brokerage Enablement platforms accounted for 50.60% of the cloud service brokerage market share in 2025, thanks to their vendor-neutral appeal and mature feature sets. Internal Brokerage Enablement, however, is forecast to compound at 18.45% CAGR, reflecting management's push to embed cloud governance natively into enterprise DevOps pipelines. The cloud service brokerage market size tied to internal platforms is set to more than double by 2031 as Fortune 500 banks and telecoms spin up bespoke portals linked to ServiceNow, Jira, and CI/CD stacks.
This internal surge rides on rising platform-engineering headcount and strategic acquisitions such as IBM's USD 6.4 billion purchase of HashiCorp, which delivers Terraform and Vault automation under one roof. Internal CSBs also cut license spend over time and let security teams inject organization-specific controls at the code level. External vendors still hold ground by offering faster time-to-value and evergreen marketplace integrations, positioning themselves as "broker of brokers" layers that manage legacy, internal, and SaaS estates together.
Public Cloud services retained 53.20% of the cloud service brokerage market in 2025, propelled by ever-expanding hyperscaler availability zones. Yet, Hybrid Cloud deployments are sprinting ahead at 20.05% CAGR as CFOs weigh egress fees against compliance mandates. EU sovereign initiatives have nudged buyers toward architectures where regulated data stays on-prem while analytics elastically burst to public capacity, a pattern Microsoft's EU Sovereign Cloud expressly targets.
Edge computing further boosts hybrid adoption because manufacturers want latency-critical workloads processed on factory floors. Brokers now knit local Kubernetes clusters with cloud back-ends, granting one-click workload mobility. As 5G private networks spread, expect CSB consoles to manage on-prem MEC nodes alongside classic IaaS resources, a capability public-only brokers cannot match.
Complete Report Scope:
- By Platform
- Internal Brokerage Enablement
- External Brokerage Enablement
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Enterprise Size
- Small and Medium-sized Enterprises
- Large Enterprises
- By End-user Industry
- IT and Telecommunications
- Banking, Financial Services and Insurance
- Retail and Consumer Goods
- Healthcare and Life Sciences
- Government and Public Sector
- Manufacturing
- Media and Entertainment
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of the South America
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 43.30% of global revenue in 2025, owing to early cloud maturity and dense partner ecosystems. Financial services and healthcare providers dominate adoption, drawn to brokers that streamline Sarbanes-Oxley and HIPAA reporting. Semiconductor shortages continue to inflate regional rack costs, yet brokers mitigate the impact by optimizing workload placement across lower-cost zones. Sovereign-cloud conversations are growing louder as federal agencies and defense contractors seek domestic data-residency assurances, nudging brokers to certify FedRAMP High controls.
Asia Pacific is the fastest-growing territory at an 18.22% CAGR through 2031. Governments from India to Japan run "cloud-first" directives, while regional GDP uplift from cloud computing is estimated at 0.25%-2.23%. Japanese providers such as Sakura Internet now bundle brokerage functions with domestic clouds, appealing to firms wary of trans-border data transfer rules. Meanwhile, semiconductor manufacturing clusters in Taiwan and South Korea secure component supply for local data-center rollout, counterbalancing geopolitical risks.
Europe stands out for regulatory pull: the EU Data Act and GAIA-X lay down stringent portability and sovereignty targets. Microsoft's sovereign-cloud roadmap and Oracle's EU Regulated Cloud hint at a service landscape tailor-made for broker overlays. The Middle East and Africa, plus South America, remain emergent but promising; national digital-economy programs in the UAE, Saudi Arabia, and Brazil are funding hyperscaler region launches, planting fertile ground for broker uptake once connectivity gaps close.
- Accenture
- IBM
- Wipro
- Capgemini
- DXC Technology
- NEC
- NTT Data
- Cognizant
- Jamcracker
- VMware
- Flexera (RightScale)
- Ingram Micro Cloud
- Arrow Electronics (CloudBlue)
- AppDirect
- Pax8
- Cloudmore
- Boomi
- DoubleHorn
- TietoEVRY
- Tech Mahindra
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Hybrid and multi-cloud adoption surge
- 4.2.2 Enterprise cloud-spend acceleration
- 4.2.3 Need for centralized cost and governance
- 4.2.4 Hyperscaler marketplace co-sell boom
- 4.2.5 AI-driven FinOps within CSBs
- 4.2.6 Sovereign-cloud compliance layers
- 4.3 Market Restraints
- 4.3.1 Security and compliance concerns
- 4.3.2 Low SME awareness of CSB value
- 4.3.3 Native hyperscaler tools cannibalize CSBs
- 4.3.4 Fee-compression squeezes margins
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Platform
- 5.1.1 Internal Brokerage Enablement
- 5.1.2 External Brokerage Enablement
- 5.2 By Deployment Model
- 5.2.1 Public Cloud
- 5.2.2 Private Cloud
- 5.2.3 Hybrid Cloud
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium-sized Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-user Industry
- 5.4.1 IT and Telecommunications
- 5.4.2 Banking, Financial Services and Insurance
- 5.4.3 Retail and Consumer Goods
- 5.4.4 Healthcare and Life Sciences
- 5.4.5 Government and Public Sector
- 5.4.6 Manufacturing
- 5.4.7 Media and Entertainment
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of the South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture
- 6.4.2 IBM
- 6.4.3 Wipro
- 6.4.4 Capgemini
- 6.4.5 DXC Technology
- 6.4.6 NEC
- 6.4.7 NTT Data
- 6.4.8 Cognizant
- 6.4.9 Jamcracker
- 6.4.10 VMware
- 6.4.11 Flexera (RightScale)
- 6.4.12 Ingram Micro Cloud
- 6.4.13 Arrow Electronics (CloudBlue)
- 6.4.14 AppDirect
- 6.4.15 Pax8
- 6.4.16 Cloudmore
- 6.4.17 Boomi
- 6.4.18 DoubleHorn
- 6.4.19 TietoEVRY
- 6.4.20 Tech Mahindra
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


